


EN
Can Goodman Group (ASX:GMG) Justify Its Valuation On Pipeline Progress And Earnings Growth?
Goodman Group (ASX:GMG) put its development pipeline in focus after first quarter commentary highlighted projects progressing as planned, supported by demand for logistics facilities and data centers, as well as management’s forecast for higher operating earnings.
Goodman Group’s latest update landed after a sharp move in the stock, with a 1-day share price return of 7.03% and a 30-day share price return of 10.07%, even though the year to date share price return is down 6.68% and the 1-year total shareholder return is down 5.46%. Over a longer stretch, total shareholder return of 31.66% over three years and 28.91% over five years points to investors who stayed the course still seeing a solid payoff. The recent rebound indicates that the market may be reacting positively to Goodman Group’s development pipeline and earnings outlook.
Scan for other Goodman Group style infrastructure and logistics plays that are showing similar momentum in their development pipelines with the hand-picked 41 power grid technology and infrastructure stocks.
The rebound in Goodman Group has arrived quickly after a weaker patch, which puts you at a simple fork in the road: lean into the momentum now, or wait for a calmer entry and clearer valuation signals ahead?
Most Popular Narrative: 16% Undervalued
Goodman Group’s most followed valuation storyline points to a fair value of about A$34.10 per security against a last close of A$28.76. This puts the current rebound in the context of a wider gap between price and that narrative fair value, built on its data center and logistics pipeline.
Acceleration in data center development, supported by a global power bank of 6.4 gigawatts across 16 cities and around A$20b of work in progress that is more than 70% data centers, is expected to convert into contracted rent, fee income and development profits as projects such as Tsukuba Tech Central and LAX move from construction into leasing and eventual stabilization, supporting revenue and operating earnings.
See why 84 investors see Goodman Group as 16% undervalued.
Result: Fair Value of A$34.10 (UNDERVALUED)
Still, the narrative can unravel if A$18b plus of data center projects suffer cost overruns, or if large campuses like LAX and Tokyo lease more slowly than expected.
Find out about the key risks to this Goodman Group narrative.
Another View: Goodman Group Through The P/E Lens
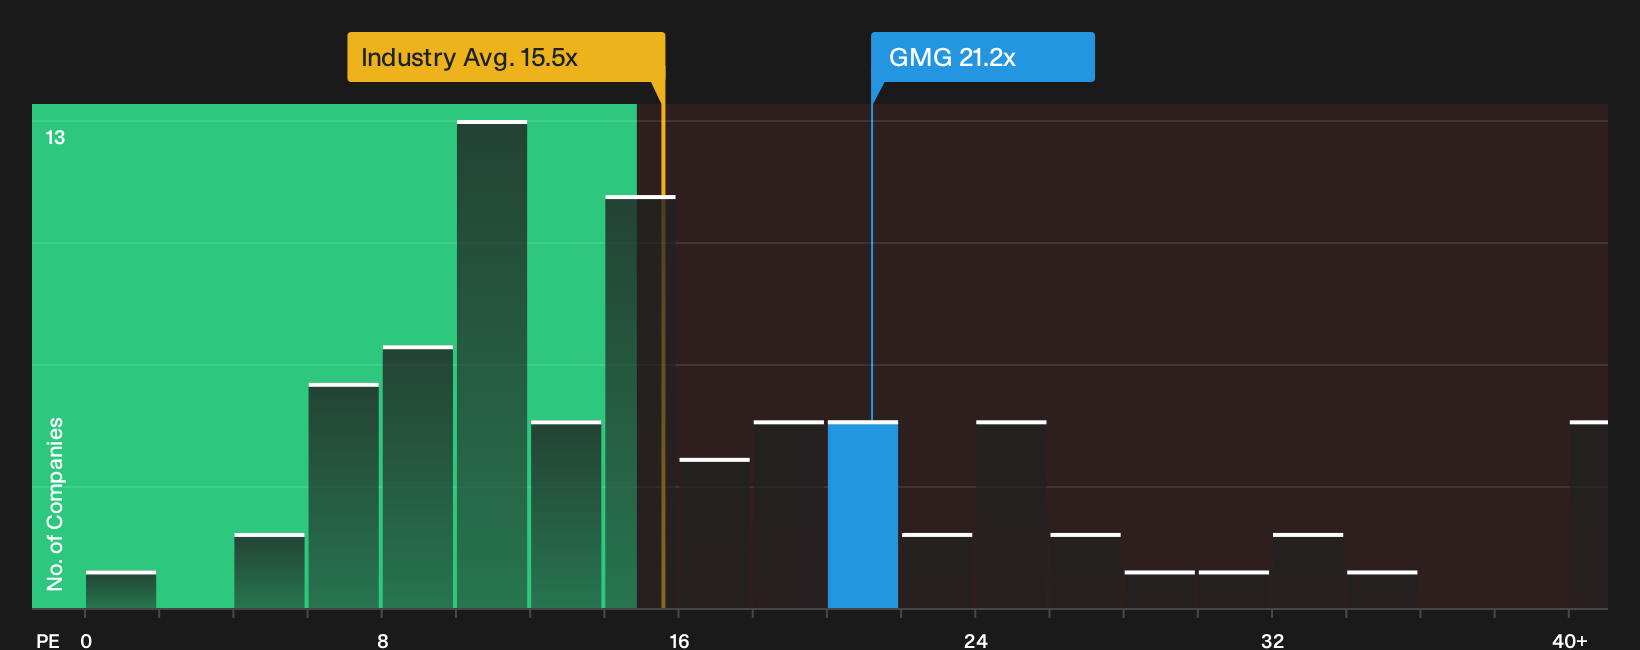
Goodman Group might look appealing on a fair value of A$34.10 against a A$28.76 price, yet its P/E of 21.2x tells a different story. The ratio is far above the fair ratio of 13x, the Australian Industrial REITs industry on 14.5x and peers on 12.2x. Is the premium a margin of safety or a margin of error?
Before leaning too heavily on any single valuation yardstick, it helps to see how the current pricing stacks up against the detailed ratio work in one place, then decide where you are comfortable on the risk and return trade off. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the market optimism in Goodman Group matches your own read of the story and the numbers? Move quickly to test that feeling against the 3 key rewards.
Looking for more investment ideas beyond Goodman Group?
If Goodman Group has sharpened your focus on quality pipelines and pricing, use that same mindset to source the next wave of ideas before they move without you.
- Target long-term compounding by zeroing in on resilient businesses with clean finances through a focused list of solid balance sheet and fundamentals (12 results).
- Hunt for pricing gaps where quality and value line up by working through the curated 5 high quality undervalued stocks.
- Stack potential income on top of capital growth by scanning yield opportunities in the carefully filtered 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com