


EN
GSK (LSE:GSK) Stock Looks Reasonable Following Jemperli Cancer Drug Approval
GSK shares have put in a solid multi‑year run, so the live question for anyone looking at the stock today is whether the current price is still adequately grounded in the earnings the business produces.
- Over the past 3 years the stock has returned about 49.1%, which puts real weight on whether that advance is matched by the strength and durability of its profit stream.
- The recent US approval for cancer drug Jemperli may support expectations for future earnings, since successful treatments in specialist areas can influence pricing power and long term cash generation.
- There is a second opinion on GSK worth weighing. See what analysts think GSK's shares could be worth.
The issue now is whether GSK's current valuation can be explained by its earnings profile when compared with a Fair Ratio benchmark.
If you want more than one idea built around earnings strength and durability, a focused screen of 5 resilient stocks with low risk scores is a useful next step in your research.
Is GSK Still Cheap on Earnings?
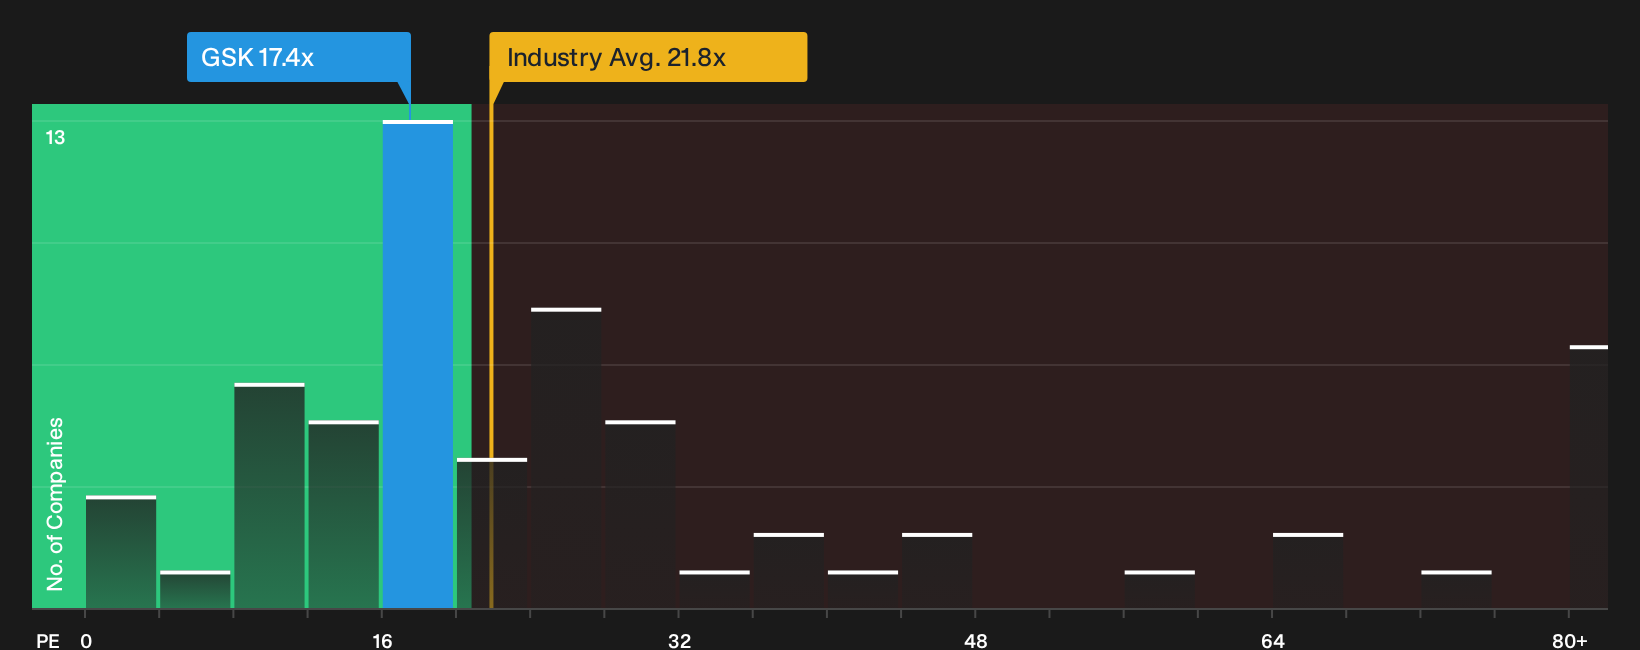
The P/E ratio suits a business like GSK because investors tend to focus on the earnings power behind its portfolio of treatments and vaccines. On this measure, GSK trades on about 17.4x earnings, which is below the Pharmaceuticals industry average of roughly 20.7x and sits far under a peer group closer to 48.1x.
The Fair Ratio framework, which looks at what multiple might be reasonable given GSK's margins, growth profile, scale and risk, points to a higher figure than the current 17.4x. On this basis, the stock screens as undervalued. Despite the recent Jemperli approval in the US lifting the story around future oncology income, the P/E still reflects a discount to both sector norms and similar businesses. Explore the numbers behind GSK's P/E valuation.
The GSK Narrative: What Would Justify Today's Price?
GSK's valuation puzzle only really comes into focus once you spell out the future that would need to unfold for today's multiple to look conservative or stretched. Simply Wall St Narratives on the Community page do exactly that for you, since each scenario links its number to a clear view on how GSK's growth, margins and risk profile might evolve, which you can revisit as fresh results and pipeline news arrive.
Bullish and bearish GSK holders are reading the same pipeline and cost plan, yet reaching very different conclusions about what is already priced in.
Bull case: 13% undervalued
"GSK is pushing deeper into long acting HIV injectables, with Cabenuva and Apretude driving a larger share of HIV division growth and backed by data showing Cabenuva superiority to daily oral therapy in high risk and viremic patients…"
Discover why this Narrative puts GSK at 13% undervalued.
Bear case: 30% overvalued
"Although GSK is pushing hard to lift its specialty medicines mix, the 9% decline in General Medicines sales in Q2 and the downgrade to full year guidance indicate structural pressure from aging brands and generic competition that could drag on revenue and dilute the margin uplift expected from higher priced therapies…"
Explore why this Narrative puts GSK at 30% overvalued.
For GSK, the share price is only half the story
Market pricing tells you what investors think today, while the projections built into analyst models hint at where they expect this business to be a few years from now. Explore where analysts expect GSK to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com