


EN
Is Wall Street Bullish or Bearish on International Paper Stock?
Memphis, Tennessee-based International Paper Company (IP) produces and sells renewable fiber-based packaging and pulp products. Valued at $18.9 billion by market cap, the company offers linerboard, medium, whitetop, recycled linerboard, recycled medium and saturating kraft, and pulp for a range of applications, such as diapers, towel and tissue products, feminine care, and other personal care products.
Shares of this global leader in sustainable packaging solutions have underperformed the broader market over the past year. IP has declined 1.3% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 13.5%. In 2026, IP stock is down 9%, compared to the SPX’s 12.3% gains on a YTD basis.
Narrowing the focus, IP’s underperformance is also apparent compared to the State Street Materials Select Sector SPDR ETF (XLB). The exchange-traded fund has gained about 27.6% over the past year. Moreover, the ETF’s 19.9% returns on a YTD basis outshine the stock’s high single-digit losses over the same time frame.
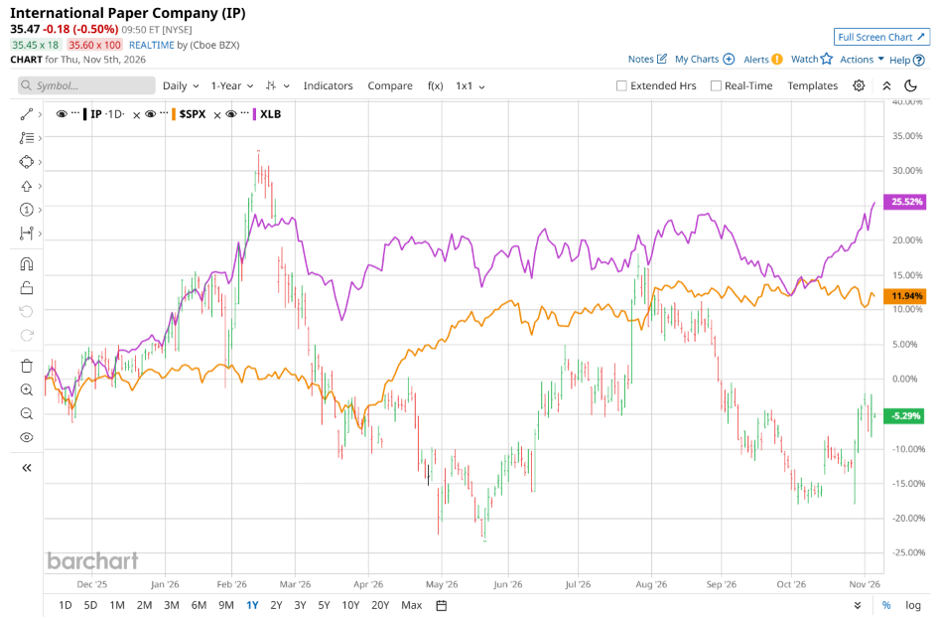
IP’s underperformance is visibly showcased through a stark contrast. While the company managed to beat Wall Street’s bottom-line profitability forecasts, reporting an adjusted EPS of $0.37 compared to analyst estimates of $0.29, via aggressive internal cost-cutting, structural plant closures, and pricing execution, its fundamental top-line growth remained constrained. Net sales came in at $6.2 billion, missing Wall Street estimates of $6.3 billion. This underlying struggle, compounded by stubborn input inflation (diesel, energy) and a massive $1.4 billion non-cash goodwill impairment charge in its EMEA Packaging Solutions segment, pushed the company into a headline net loss for the quarter, highlighting persistent regional headwinds and forcing management to pursue an urgent separation of the European business.
For the current fiscal year, ending in December, analysts expect IP’s EPS to grow 665% to $1.13 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in two of the last four quarters while missing the forecast on two other occasions.
Among the 13 analysts covering IP stock, the consensus is a “Strong Buy.” That’s based on 10 “Strong Buy” ratings, one “Moderate Buy,” and two “Holds.”
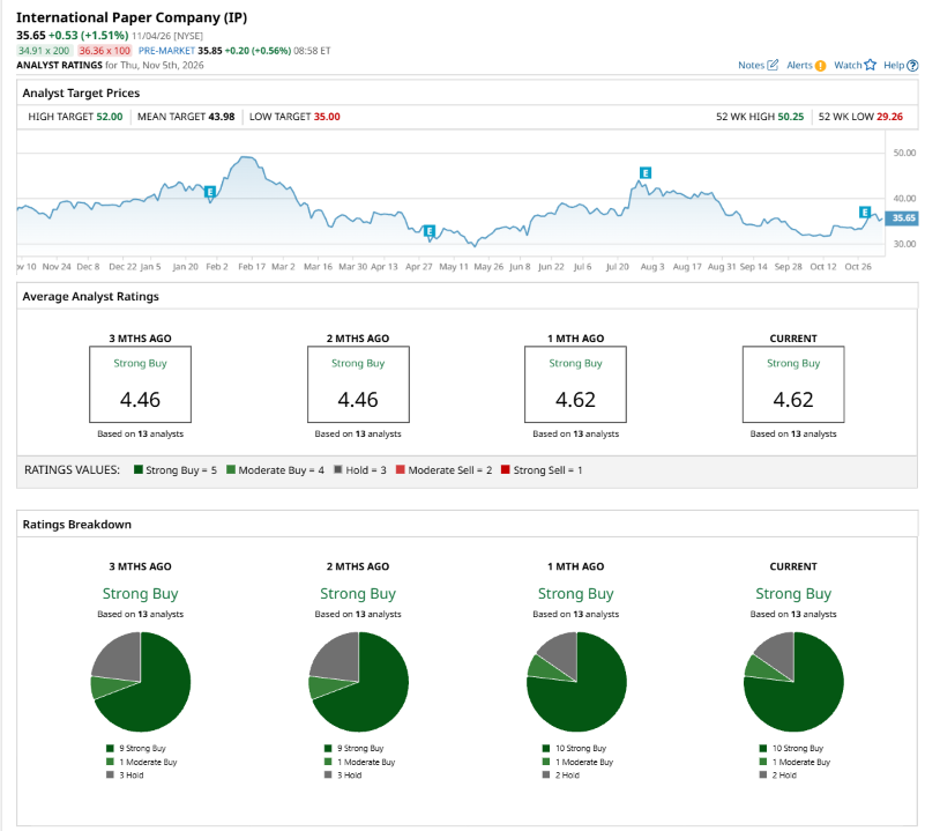
This configuration is more bullish than two months ago, with nine analysts suggesting a “Strong Buy.”
On Nov. 4, Matt McKellar from RBC Capital reiterated a “Buy” rating on IP, with a price target of $45, implying a potential upside of 26.2% from current levels.
The mean price target of $43.98 represents a 23.4% premium to IP’s current price levels. The Street-high price target of $52 suggests an ambitious upside potential of 45.9%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.