


EN
Kulicke and Soffa Industries (KLIC) Stock Dropped, So What Is Driving Attention Now?
Kulicke and Soffa Industries (KLIC) is back in focus after fresh commentary highlighted projected quarterly earnings of US$1.44 per share and revenue of US$375 million, with both figures indicating a sharp year-over-year improvement.
The upbeat earnings projections arrive after a sharp pullback in Kulicke and Soffa Industries’ shares, with the price down 5.52% over the last session, 13.85% over seven days, and 30.68% over the past month. Even so, the year-to-date share price return is still up 41.55%, and the 1-year total shareholder return sits at 75.35%, suggesting that long-term holders remain well ahead while short-term momentum has clearly cooled.
Scan beyond Kulicke and Soffa Industries and size up other semiconductor plays showing strong earnings momentum with our curated list of 53 AI infrastructure stocks.
Kulicke and Soffa Industries now trades well below the average analyst target, even after a strong longer term run. Is that discount mispricing renewed earnings optimism, or a fair reflection of lingering market caution about the cycle ahead?
Most Popular Narrative: 32% Undervalued
Kulicke and Soffa Industries closed at $68.44, while the most followed narrative pegs fair value at $100.33. This frames the recent pullback as a sizeable valuation gap rather than just a sentiment swing.
Management is preparing for a production ramp in Fluxless thermocompression and vertical wire into fiscal 2026, yet both are still in early phases with first HBM system shipments and initial vertical wire qualifications. Any delay or slower adoption in high bandwidth memory or on device AI could pressure the anticipated contribution to revenue growth and limit margin expansion.
See why 7 investors see Kulicke and Soffa Industries as 32% undervalued.
Result: Fair Value of $100.33 (UNDERVALUED)
Still, the Kulicke and Soffa Industries story can break if advanced packaging ramps slip or if power semiconductor and EV demand recover more slowly than analysts expect.
Find out about the key risks to this Kulicke and Soffa Industries narrative.
Another View: Kulicke and Soffa Industries Through A Cash Flow Lens
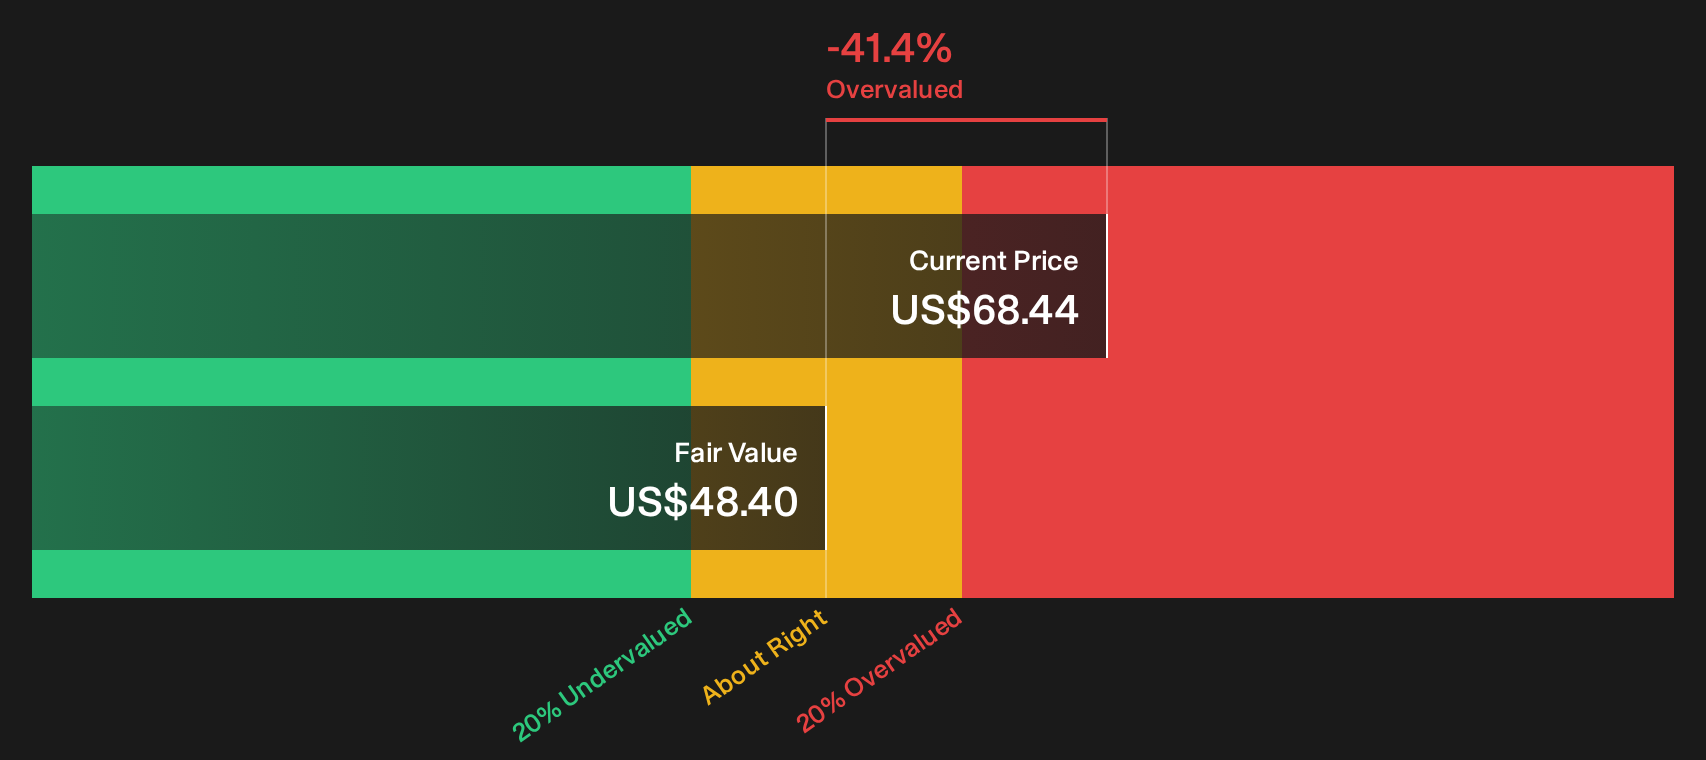
The earlier narrative leaned on analyst earnings and multiples to argue Kulicke and Soffa Industries looks undervalued around $68.44 versus a fair value of $100.33. Our DCF model tells a different story. Based on projected future cash flows, it points to a value of about $48.40, which implies the stock currently trades above that estimate.
The gap between a P/E based fair value near $100 and an SWS DCF outcome closer to $48.40 is wide enough that it raises a practical question. Are analysts building in more generous assumptions on growth durability and margins than long term cash generation currently supports? Or is the DCF framework being too strict about risk and required returns?
Our DCF model is only one framework, and every model is just a simplified version of reality. Use it as a cross check on the earnings based narrative, not a verdict, and decide which set of assumptions you find more realistic for Kulicke and Soffa Industries over a full cycle. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kulicke and Soffa Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Kulicke and Soffa Industries can be useful if you act before sentiment shifts again. Be sure to weigh both sides for yourself with 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Kulicke and Soffa Industries?
If you stop with Kulicke and Soffa Industries, you only see part of the opportunity set. Broaden your watchlist and give yourself more ways to win.
- Target resilient performers that can handle rough patches by scanning a 31 resilient stocks with low risk scores built around financial strength and historically steadier trading profiles.
- Hunt for quality at a reasonable entry point by checking a 35 high quality undervalued stocks that filters for strong fundamentals at prices that still look restrained.
- Build a portfolio that works for you even when markets pause by reviewing a 5 dividend fortresses focused on higher yielding, income oriented stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com