


EN
Does Earnings Beat Change The Bull Case For Emerson Electric Stock (EMR)?
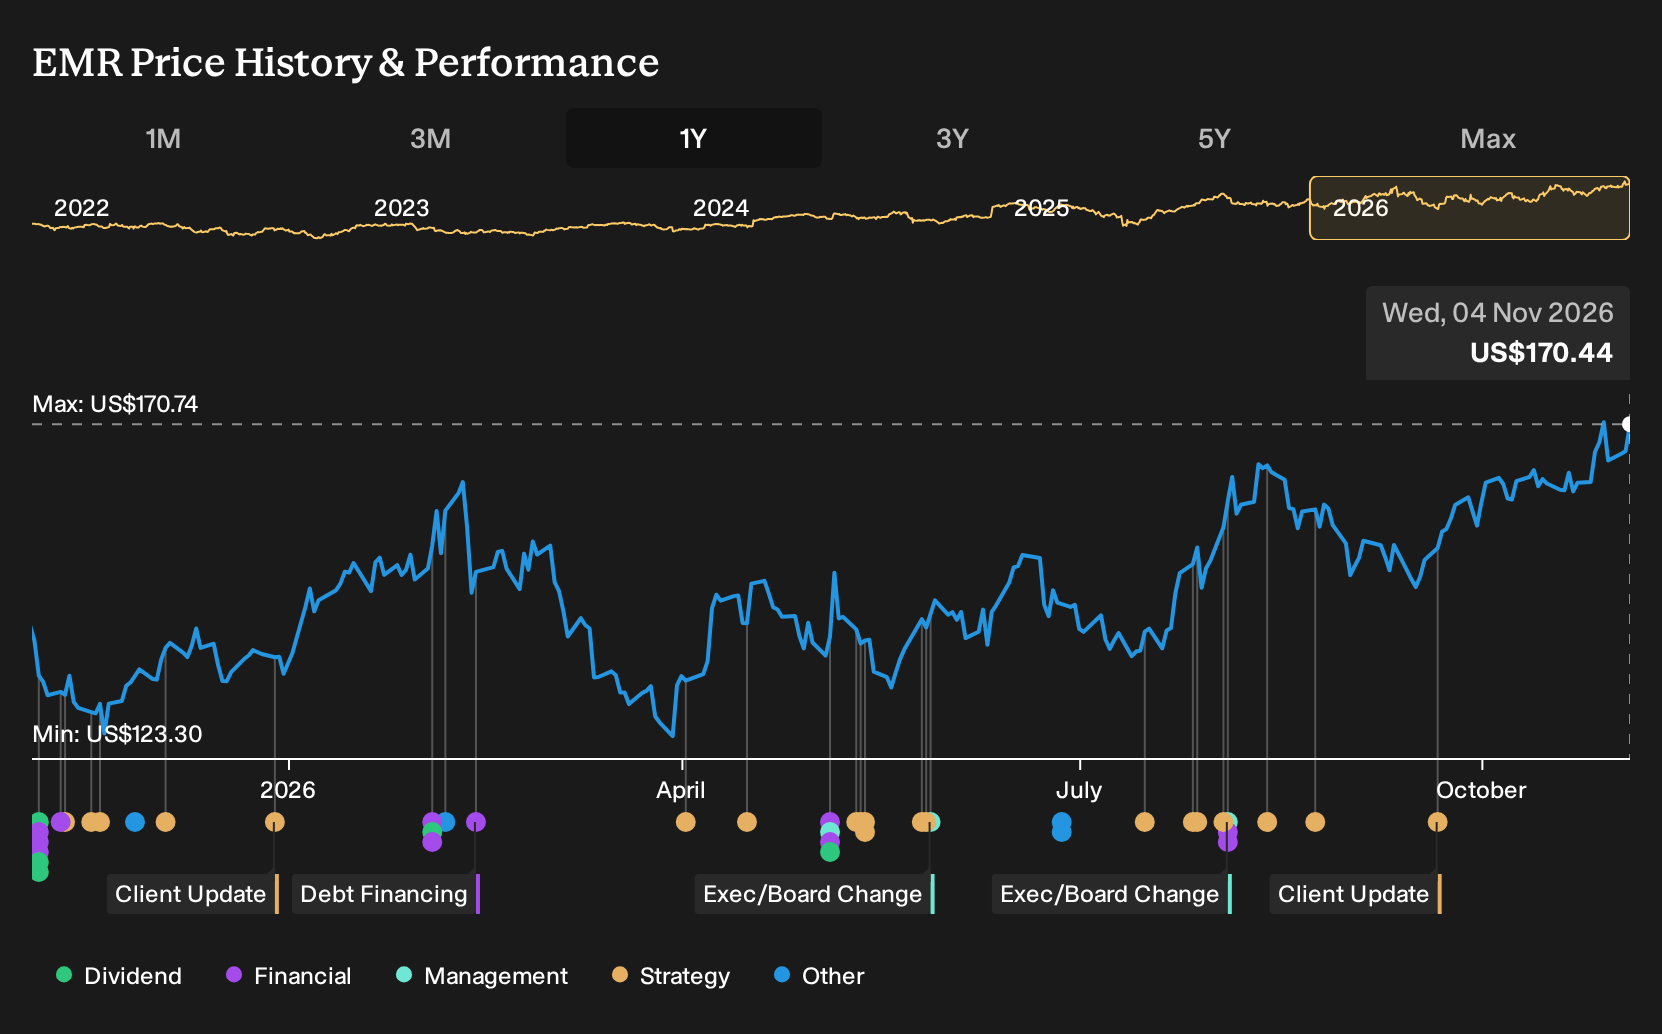
- Emerson Electric reported quarterly revenue of US$5.2b and earnings of US$1.86 per share that were above consensus, issued 2027 guidance that targets about 5% net sales growth and around US$5.70 in EPS, and raised its quarterly dividend by 7% to US$0.595 per share.
- The combination of higher earnings, fresh guidance for 2027 and a larger cash payout signals management confidence in cash generation, project execution and the health of core automation and software demand across power, LNG, and test and measurement markets.
- This article will examine how Emerson Electric's investment narrative around automation and software-led growth is affected by management's 7% dividend increase and earnings guidance.
Scan beyond Emerson Electric and line up other automation and infrastructure contenders by reviewing the hand picked 41 power grid technology and infrastructure stocks shaping tomorrow's energy and industrial projects.
Emerson Electric Investment Narrative Recap
To own Emerson Electric, you need to be comfortable with an automation and software story that leans on power, LNG, Test & Measurement and recurring software revenue. The latest quarter showed higher sales and earnings per share than a year earlier, which supports that narrative but does not remove exposure to Middle East project disruption or weaker demand in China.
The new 2027 guidance for about 5% net sales growth and roughly US$5.70 in EPS keeps the near term catalyst squarely on execution of the existing project funnel. The biggest operational risk still sits in project timing and regional disruptions, rather than in any single quarter of reported results.
The most relevant new data point is the 2027 outlook. Management is framing the business around roughly 5% annual net sales growth and earnings per share of about US$5.70. For investors, the focus is on whether Emerson Electric can convert its power, LNG, software and Test & Measurement pipelines into consistent revenue that supports those figures.
This guidance interacts directly with the key catalyst, which is continued adoption of digital automation and AI-led solutions such as Ovation 4.0 and the Nigel AI adviser. It also tests the firm against its main risks, including project delays, Middle East related interruptions and ongoing softness in China chemicals, where further weakness could make that US$5.70 EPS harder to reach.
Emerson Electric's current earnings of US$2.6b are set against analyst projections for US$21.9b in revenue and US$3.8b in earnings by 2029. This implies forecast revenue growth of 5.6% per year and an earnings increase of US$1.2b from today.
Uncover why Emerson Electric's fair value is essentially consistent with its current price.
Exploring Other Perspectives
One bullish catalyst that highest ranked analysts kept highlighting before this dividend and guidance news was Emerson Electric's AI heavy software push. This group was sketching out a world where revenue could reach about US$22.8b and earnings about US$4.0b by 2029. That is a more optimistic script than the consensus, and these fresh numbers may nudge both stories in new directions.
Explore 3 other Emerson Electric fair value estimates, including one that suggests it could be worth as much as $174.82.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Emerson Electric research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Emerson Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Emerson Electric's overall financial health at a glance.
Looking For More Investment Ideas Beyond Emerson Electric?
If Emerson Electric's mix of automation, software and infrastructure exposure has your attention, it can help to compare it with other opportunities that match your preferred balance of quality, risk and income potential. The Simply Wall St Screener lets you filter the market down to a smaller, more focused watchlist that fits your own approach rather than copying consensus.
- For investors who want strong fundamentals at a discount, check out a curated group of 35 high quality undervalued stocks that combine quality with pricing that may appeal to value focused portfolios.
- If resilience and capital preservation matter most to you, start with a 31 resilient stocks with low risk scores that screens for businesses with steadier profiles and lower risk scores.
- When you are hunting for future leaders before they are widely followed, use a 19 high quality undiscovered gems that highlights under-the-radar companies with solid financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com