


EN
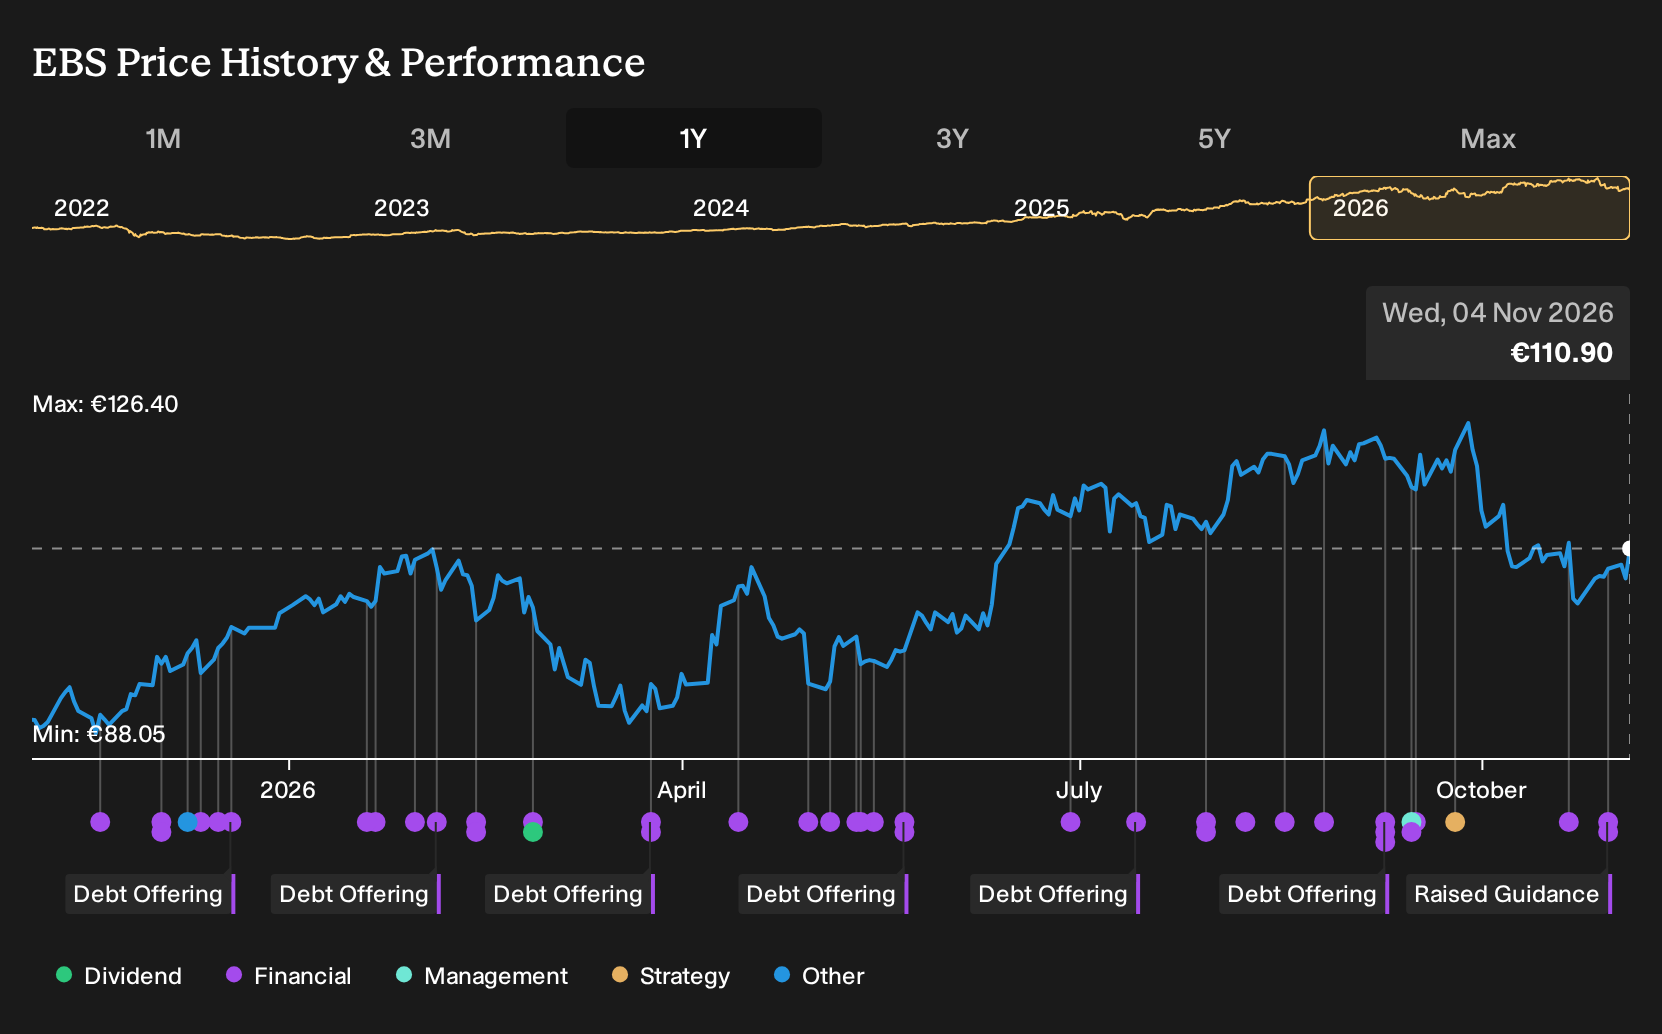
Missed Erste Group Bank's Run? What Holders Had To Believe
If Erste Group Bank sat on your watchlist instead of in your portfolio, the result may feel like a missed call. For Erste Group Bank shareholders, the return over the past year was 26.0%, including dividends. That outcome invites a question. What signal in late 2025, when bullish and cautious views split around Poland, digital banking and CEE convergence, could have helped you judge whether the ambitious revenue growth and margin assumptions were realistic before the story played out?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Erste Group Bank. Zero in on 194 high quality undervalued stocks for companies trading below our estimates.
The Two Erste Group Bank Stories Investors Were Weighing
The shares cost €89.7 at the start of the period, and investors in Erste Group Bank had to choose which story about its future felt more plausible.
The bullish camp saw a Fair Value of €97, built on revenue growth of 18.3% and profit margins at 25.6%. That view leaned heavily on Poland and CEE convergence as potential drivers of higher loan growth, along with digital banking as a possible way to cut the cost-to-income ratio.
The more cautious view pointed to a Fair Value of €82.63, with revenue growth of 11.1% and margins at 26.2%. This scenario focused on integration risk in Poland and the possibility that banking taxes across CEE would chip away at profitability.
What The Results Changed In The Erste Group Bank Debate
Erste Group Bank’s Q3 2026 update leaned toward the bullish script. Revenue moved from €2,783m in Q3 2025 to €3,903m and net income rose from €901m to €1,121m, which supported the more optimistic revenue and profit assumptions. Net margin slipped from 32.4% to 28.7%, so the profitability stretch in the bullish case stayed unproven. Overall, the evidence cut both ways.
The lesson travels. When a story depends on ambitious volume and earnings targets, focus on the trio that tested Erste Group Bank here: absolute revenue, profit, and net margin. Track these in each report to see which side of the original thesis the numbers are actually feeding.
What Erste Group Bank's Price Now Asks You To Believe
Erste Group Bank now trades at €111, with this selected Narrative’s Fair Value set below that level. The Narrative argues that taxes, integration costs and higher technology spending could eat into what today looks like strong profitability and digital traction.
A buyer at €111 is effectively assuming current earnings strength can translate into durable fee growth and capital generation. The question is how that assumption holds up against the Narrative’s concern that structurally higher banking taxes and specific country risks could absorb more of that profit stream.
"Although Erste Group Bank highlights strong operating profit and high returns on tangible equity, the steep increase in banking taxes and sector levies toward €372m in 2025 and continued elevated charges in 2026 in Austria, Hungary, Romania and Poland can structurally absorb a larger share of operating profit and limit how much of the revenue base ultimately flows through to net profit and capital generation."
The price and this Narrative do not agree. → Uncover what this Narrative says Erste Group Bank is actually worth
Another Banking Story Nearby
Erste Group Bank pushes you to think about what really drives a universal bank’s earnings power. One step away sits a different model.
Here, the focus is global banking, payments and capital markets under one roof. Management leans on size and breadth to chase share in payments, investment banking and wealth.
The same corporate clients funding growth plans, data centers and infrastructure need financing, advice and transaction services. That creates chances to earn both interest income and recurring fees.
Security, resiliency and cross border money movement sit at the center of this other story. If those needs keep expanding, this franchise’s role inside global finance could look very different.
That argument has a Narrative and a number behind it. → See the company one Narrative values 19% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com