


EN
How Strong Earnings Guidance At ING Groep (ENXTAM:INGA) Has Changed Its Investment Story
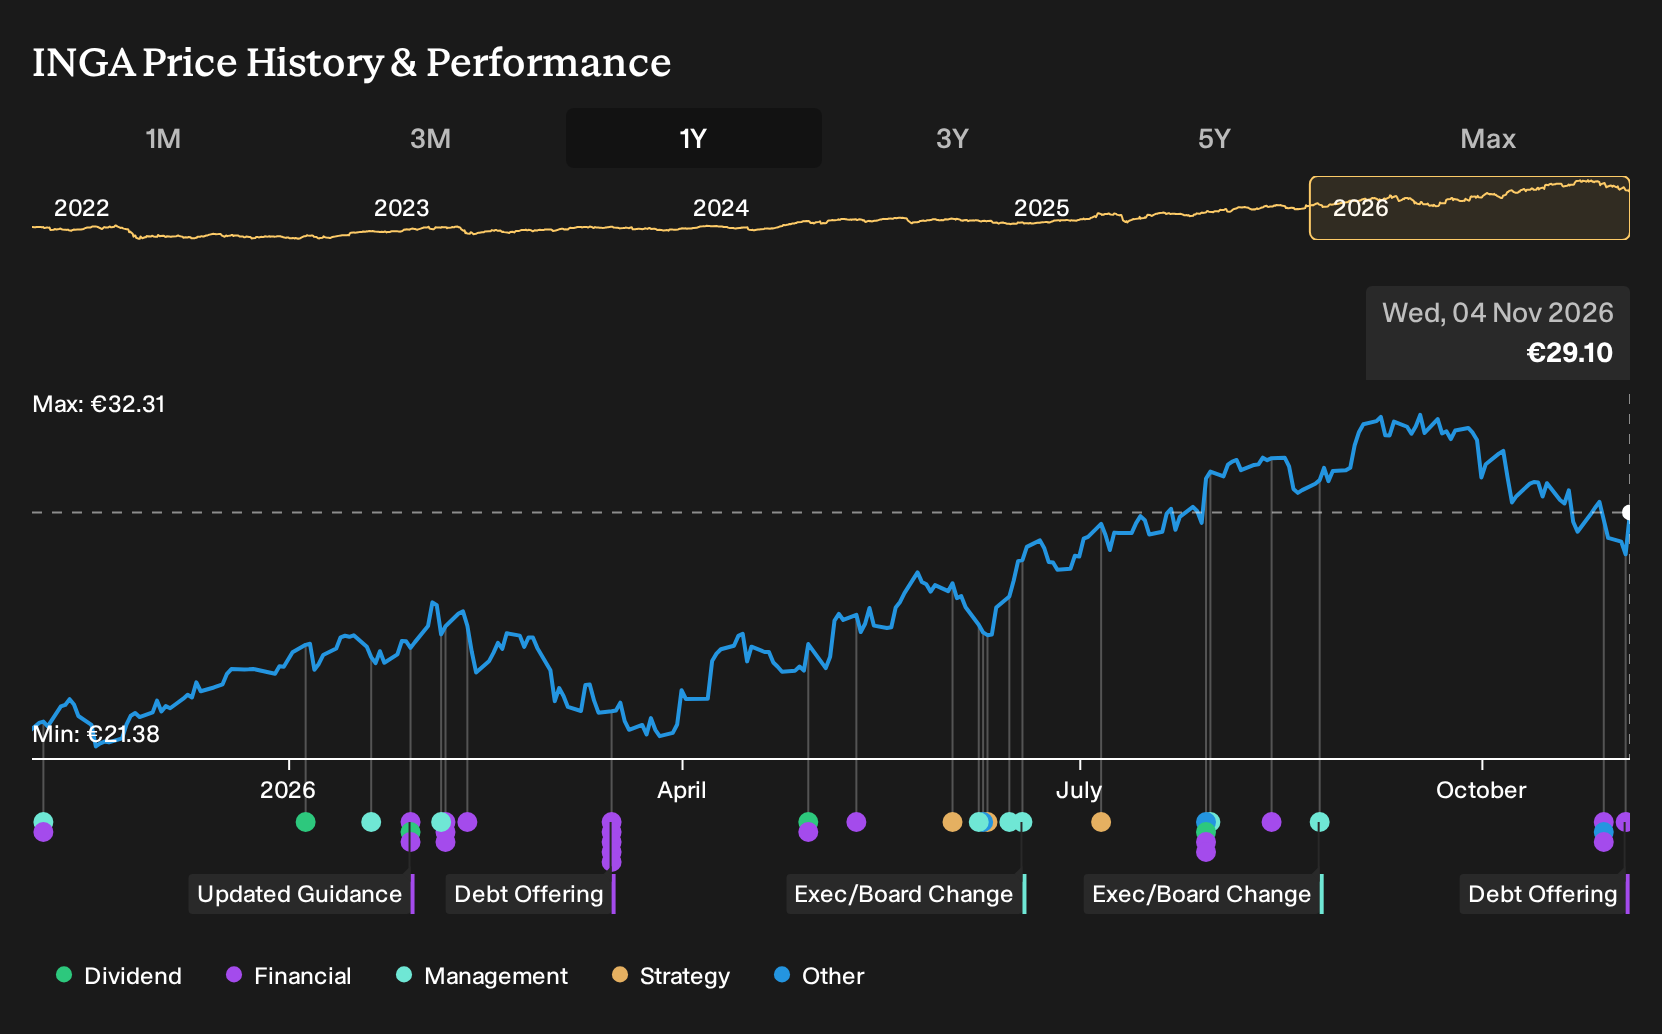
- ING Groep reported third quarter 2026 net interest income of €4,262 million and net income of €1,850 million. It later completed a £500 million senior unsecured fixed to floating Eurobond due November 2033, alongside ongoing execution of its €1.65b share buyback programme.
- Management now expects 2027 total income to exceed the original target by at least €1b. This points to a materially higher revenue ambition than previously communicated and sharpens focus on how ING Groep balances growth, funding and capital returns.
- We will examine how ING Groep's investment narrative is shaped by this stronger 2027 income guidance and recent funding and buyback activity.
Look beyond ING Groep and compare its latest guidance and buyback story with a curated 194 high quality undervalued stocks that may be positioning for its own rerating potential.
ING Groep Investment Narrative Recap
For ING Groep, the core belief as a shareholder is that a large, digitally oriented retail and wholesale bank can keep turning its scale into steady income while controlling funding and credit costs. The updated 2027 total income guidance, at least €1b above the prior goal, reinforces that management is leaning into this operating model rather than resetting expectations lower.
The most important short term catalyst is execution against that higher 2027 revenue ambition while maintaining returns and capital discipline. Key risks stay familiar. Wholesale loan demand could stay soft if corporate confidence remains weak. FX swings or a low bad loan allowance could also leave earnings more exposed if conditions turn.
The recent £500m senior unsecured fixed to floating Eurobond that ING Groep issued is the most relevant announcement to focus on here. It adds term funding at a time when the bank is signalling a bigger income ambition. It does so without using covered or subordinated structures that could complicate the capital stack.
For you, the link to catalysts is straightforward. The Eurobond supports balance sheet flexibility as ING reallocates risk weighted assets toward higher return retail and fee activities, while ongoing buybacks return capital. Execution risk sits in proving that this funding mix, plus the digital and AI enabled cost base, can support the upgraded income outlook without stretching risk or eroding earnings quality.
ING Groep's narrative projects €28.6 billion in revenue and €8.9 billion in earnings by 2029. This assumes 4.3% yearly revenue growth and an earnings increase of about €0.2 billion from €8.7 billion today.
Uncover why ING Groep's fair value indicates an 18% potential upside to its current price, a discount that could close faster than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts focus on ING Groep’s AI rollout as the real swing factor. Before this bond deal and raised 2027 income guidance, the bullish group was already modelling about €30.8b of revenue and €10.4b of earnings by 2029. You can see how this new information could push those views even further or bring them closer to consensus.
Explore 3 other ING Groep fair value estimates, including one that suggests up to 118% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ING Groep research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ING Groep. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ING Groep's overall financial health at a glance.
Looking for more investment ideas beyond ING Groep?
Once you have formed a view on ING Groep, it can be useful to line that opinion up against other opportunities that share some of the qualities you like, whether that is value, income, or balance sheet strength. The Simply Wall St Screener lets you filter for those traits directly so you can build a watchlist that fits how you prefer to invest.
- If you want potential mispricing combined with solid fundamentals, consider scanning a curated 194 high quality undervalued stocks that match strict quality and valuation filters.
- If resilience matters more to you than excitement, focus on stability with a 217 resilient stocks with low risk scores that have relatively lower risk scores based on financial and volatility metrics.
- If balance sheet strength is your first hurdle, start with a list of solid balance sheet and fundamentals (195 results) and then layer on your own criteria for return potential and income.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com