


EN
ConocoPhillips (COP) Posts Strong Q3 Results, Is The Pullback A Buying Opportunity?
Fresh third quarter results are now in for ConocoPhillips (COP), with the oil producer reporting US$20.06b in revenue and US$4.00b in net income for the period ended September 30, 2026.
ConocoPhillips shares pulled back sharply after the earnings release, with a 1-day share price return of down 5.17% and a 7-day move of down 8.13%. However, momentum over longer periods remains positive, with a 30-day share price return of 6.65%, a 90-day gain of 17.28%, and a year-to-date share price return of 41.61%, alongside a 1-year total shareholder return of 61.07% that reflects both price gains and distributions.
Scan how ConocoPhillips stacks up against other energy producers and spot potential next candidates for your watchlist with a curated set of 35 high quality undervalued stocks.After a sharp pullback on strong third quarter numbers and a big run over the past year, ConocoPhillips now forces a choice. Does buying after this drop still compare well with waiting for a deeper reset on valuation?
Most Popular Narrative: 8% Undervalued
ConocoPhillips last closed at $136.94, while the most followed valuation narrative pegs fair value closer to $149.04, creating a clear gap that hinges on how well long life oil and LNG projects deliver.
The company’s outlined path to a $7b free cash flow uplift by 2029, helped by lower free cash flow breakevens from the mid US$40s WTI range today to the low US$30s, indicates a scenario in which margin expansion and higher earnings power may not yet be fully reflected in recent results. Progress on long life conventional and international projects, including the Willow development at roughly 50% completion and the planned Iraq Kirkuk stake with around 3b barrels of initial gross recoverable resources at an expected US$30 per barrel cost of supply, is expected to add durable production and support structurally higher net margins.
See why 107 investors see ConocoPhillips as 8% undervalued.
Result: Fair Value of $149.04 (UNDERVALUED)
Still, the ConocoPhillips narrative can break if big ticket projects like Willow or Port Arthur LNG hit timing setbacks or if higher capital needs squeeze free cash flow.
Find out about the key risks to this ConocoPhillips narrative.
Another View: Market Multiple Says ConocoPhillips Is Pricey
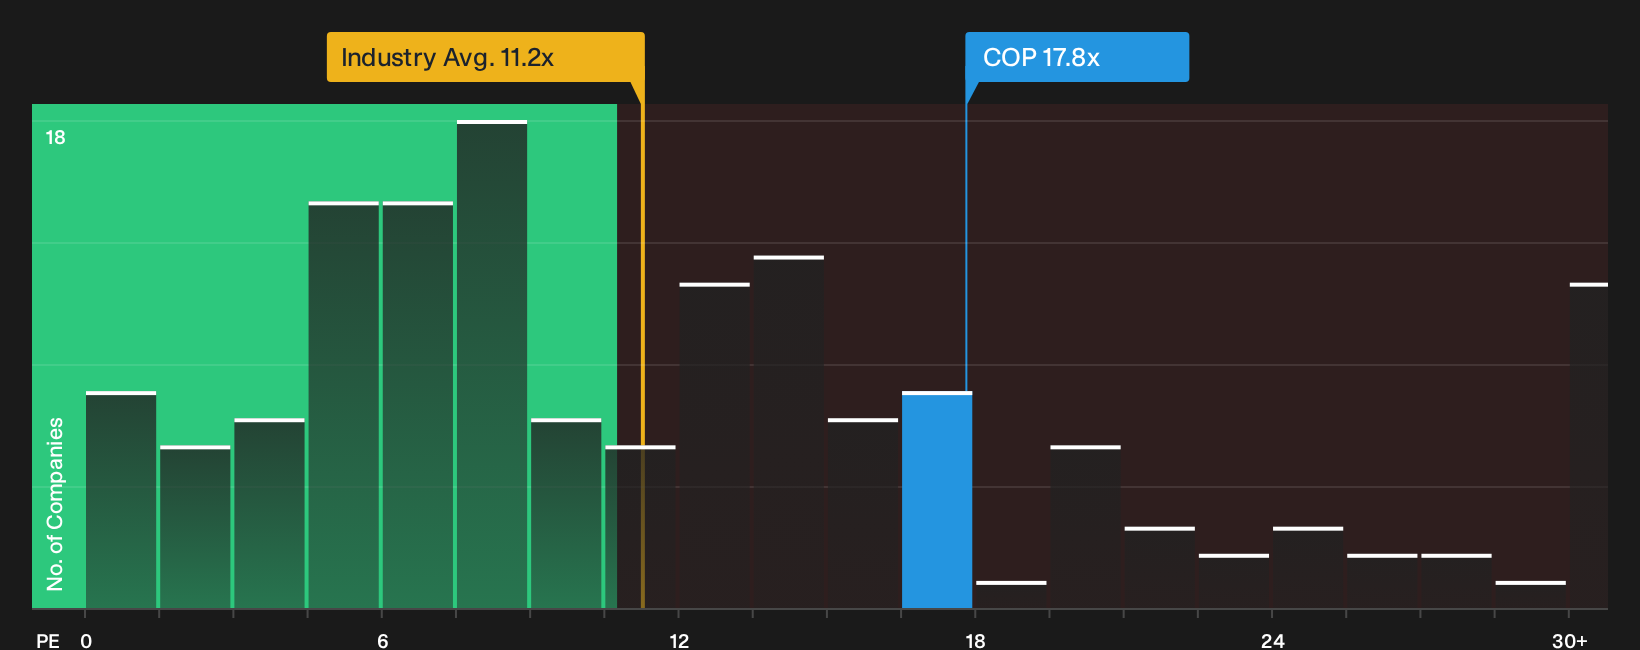
The SWS DCF model points to ConocoPhillips trading well below an estimated future cash flow value of $325.51 per share, which flags a deep undervaluation story. Yet the current 17.8x P/E is richer than the US Oil and Gas industry on 11.2x and above the 15.2x peer average. If the market leans back toward those lower ratios, how comfortable are you with that compression risk?
See what the numbers say about this price in our valuation breakdown, then decide which lens you trust more for ConocoPhillips, the cash flow model or the earnings multiple, before making any moves. See what the numbers say about this price — find out in our valuation breakdown.
For a clearer picture of how ConocoPhillips trades against its sector on earnings, review the latest relative valuation chart before updating your own expectations.
Next Steps
Mixed signals on ConocoPhillips so far. Use this as a starting point, move quickly with your own research, and weigh both the 1 key reward and 2 important warning signs in the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond ConocoPhillips?
If ConocoPhillips has you thinking about portfolio upgrades, do not stop here. Broader opportunity sits with other stocks that share strong fundamentals and compelling setups.
- Target stability with companies that prioritise balance sheet strength and resilient cash profiles through the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities where quality and valuation line up by scanning the 35 high quality undervalued stocks.
- Put income potential on your radar by tracking companies screened as 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com