


EN
How Investors Are Reacting To MasTec (MTZ) Record Backlog Growth
- MasTec reported third quarter 2026 sales of US$5,152.34m and net income of US$150.57m, issued full year 2026 guidance, and highlighted strong Power Delivery demand with a record backlog.
- The mix of record Power Delivery work alongside restructuring in Pipeline Infrastructure and Communications gives investors a clearer picture of how MasTec is balancing growth opportunities with execution pressure across its portfolio.
- We will now look at how MasTec's record Power Delivery backlog could reshape the investment narrative built around its infrastructure cycle.
Scan how MasTec's infrastructure story compares with other contractors by running the same playbook across our curated 41 power grid technology and infrastructure stocks
MasTec Investment Narrative Recap
To own MasTec, you need to believe that record Power Delivery and clean energy work can offset the pressure in Pipeline Infrastructure and Communications. The latest quarter showed higher sales but lower quarterly net income. The near term catalyst is clear execution on this bigger backlog while holding project margins close to management’s targets.
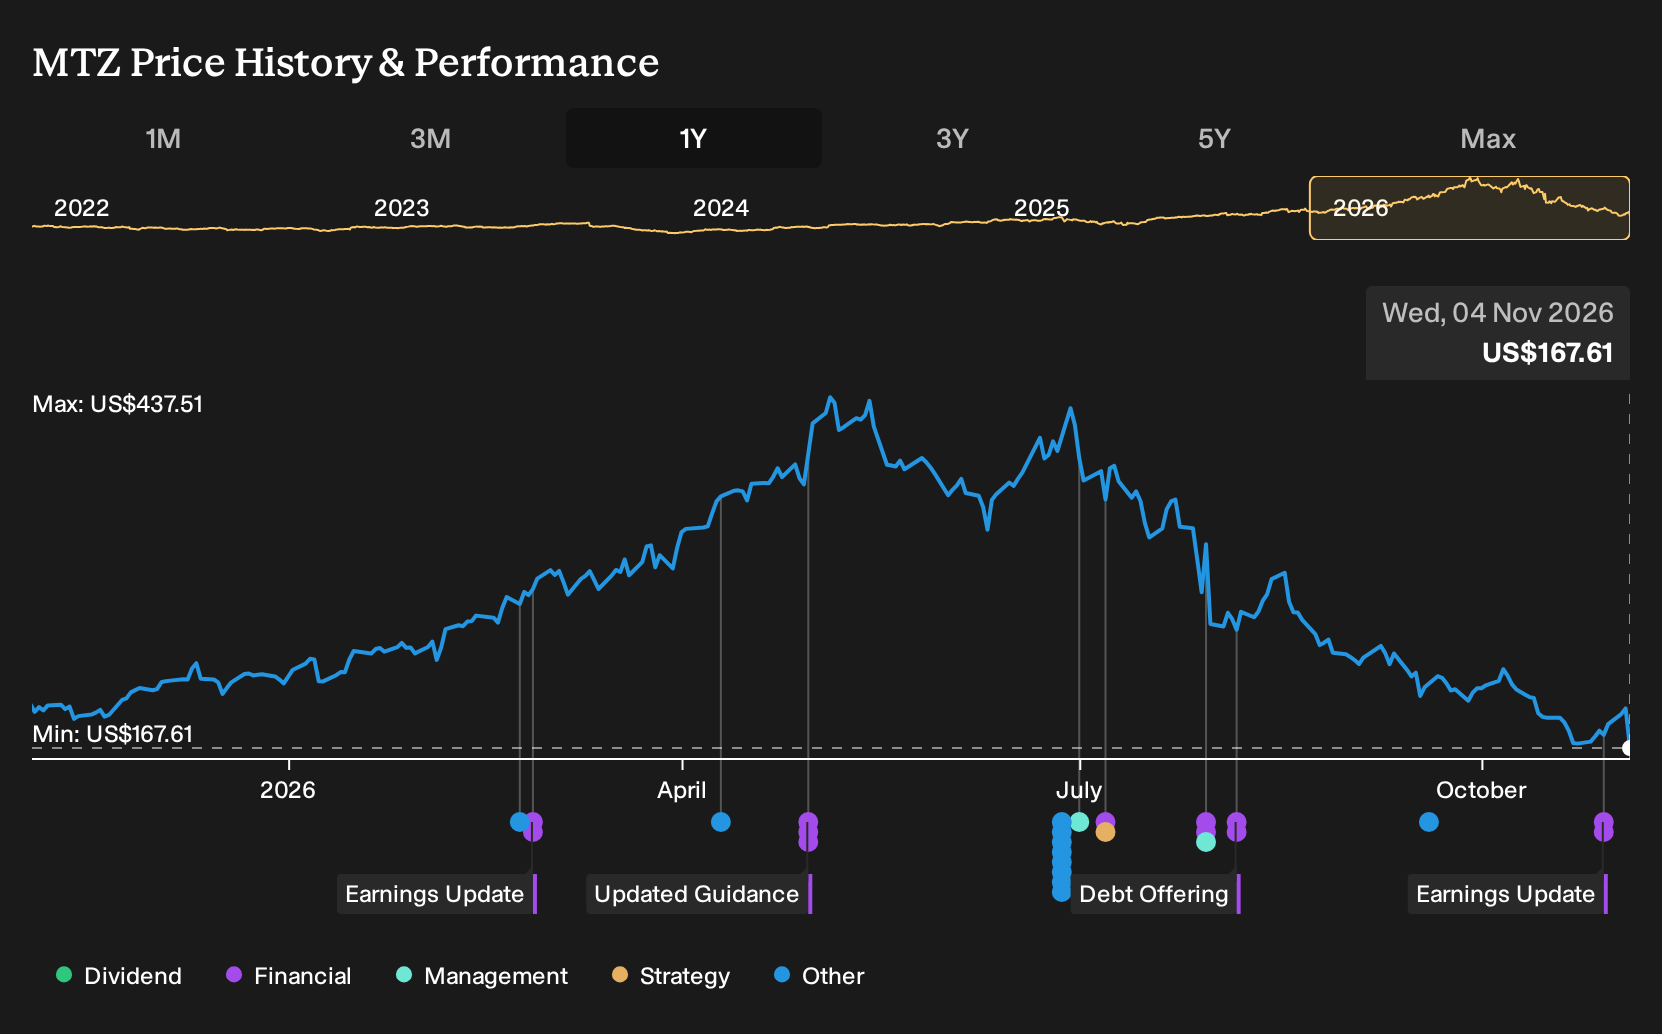
The biggest risk right now remains earnings delivery. Communications has a trimmed outlook and any further softness or execution slip could matter because the stock has reacted sharply to past guidance misses. If Power Delivery work converts smoothly, recent earnings volatility may look more like timing than a structural issue.
The new full year 2026 outlook gives you a useful anchor. MasTec now expects US$18.3b of revenue, GAAP net income of US$498m to US$524m and GAAP diluted EPS of US$5.69 to US$6.01. Those numbers frame what has to be delivered as Power Delivery ramps and Communications restructures.
For catalysts, that guidance range effectively becomes the scoreboard. Strong Power Delivery conversion and any early signs of margin progress in Communications or Pipeline would help support confidence in those EPS targets. On the flip side, given how the stock has reacted to past misses, even a modest shortfall versus this new bar remains a key risk.
MasTec's narrative projects US$26.2b revenue and US$1.2b earnings by 2029. This implies 17.7% yearly revenue growth and an earnings increase of roughly US$705.7m from current earnings of US$494.3m.
Uncover how MasTec's fair value indicates a 115% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Some of the most optimistic analysts frame MasTec’s Power Delivery strength as part of a bigger acquisition story. Before this earnings release, that group was penciling in about US$28.6b of revenue and US$1.6b of earnings by 2029. As a result, you are comparing this quarter’s mixed EPS print against forecasts that were already far more ambitious than consensus and may now need a rethink.
Explore 4 other MasTec fair value estimates, including one that suggests potential upside of up to 196% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MasTec research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for MasTec. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MasTec's overall financial health at a glance.
Looking For More Investment Ideas Beyond MasTec?
Once you have a view on MasTec, it can help to compare its story with other opportunities that share some of the qualities you care about most.
- If you want potential mispricings backed by fundamentals, start with our carefully filtered list of 35 high quality undervalued stocks that pair quality with pricing support.
- If resilience and balance sheet strength matter most to you, narrow the field using the list of solid balance sheet and fundamentals (24 results) for companies with financial cushions that can help them handle tougher periods.
- If you are hunting for lesser known opportunities with solid foundations, scan the 19 high quality undiscovered gems and see which profiles align with your own risk and return preferences.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com