


EN
A $650 Million Reason Why Kraft Heinz Stock Is Up
Kraft Heinz (KHC) stock moved higher on Nov. 4 after the packaged-food giant announced a $650 million deal to divest its North American coffee business. The transaction will see private-equity giant One Rock Capital Partners acquire brands, including Maxwell House and Gevalia, at an enterprise valuation of $650 million.
KHC expects to receive about $500 million in after-tax cash proceeds while retaining a 30% non-controlling stake in the business. Kraft Heinz shares are now up about 20% versus their year-to-date low.
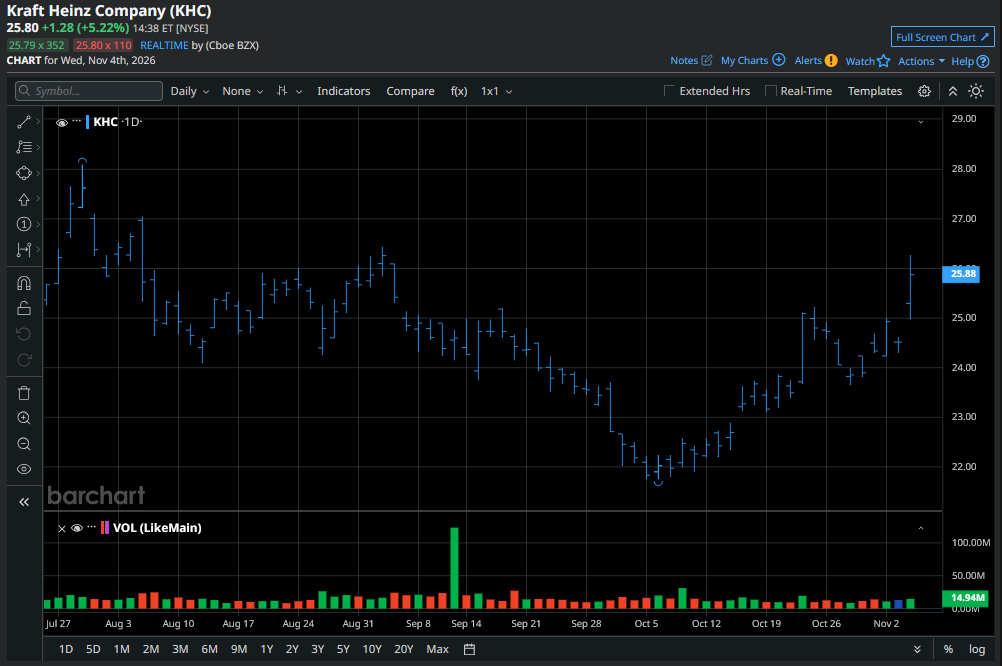
Why Is the Coffee Divestiture Bullish for KHC Shares?
Investors cheered KHC stock, believing the coffee divestiture is a strategic win for the NYSE-listed giant. Instead of holding onto a slower-growth business, management is monetizing a non-core asset and redirecting resources toward brands and categories where it sees opportunity for stronger long-term growth.
Kraft Heinz plans on using the deal proceeds to reduce debt and strengthen its balance sheet. The asset sale aligns with CEO Steve Cahillane’s broader transformation strategy as well.
Since taking the helm earlier this year, he has emphasized investment in core brands, operational improvements, and portfolio optimization.
The announcement is bullish for KHC because it’s retaining a 30% equity stake in the coffee unit, preserving exposure to any future upside while immediately unlocking capital.
Is Kraft Heinz Stock Attractive for the Long Term?
Also on Wednesday, Kraft Heinz reported a market-beating Q3 and raised its guidance for the full year. Management now sees organic net sales declining to between 0.4% and 1.25% — a major improvement from a steeper decline it had guided for earlier.
Together, the divestiture and raised 2026 sales outlook suggest management is making measurable progress in its turnaround effort, which makes KHC attractive for long-term investors.
Improving market-share trends, substantial cash generation, and a lucrative dividend yield of more than 6% make up additional reasons to have Kraft Heinz shares in your investment portfolio.
Barchart also currently has a “24% BUY” average opinion on KHC, indicating technical momentum is turning in its favor as well.
What Analysts Expect From Kraft Heinz Moving Forward
On the flip side, Wall Street analysts recommend caution in playing KHC shares at current levels.
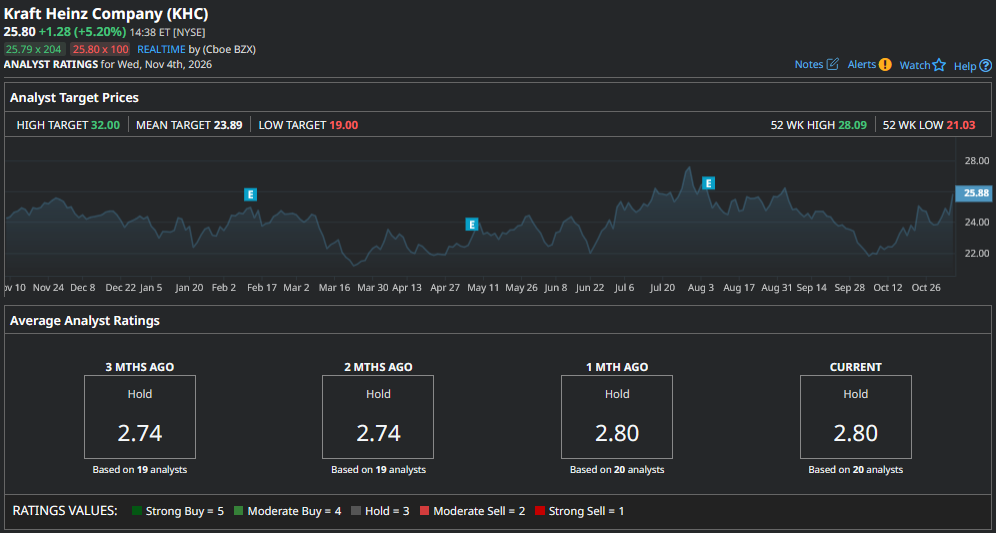
The consensus rating on Kraft Heinz sits at “Hold,” with the mean price objective of nearly $24 indicating potential for a decline over the next 12 months.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.