


EN
Earnings Beat Has Investors Revisiting Agnico Eagle Mines Stock
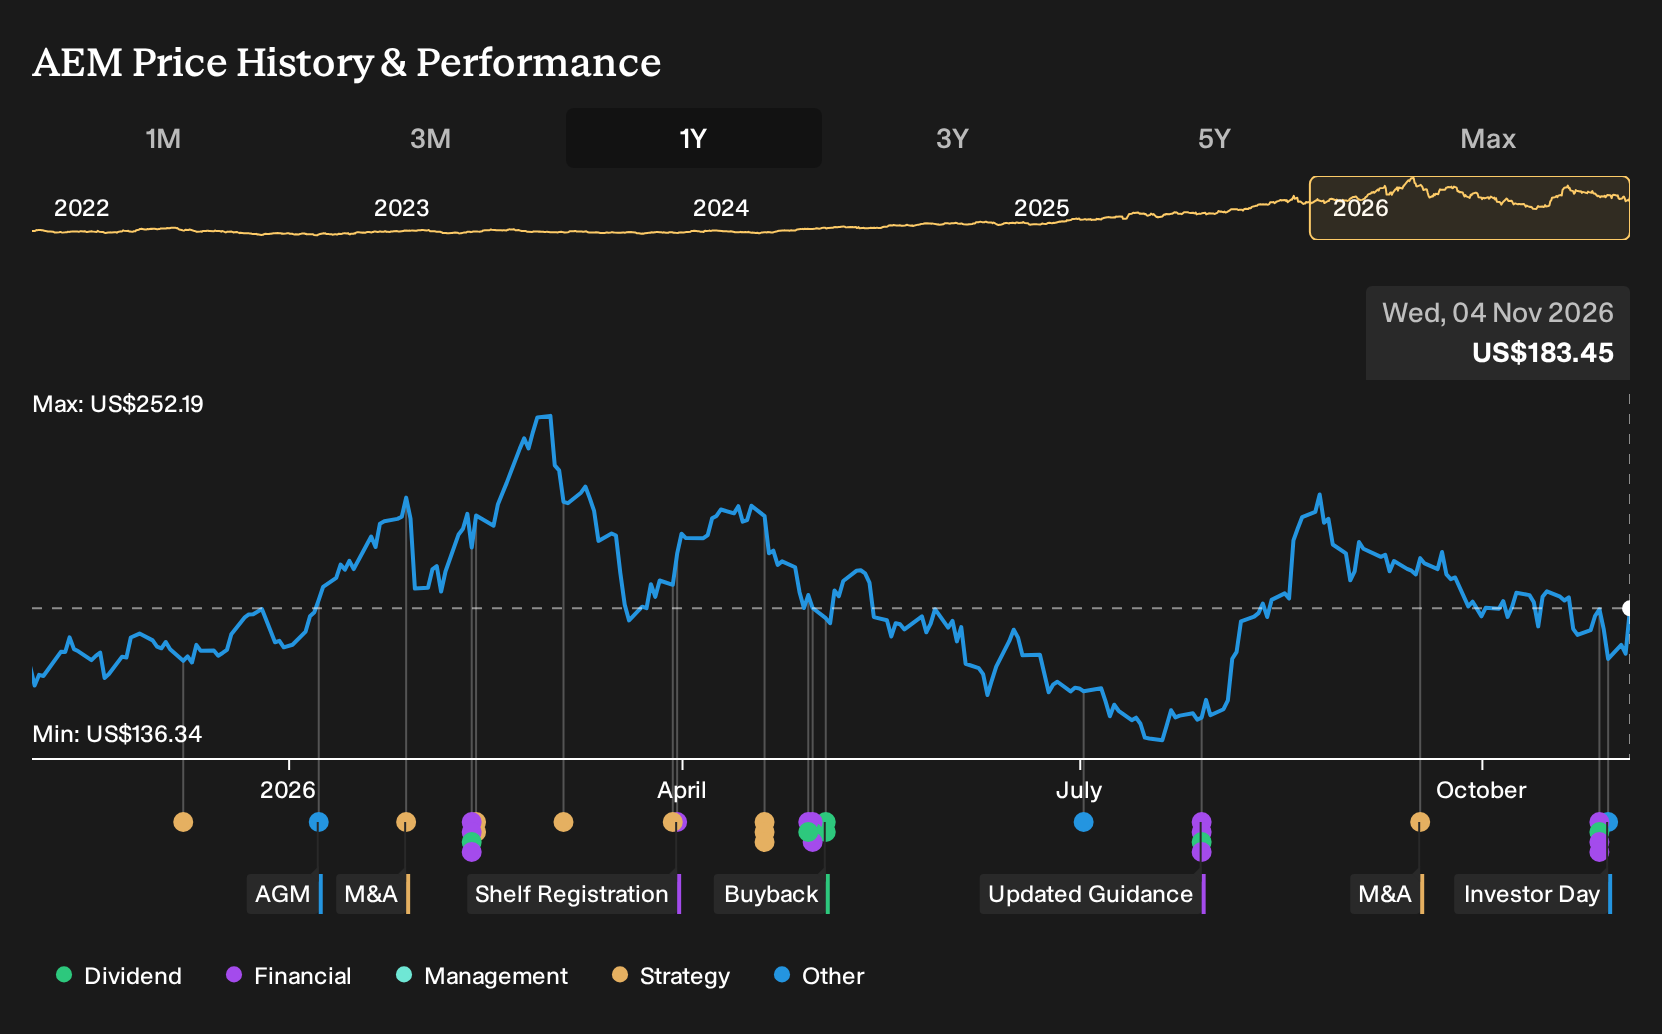
- Agnico Eagle Mines reported third quarter 2026 net income of US$1,352.87m and basic EPS of US$2.67 from continuing operations, alongside a US$0.45 quarterly dividend and updated 2026 gold production guidance of 3.3m to 3.5m ounces.
- Even with lower reported gold volumes for the quarter and year to date, higher gold prices and stronger earnings highlight how pricing power, cost control and capital returns are shaping Agnico Eagle Mines' operating story.
- The focus now shifts to how Agnico Eagle Mines' strong earnings in the context of firm gold prices may influence the longer term investment narrative.
Compare Agnico Eagle Mines' earnings momentum and capital returns with hand picked peers by scanning the 34 elite gold producer stocks, which is shaping the next phase of the precious metals trade.
Agnico Eagle Mines Investment Narrative Recap
To own Agnico Eagle Mines, you need to believe the business can keep turning a large, diversified mine portfolio into strong free cash flow even when individual sites hit problems. The latest quarter supports that idea. Net income of US$1,352.87m and basic EPS of US$2.67 came alongside lower reported gold volumes.
The near term swing factor is whether operations stay smooth while Barnat related volume losses are absorbed and major projects continue without fresh disruptions. The biggest risk still sits with site specific issues and safety, where past fatalities and the permanent loss of Barnat ounces show how fast output and reserves can be hit.
The dividend update is probably the clearest signal for you right now. Agnico Eagle Mines declared a quarterly cash payout of US$0.45 per share, with a record date of December 1, 2026 and payment on December 15. Management has kept some form of dividend in place every year since 1983.
That sort of track record matters if you are weighing today’s strong earnings against future project and safety risks. A recurring payout, together with the existing buyback and current free cash flow profile, puts more focus on the company’s ability to keep operations stable enough to fund both growth projects and ongoing capital returns.
Agnico Eagle Mines' narrative projects US$15.3b revenue and US$5.9b earnings by 2029. This is based on analysts assuming 1.7% yearly revenue growth and earnings staying flat at US$5.9b compared with current earnings of US$5.9b.
Uncover why Agnico Eagle Mines' fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Agnico Eagle Mines’ production growth pipeline rather than today’s free cash flow. Before this earnings release, they were pencilling in revenue of about US$17.3b and earnings of roughly US$5.7b by 2029. That is a far more upbeat story than consensus. Use this quarter’s strong results and dividend affirmation as a prompt to compare those upbeat expectations with more cautious views. Then decide which camp feels closer to your own read of the risks.
Explore 5 other Agnico Eagle Mines fair value estimates, including one that suggests as much as 67446% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Agnico Eagle Mines research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Agnico Eagle Mines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Agnico Eagle Mines' overall financial health at a glance.
Looking for more Agnico Eagle Mines sized investment ideas?
If Agnico Eagle Mines has sharpened your focus on quality and resilience, you can use that same filter across the market with a few targeted screens that surface different angles on potential opportunities.
- For investors who want income to feel more predictable, start with a shortlist of companies that have paid out at least a 5% yield, then review which ones look like genuine 5 dividend fortresses.
- If capital preservation comes first and return comes second, focus on businesses that combine sturdy finances with muted risk scores by using a 31 resilient stocks with low risk scores to narrow the field.
- When you want to go beyond the usual tickers and search for quality that the crowd might be overlooking, let the screener surface 19 high quality undiscovered gems that still show strong fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com