


EN
Are Wall Street Analysts Bullish on Philip Morris International Stock?
With a market cap of $329.3 billion, Philip Morris International Inc. (PM) is a leading global consumer goods company transforming its business toward a smoke-free future, with a portfolio spanning cigarettes, heat-not-burn products, nicotine pouches and e-vapor products, available in 110 markets and used by more than 43 million legal-age consumers worldwide.
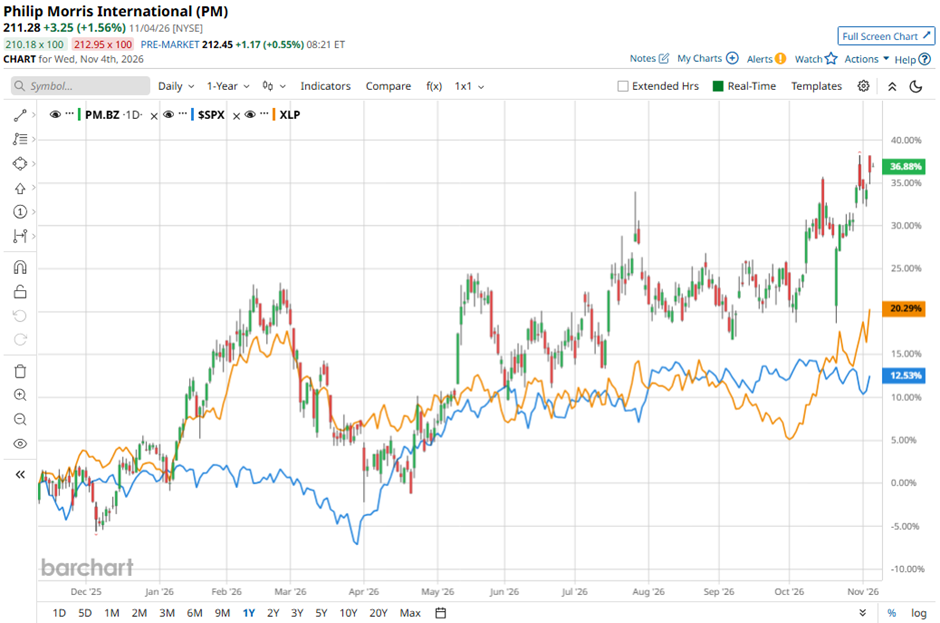
Shares of the Stamford, Connecticut-based company have outperformed the broader market over the past 52 weeks. PM stock has increased 43.1% over this time frame, while the broader S&P 500 Index ($SPX) has gained 13.5%. Moreover, shares of the company are up 31.7% on a YTD basis, compared to SPX’s 12.3% increase.
Narrowing the focus, the tobacco giant stock has outpaced the State Street Consumer Staples Select Sector SPDR ETF’s (XLP) nearly 21% rise over the past 52 weeks.
Philip Morris International shares fell 1.2% on Oct. 21 as unadjusted EPS declined 5% due to a non-cash adjustment related to equity investments, even though Q3 2026 adjusted EPS rose 5.4% to $2.36, beating estimates. The company warned that the Middle East conflict and energy-driven inflation would have a greater impact in Q4 as higher input costs take effect, and the ongoing Ukraine conflict continued to disrupt its supply chain and logistics.
Additional concerns included a decline in organic U.S. sales and plans for higher investment in its ZYN nicotine-pouch business, despite combined sales increasing 5.4% (7.1% organically) and smoke-free products accounting for more than 40% of total sales.
For the fiscal year ending in December 2026, analysts expect Philip Morris International’s adjusted EPS to grow 10.3% year-over-year to $8.32. The company’s earnings surprise history is promising. It beat the consensus estimates in each of the last four quarters.
Among the 14 analysts covering the stock, the consensus rating is a “Moderate Buy.” That’s based on eight “Strong Buy” ratings, two “Moderate Buys,” and four “Holds.”
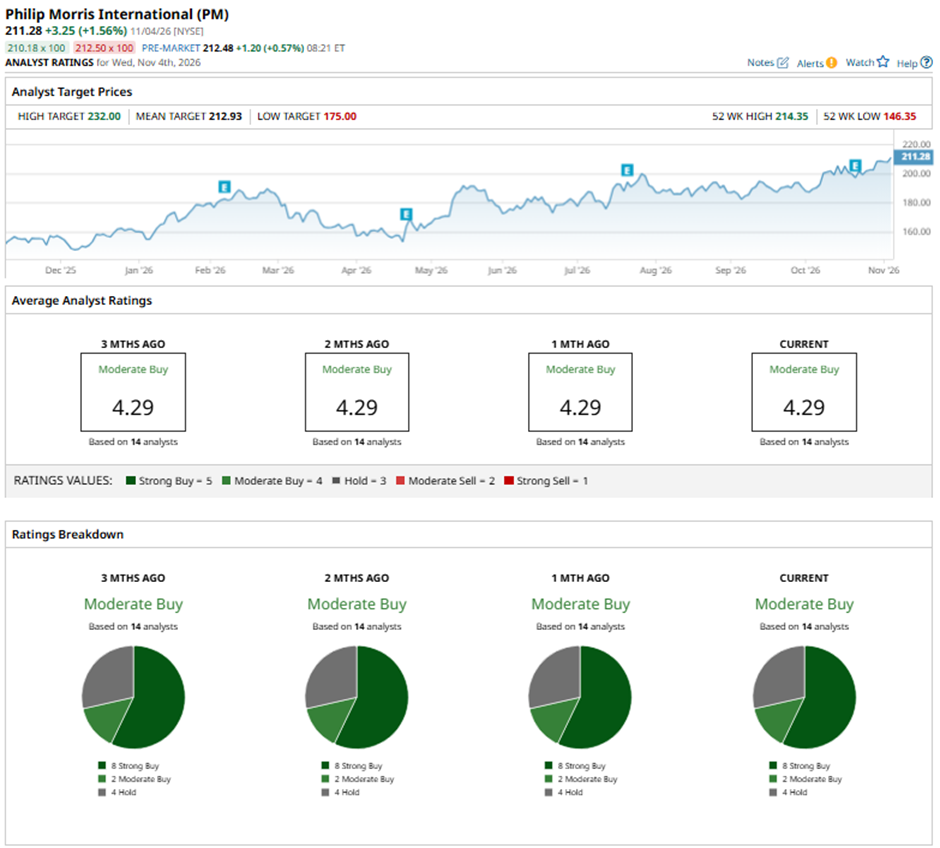
This configuration has remained unchanged over the past three months.
On Oct. 26, Argus raised its price target on Philip Morris International to $220 and maintained a “Buy” rating.
The mean price target of $212.93 represents a marginal premium to PM’s current price levels. The Street-high price target of $232 suggests a 9.8% potential upside.
On the date of publication, Sohini Mondal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.