


EN
Comfort Systems USA (FIX) Stock Still Looks Cheap Following Its Huge 5 Year Run
Comfort Systems USA has delivered a very large 5 year gain for shareholders, even after a sharp pullback in recent weeks. With that kind of long run-up now meeting a steeper short term slide, the key issue is whether the current valuation is still grounded in the construction services group's earnings power.
- Over the past 5 years the stock has returned about 10x, which puts real pressure on the question of how much of Comfort Systems USA's earnings strength is already reflected in the price.
- Recent reporting pointed to faster revenue and earnings per share growth along with more cash than debt, which can support arguments that investors are paying for a business with reinforced profitability and balance sheet resilience.
- The analysts covering Comfort Systems USA have run their own numbers. See what analysts think Comfort Systems USA's shares could be worth.
The issue now is whether the earnings that Comfort Systems USA generates today are enough to justify where the stock trades after that kind of multi year climb and recent drop.
If you are weighing whether Comfort Systems USA still justifies its recent run based on earnings, it can help to compare it with a broader group of 35 high quality undervalued stocks.
Is Comfort Systems USA Still Cheap on Earnings?
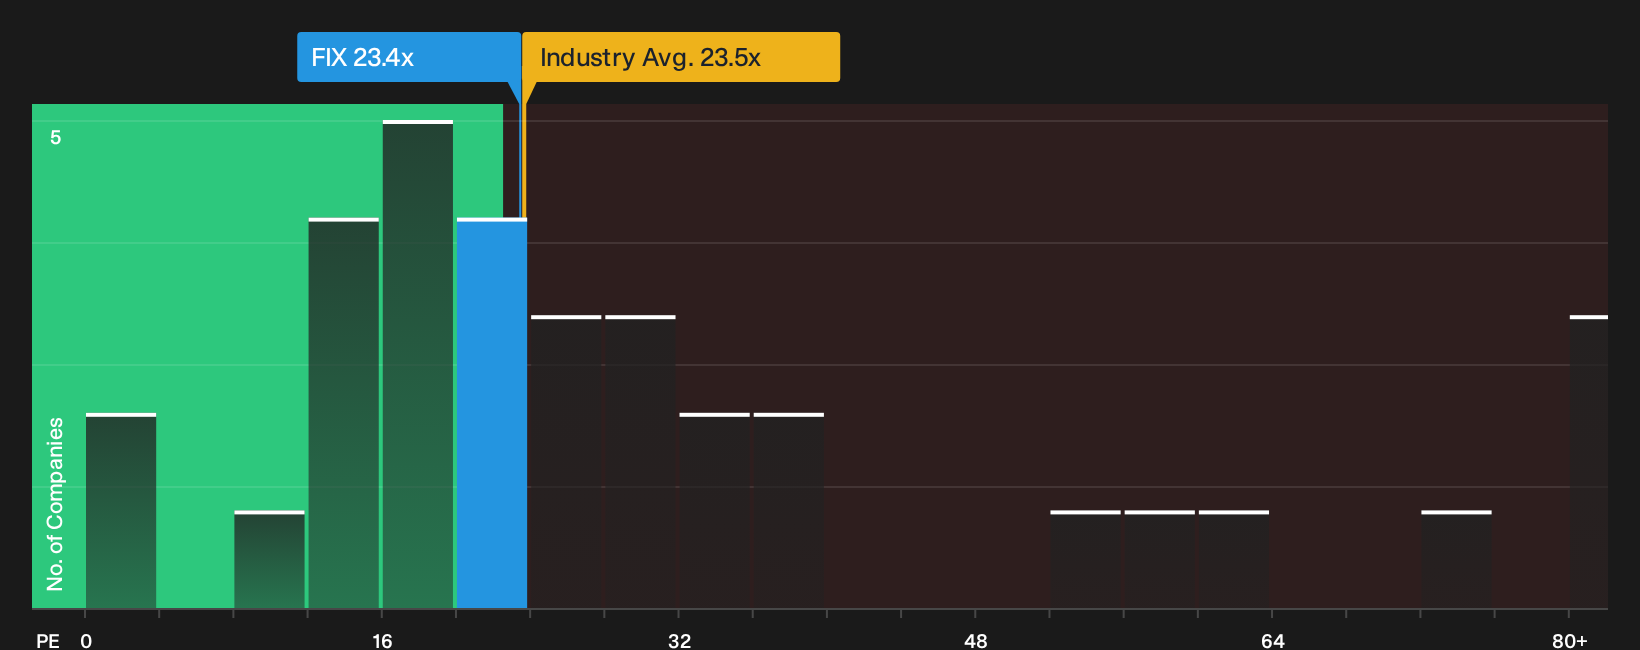
The P/E ratio fits Comfort Systems USA quite well because this is an earnings driven contractor rather than a story purely about assets or revenue scale. The stock currently trades on about 23.4x earnings, which is slightly below the broader construction industry average of roughly 23.5x and under the peer group around 28.3x. Based on a tailored fair multiple that takes its profitability profile, sector, size and risk into account, that level screens as undervalued rather than stretched.
Because revenue and earnings per share were recently reported higher year on year, the valuation gap suggests investors are not paying the kind of premium that peers command for similar profit streams. Despite that recent quarter and a balance sheet carrying more cash than debt, the P/E still comes in below the peer pack. That leaves room for readers to argue the stock is priced cautiously relative to its earnings base. Explore the numbers behind Comfort Systems USA's P/E valuation.
The Comfort Systems USA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Comfort Systems USA valuation question leaves off and explain what kind of future path for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price. Each scenario links a fair value to a clear storyline about Comfort Systems USA's potential catalysts and key risks, so you can track which version of events appears closer to reality over time on the Community page.
One of the top community narratives on Comfort Systems USA: 48% undervalued
"Record backlog of US$14.1b, up strongly year over year and sequentially, points to continued conversion of contracted work into future revenue and earnings…"
Discover why this Narrative puts Comfort Systems USA at 48% undervalued.
One More Piece To Check Before Acting On Comfort Systems USA's Valuation
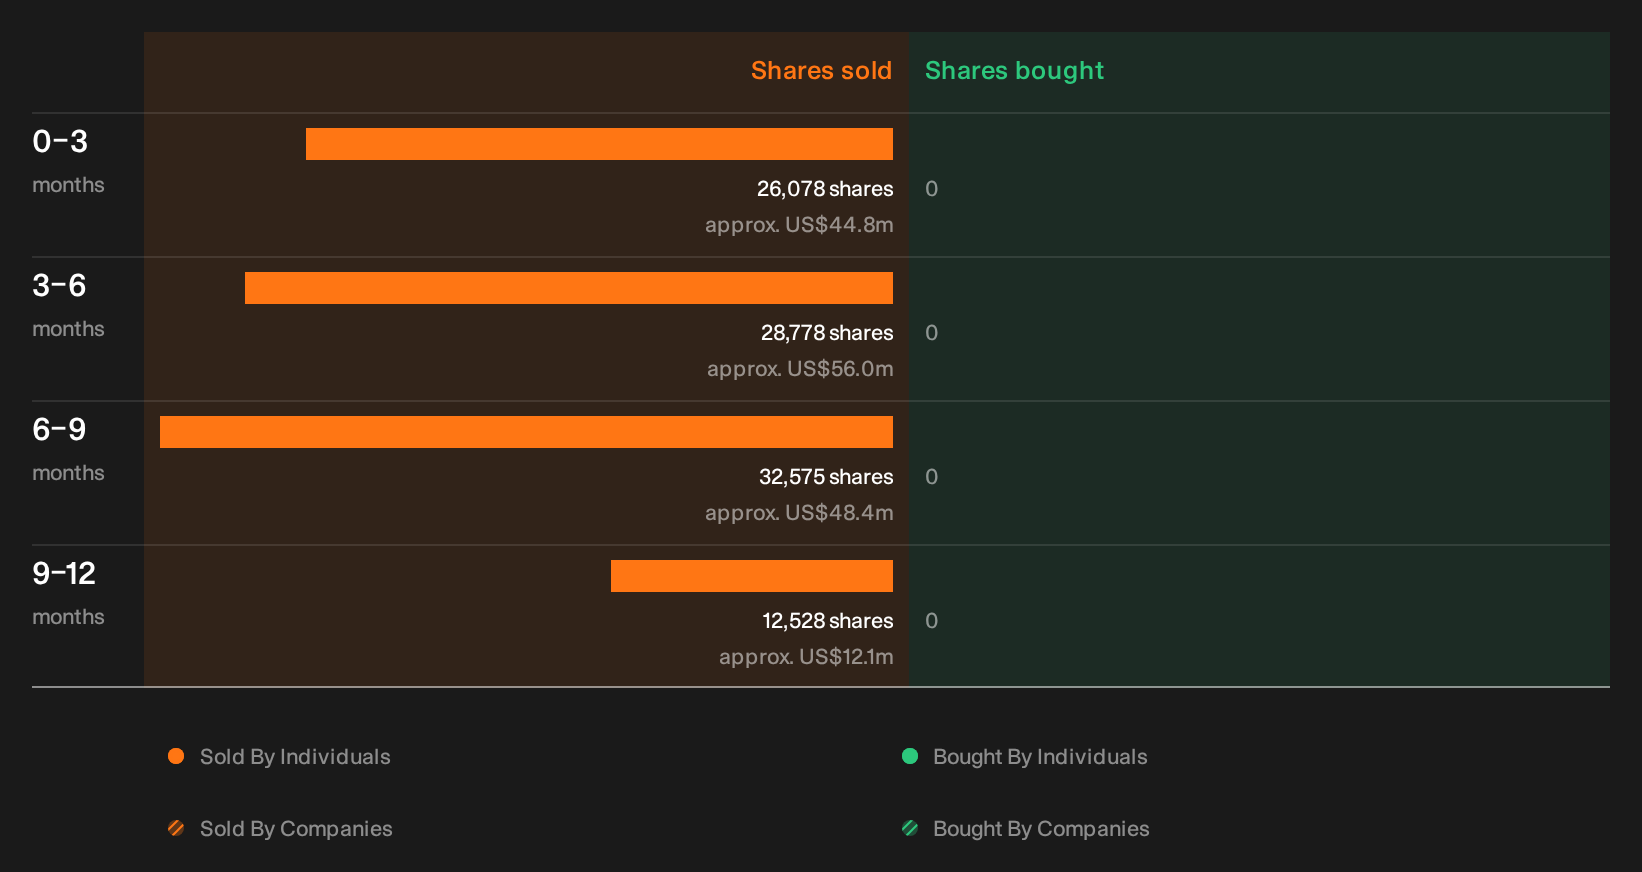
Before leaning too hard on the numbers, it is worth seeing which insiders have recently been selling, how much stock has changed hands and what that might signal for you as a shareholder. See the recent insider selling flagged for Comfort Systems USA.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com