


EN
Should Return To Profit Require Action From Ryerson Holding (RYI) Investors?
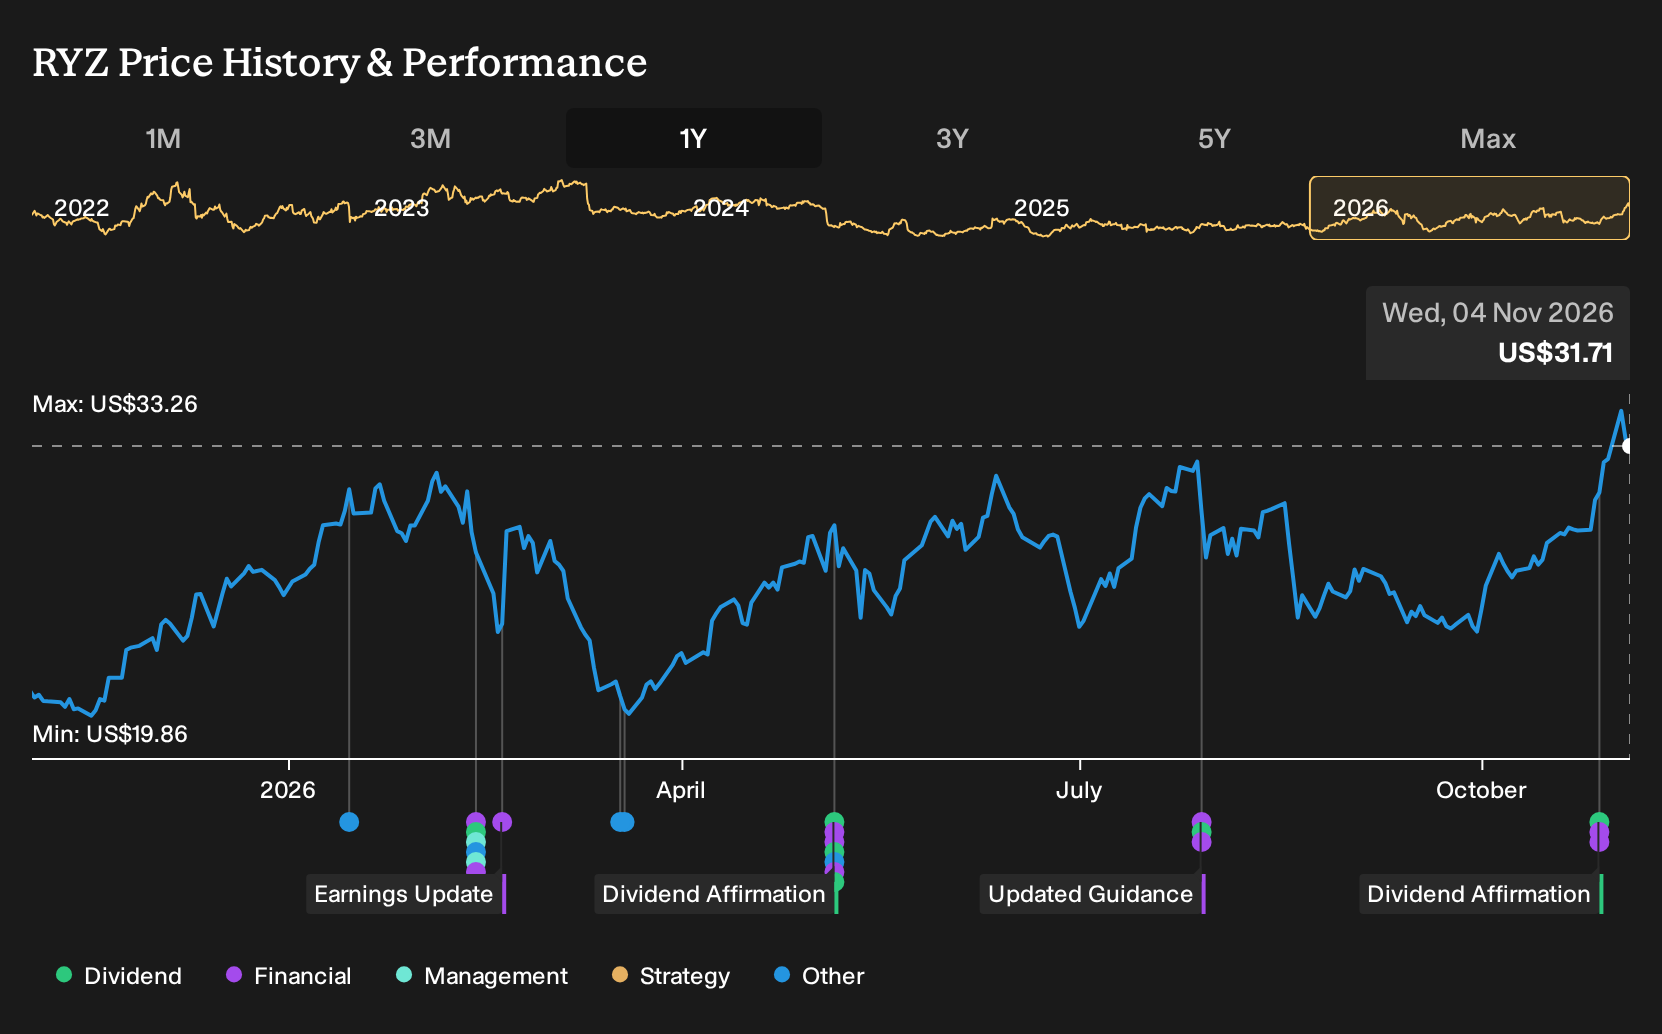
- Ryerson Holding reported third quarter 2026 results with sales of US$2,177.8 million and net income of US$32 million, issued fourth quarter guidance, affirmed a quarterly dividend of US$0.1875 per share, and completed a US$3.81 million share repurchase tranche.
- The swing from a third quarter 2025 net loss to earnings, paired with specific fourth quarter profit guidance per diluted share, gives investors fresh data on how Ryerson Holding is managing demand, pricing, and capital returns in parallel.
- We will look at how Ryerson Holding's investment narrative is shaped by the return to profitability and detailed fourth quarter guidance.
What Is Ryerson Holding's Investment Narrative?
For Ryerson Holding, the investment pitch hinges on a simple question: Do you believe the metals processor can turn its recent return to profitability into something steady while handling a capital heavy business and a volatile pricing backdrop? Third quarter earnings in the black, plus fourth quarter guidance that points to continued net income and EPS, show management aiming for consistency rather than a one off quarter.
The confirmed US$0.1875 dividend and the completed US$3.81 million buyback tranche underline a commitment to capital returns. However, they sit beside flagged issues such as dividend coverage, interest costs and prior dilution. In the short term, the key catalyst is whether fourth quarter guidance is met while demand and pricing for industrial metals stay supportive enough to service debt and fund processing operations without overreliance on external borrowing.
Even so, there is a pressure point in Ryerson Holding's setup that could quickly change how that story feels if ...
There's only one way to know the right time to buy, sell or hold Ryerson Holding. Head to Simply Wall St's company report for the latest analysis of Ryerson Holding's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community only includes two fair value opinions for Ryerson Holding, with estimates stretching from US$33 to about US$150 per share. That gap shows how far views can spread when investors focus on different earnings paths. With new guidance and a confirmed dividend now on the table, you can revisit those older community views and weigh several alternative takes on what the recent profitability and capital returns might mean for future performance.
Explore another Ryerson Holding fair value estimate, including one that suggests it could be worth just $33.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ryerson Holding research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Ryerson Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ryerson Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ryerson Holding?
Ryerson Holding's latest results give you one reference point, but you can widen your opportunity set by scanning other businesses with different balance sheet strength, income profiles, and risk levels using the Simply Wall St Screener.
- If you care most about resilient financial footing, start with a list of solid balance sheet and fundamentals (24 results) that keeps cash and debt quality front and center.
- For income focused investing, review a curated 5 dividend fortresses that couples higher yields with supporting fundamentals.
- If you want potential value on your side, scan a focused 19 high quality undiscovered gems that highlights under-followed companies with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com