


EN
Paymentus Holdings (PAY) Stock Looks Expensive As Earnings Face A Higher Bar
Paymentus Holdings has delivered a strong multi‑year share price run, and that kind of move naturally puts its earnings under a brighter spotlight. With the stock recently closing at US$33.49, the open question is whether that level is supported by what the business is currently earning and what it can reasonably generate over time.
- Over the past 3 years the stock has gained 106.3%, which raises the stakes on whether its current earnings profile can shoulder that kind of re-rating.
- Recent company updates highlighted growing transaction volumes and a larger Bill Wallet user base, which can feed into expectations for how quickly Paymentus might scale earnings relative to any Fair Ratio style benchmark on its P/E.
- There is a second opinion on Paymentus Holdings worth weighing. See what analysts think Paymentus Holdings's shares could be worth.
For investors, the debate is whether Paymentus Holdings' current earnings are sufficient to justify the share price after this multi year climb.
If you are weighing whether Paymentus Holdings' earnings justify the recent share price move, it can help to compare it with a wider field of 35 high quality undervalued stocks as another research starting point.
Has Paymentus Holdings Run Too Far on Earnings?
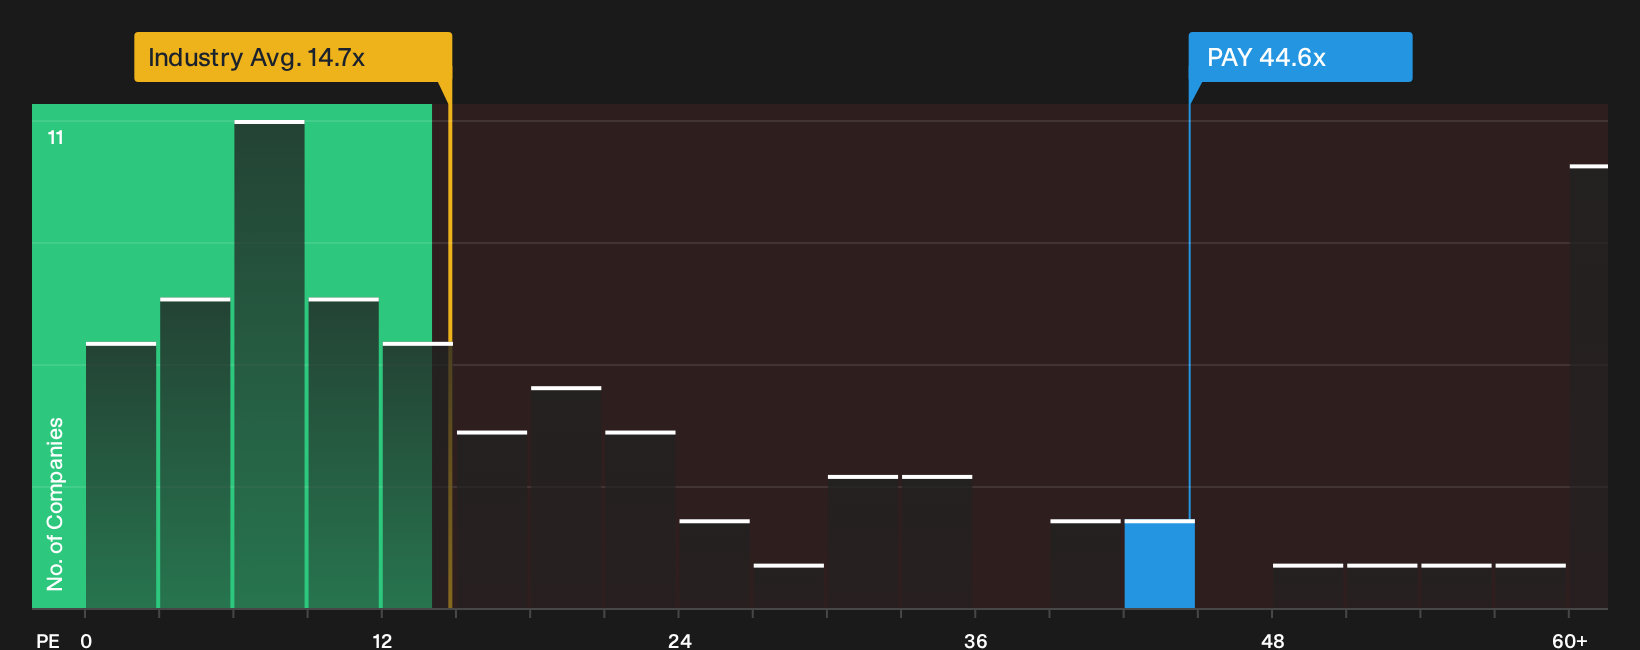
The P/E lens fits Paymentus Holdings because earnings are now a more meaningful part of the story after recent profit updates. At a current P/E of about 44.6x, the stock trades at a clear premium to the diversified financial industry average of roughly 14.7x and also above the peer group on about 36.4x. Those numbers indicate that buyers today are willing to pay materially more for each dollar of Paymentus earnings than is typical for the sector.
The Fair Ratio model, which estimates what a more tailored multiple might look like based on factors such as growth profile, margins and risk, points to a lower P/E than where Paymentus is currently priced, so on this framework the shares screen as overvalued. Because management recently highlighted record Q3 2026 earnings progress and reiterated its confidence in meeting full year targets, the present valuation suggests the market is already incorporating much of that enthusiasm. The key question is whether Paymentus can keep justifying that premium or whether investors may start to prefer a cheaper entry point based on this P/E. Explore the numbers behind Paymentus Holdings's P/E valuation.
The Paymentus Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Paymentus Holdings valuation puzzle leaves off. They spell out which future paths for growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price. Each scenario anchors a fair value to a particular mix of potential catalysts and risks so you can see over time which version of the story appears to be unfolding on the Community page.
One of the top community narratives on Paymentus Holdings: 17% undervalued
"The current valuation implies that the stock price does not yet fully credit Paymentus Holdings for its raised 2026 revenue and EBITDA outlook..."
Discover why this Narrative puts Paymentus Holdings at 17% undervalued.
Paymentus Holdings: why the story is not finished at today's share price
Price and current earnings only tell you where Paymentus Holdings stands today. The next layer is how professional analysts map out its profit and revenue path over the coming years, and how that compares with where the stock trades right now. Explore where analysts expect Paymentus Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com