


EN
What Does Stanley Black & Decker (SWK) Raising Outlook And A $1 Billion Buyback Change?
- Stanley Black & Decker (NYSE: SWK) raised its 2026 earnings outlook following stronger than expected third quarter results reported this week.
- The tools and industrial group paired the upgraded 2026 guidance with a new US$1b share repurchase authorization.
- Management framed the buyback and outlook update as a response to recent operational execution and financial performance in the third quarter.
- The higher 2026 earnings outlook and US$1b repurchase plan only tell part of the Stanley Black & Decker story. Take a look at 1 warning sign we have identified for Stanley Black & Decker.
For more ideas in the tools and industrial income space, you can compare Stanley Black & Decker with peers through 5 dividend fortresses.
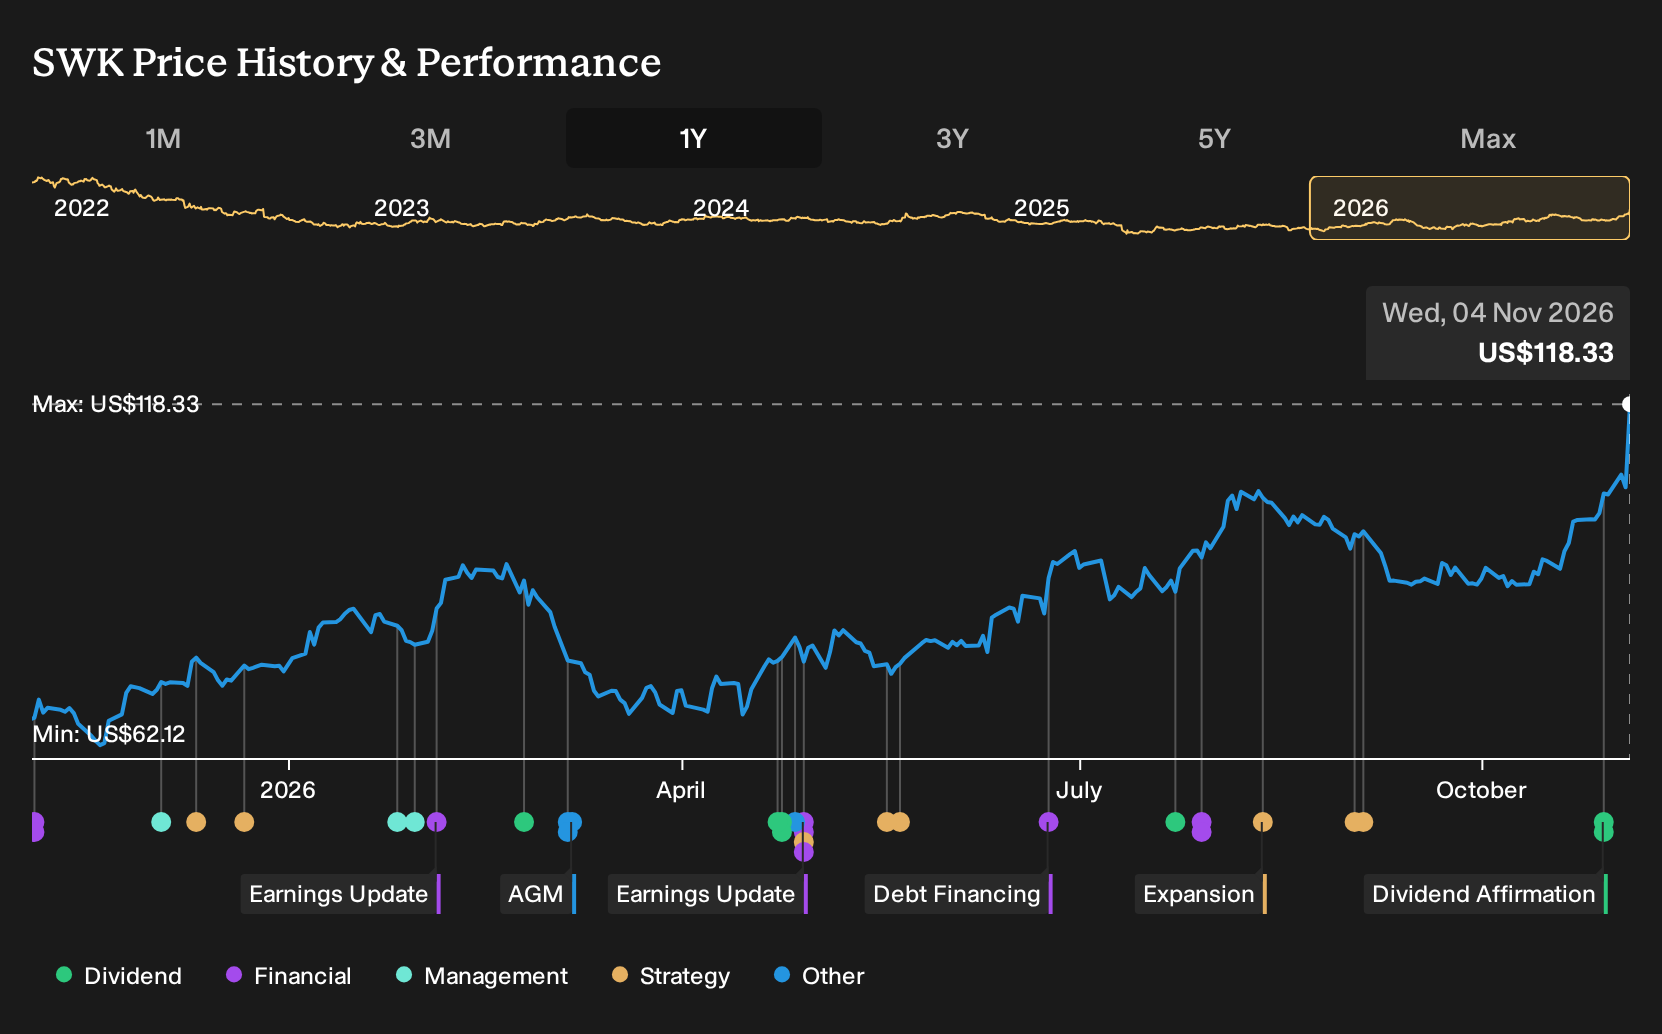
Stanley Black & Decker, a US$15.8b machinery group, earns most of its clout from a broad portfolio of hand tools, power tools, outdoor equipment, and accessories sold across the US, Canada, other parts of the Americas, Europe, and Asia. As a result, changes in its earnings outlook and capital return plans can ripple through a wide global customer base.
See which insiders are buying and selling Stanley Black & Decker following this latest news.
What Stanley Black & Decker’s upgraded outlook and buyback signal for investors
The raised 2026 GAAP EPS range to US$5.45 to US$5.85, alongside a fresh US$1b repurchase authorization, signals that Stanley Black & Decker’s leadership is more confident in the earnings path than it was earlier in the year. Strong third quarter profit, with net income of US$272.1 million and diluted EPS of US$1.83, gives that message some backing and reinforces the existing case that this is a cash generative tools and industrial business with an active capital return policy. For shareholders, the key shift is sentiment. Management is effectively saying that recent operational execution justifies committing more balance sheet capacity to buybacks, even with a history of higher debt on the books.
This update does not settle how durable those earnings will be once one off supports, such as tariff refunds, are no longer reflected in results. The clearest checkpoint is the next few quarterly reports through 2027. Investors can watch whether EPS and free cash flow stay consistent with the higher 2026 range while Stanley Black & Decker continues to fund both the regular US$0.84 dividend and ongoing repurchases under the new US$1b program that runs through October 29, 2029.
The next check on Stanley Black & Decker before you act
Before you treat today’s update as your main guide, the real filter is where analysts expect Stanley Black & Decker to be a few years from now. See where analysts expect Stanley Black & Decker to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com