


EN
Is Mitie Group (LSE:MTO) Overvalued Given Its Earnings Power?
Mitie Group has delivered a powerful run over the past few years, so the live question for you today is whether the current share price is properly supported by its earnings profile. With the stock closing at £2.10, the issue is whether that level still lines up with what the business is actually generating in profit.
- Over the past 5 years the share price has gained 264.5%, which puts a lot of weight on the idea that Mitie Group's earnings power can justify a much higher valuation than in the past.
- The business relies on converting long-term support and facilities contracts into consistent profit, so the durability of those margins and the cash that falls out of them matters directly for what investors are willing to pay for each pound of earnings.
- The analysts covering Mitie Group have run their own numbers. See what analysts think Mitie Group's shares could be worth.
The stock's next move may depend on whether the current valuation can be explained by the earnings that Mitie Group is producing today and is expected to generate over time.
If you want other ideas to compare with Mitie Group using this earnings-focused lens, a targeted screener built around 14 high quality undervalued stocks can be a useful next step in your research.
Is Mitie Group Getting Expensive on Earnings?
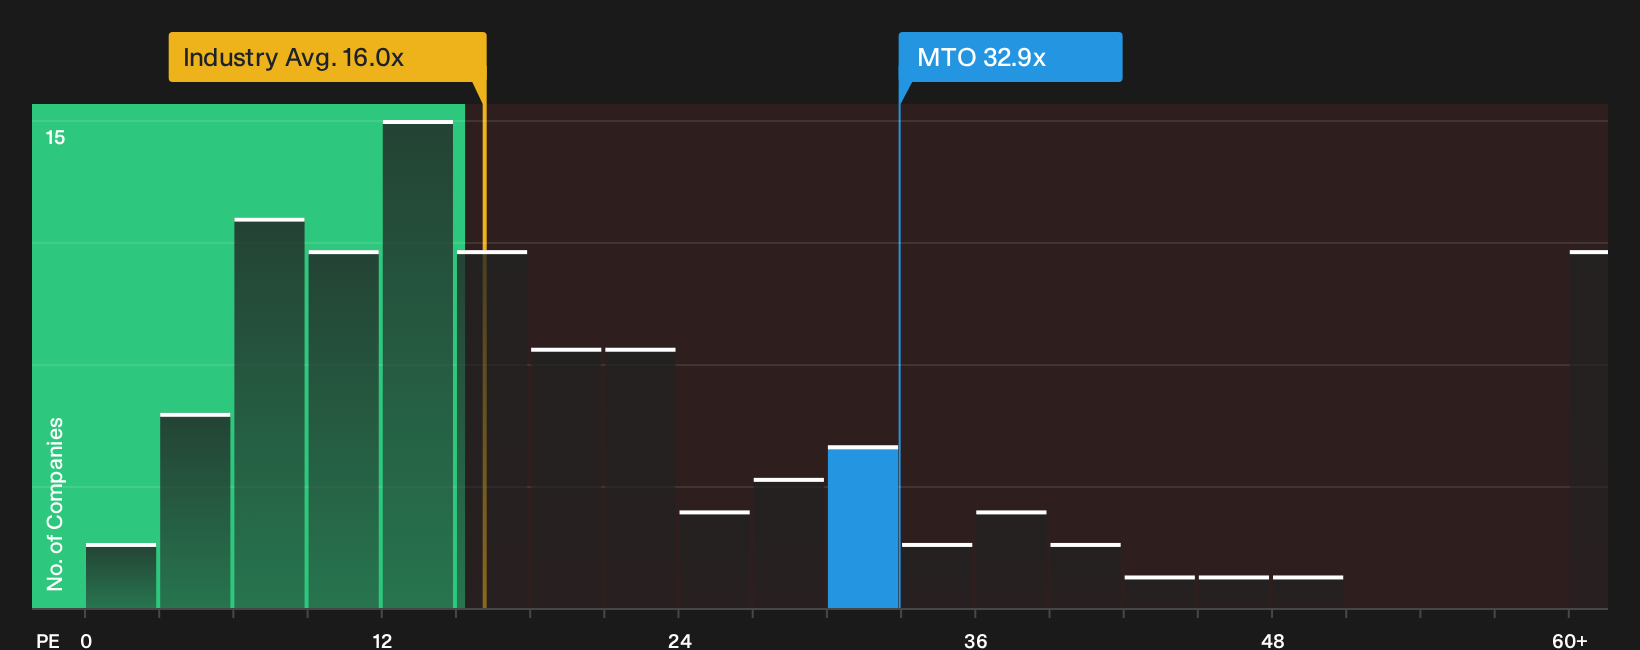
P/E suits a service contractor like Mitie Group because profit is a core yardstick for how efficiently it turns long-term contracts into cash. On this measure, the shares trade on about 32.9x earnings, which is well above the Commercial Services industry average of roughly 15.0x and also higher than the peer group at about 21.6x. That sort of gap indicates the market is attaching a premium to the quality or perceived resilience of Mitie Group’s current profit stream.
The fair-value framework that adjusts for Mitie Group’s own growth profile, profitability and risk points to a lower earnings multiple than the one implied by the present share price. As a result, the P/E screens as overvalued against that tailored yardstick rather than just against broad sector benchmarks. For an investor comparing options in this space, the key question is whether the contract base, margins and cash generation profile are strong enough to justify paying a higher price for each pound of earnings than both peers and the model suggest. Explore the numbers behind Mitie Group's P/E valuation.
The Mitie Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E debate on Mitie Group leaves off. They spell out the specific profit, margin and contract assumptions that would need to hold for the shares to look meaningfully cheap or clearly stretched. Each one links its number to a clear view on how Mitie Group's growth path, profitability and risk profile could evolve, giving you something concrete to return to as fresh results and contract news arrive on the Community page.
Mitie Group attracts two quite different readings from the community, with one side seeing more runway left than the other at roughly similar valuation anchors.
Bull case: roughly fairly valued
"Rising demand for decarbonization, energy efficiency and upgraded infrastructure in areas such as health care, transport, aviation and defense is feeding into a project pipeline of more than £7.0b…"
Discover why this Narrative puts Mitie Group at roughly fairly valued.
Bear case: roughly fairly valued
"The margin enhancement initiatives that were intended to support an operating margin above 5% by FY27 now sit alongside Project Prio, a 70 person AI programme expected to cover more than 75% of the £5b cost base from FY28…"
Explore why this Narrative puts Mitie Group at roughly fairly valued.
The Mitie Group share price is only one piece of the decision
Valuation tells you what you are paying, but not everything you might be taking on, because Simply Wall St's broader checks have also picked up potential areas of concern for Mitie Group that deserve a closer look. Take a closer look at 4 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com