


EN
ADT (ADT) Stock Trades At A Discount Despite Its 84% Run
ADT Inc. has climbed to a recent close of US$9.90, with the share price moving sharply in recent weeks as investors digest a take‑private offer and the business’s earnings profile. With the stock now trading closer to the proposed US$10.00 deal price, the key issue is how well that market value lines up with the company’s profit generation.
- Over the past 3 years, ADT has returned 83.6%, which puts a lot of weight on the question of whether its earnings foundation justifies that kind of share price performance.
- The agreed US$10.00 per share all cash acquisition by Thrive Holdings, backed by significant debt financing, may shape how investors think about ADT’s earnings power, balance sheet risk and the durability of its cash flows as a private company.
- The analysts covering ADT have run their own numbers. See what analysts think ADT's shares could be worth.
The issue now is whether ADT’s current share price is appropriately supported by its earnings when set against the Fair Ratio benchmark.
If you are weighing whether ADT’s US$9.90 price and take private premium feel fair for its earnings profile, a focused stock screen of 35 high quality undervalued stocks can give you more ideas for comparison.
Does ADT Look Undervalued on Earnings?
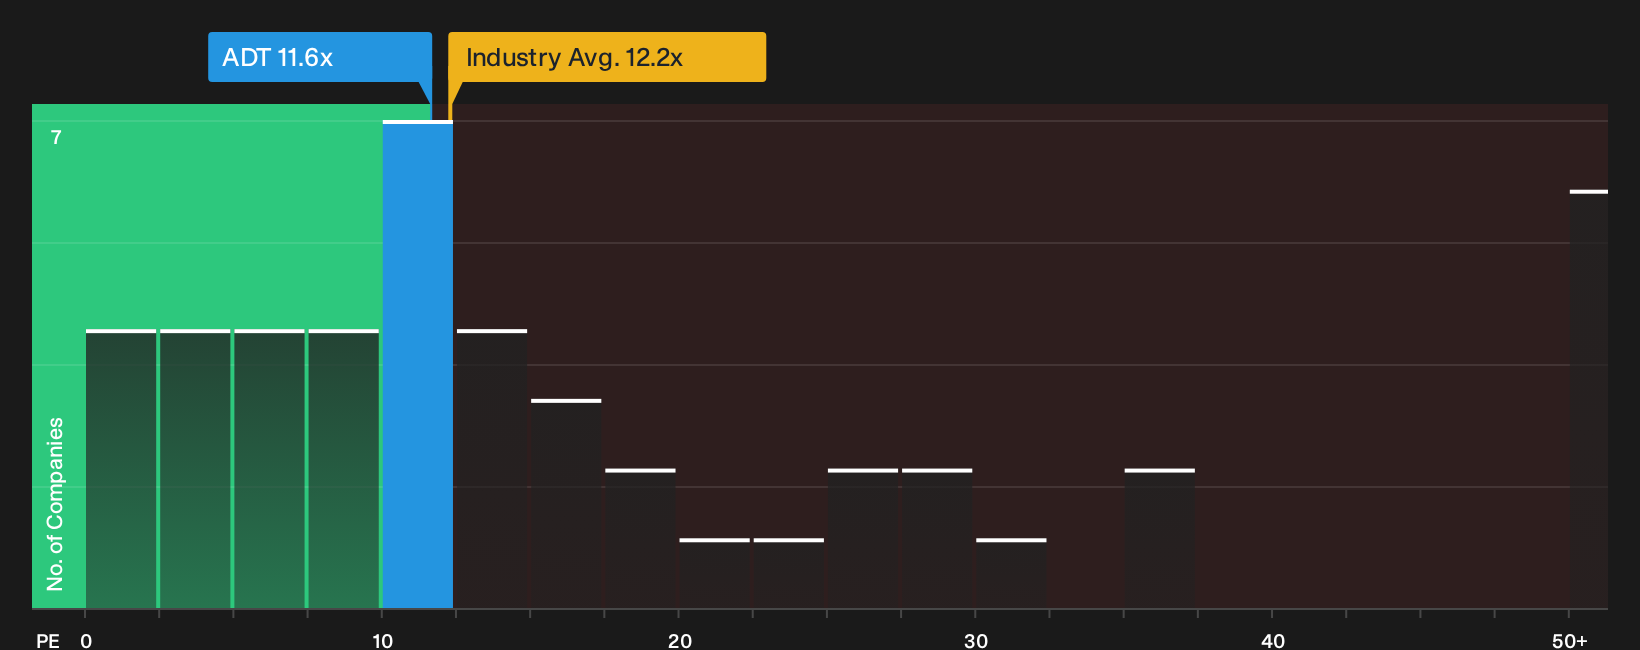
The P/E ratio suits ADT because investors are focused on the earnings that support its take private price. At a current P/E of 11.6x, the stock trades slightly below the wider Consumer Services sector on 12.2x, which points to a modest discount against the broader group of listed operators.
Against closer peers, the picture looks different. The peer set averages a much richer 22.1x, and the Fair Ratio model, which blends ADT’s growth outlook, profitability, size and risk profile into a tailored benchmark, also places the current multiple below where that framework would expect it to trade. Despite the all cash US$10.00 per share offer from Thrive Holdings supporting the share price, the earnings multiple still screens as undervalued relative to that Fair Ratio yardstick. Explore the numbers behind ADT's P/E valuation.
The ADT Narrative: What Would Justify Today's Price?
Narratives on ADT sit between the current valuation puzzle and the future outcomes that would need to play out on growth, margins and earnings for today’s price to look meaningfully high or low. Each scenario lays out its own assumptions for ADT’s potential worth so you can compare those moving parts with the company’s reported results over time rather than relying on a single multiple or model output.
Community views on ADT split between those who see more upside in the AI and cloud shift and those who focus on balance sheet strain.
Bull case: roughly fairly valued
"The integration of Origin AI’s WiFi based presence sensing and about 200 related patents into ADT+ smart plugs, with pilots in fall 2026 and commercialization starting in early 2027, gives ADT a path to add new sensing tiers such as aging in place services that can widen use cases and support higher recurring revenue per account..."
Discover why this Narrative puts ADT at roughly fairly valued.
Bear case: 21% overvalued
"Bearish analysts are absolutely correct that the company carries a heavy debt load and that Apollo's ongoing equity sales act as an artificial ceiling on momentum..."
Explore why this Narrative puts ADT at 21% overvalued.
One more angle on ADT before you make a move
Price multiples tell you what ADT is worth today in the market, and the projections that analysts have mapped out for the next few years offer a different lens on where expectations sit. Explore where analysts expect ADT to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com