


EN
Corcept Therapeutics (CORT) Stock Trades At A Premium On Strong Q3 Earnings
Corcept Therapeutics has seen a sharp pullback in recent weeks after a strong multi year run. This puts fresh focus on whether the current share price is still in line with what its earnings can support. Recent news around its cortisol modulator portfolio has kept the story moving, but the key issue for you is what those profits are worth today.
- Over the past 5 years, Corcept Therapeutics has returned about 251.3%, so a lot of future earnings power is already embedded in the recent share price history.
- Recent positive trial results for Lifyorli in ovarian cancer and progress on cortisol modulators can influence how investors think about the durability and trajectory of the business's profit stream.
- The analysts covering Corcept Therapeutics have run their own numbers. See what analysts think Corcept Therapeutics's shares could be worth.
The stock's next move may depend on whether that recent price, after a steep pullback, is adequately supported by the earnings Corcept Therapeutics is generating today.
If you are considering Corcept Therapeutics following this earnings-driven move and want context on similar opportunities, compare it with companies in the 38 healthcare AI stocks.
Is Corcept Therapeutics Getting Expensive on Earnings?
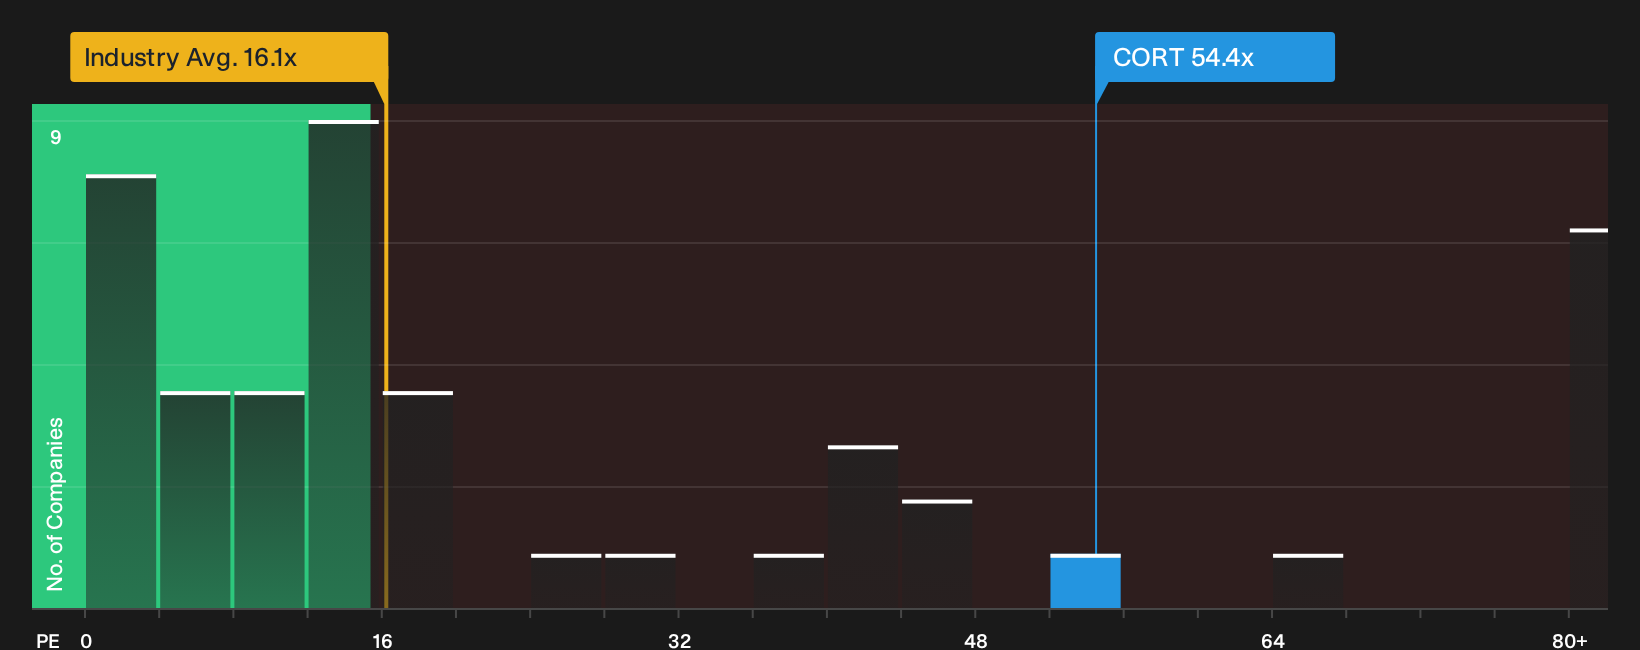
For Corcept Therapeutics, the P/E multiple is the cleanest way to anchor the recent share price move to the profits already being reported. The stock trades on about 54.4x earnings, which is well above the Pharmaceuticals sector average of 16.1x but below the peer group on roughly 63.9x. That puts Corcept in the higher valuation bracket where investors are paying a steep price for each dollar of current profit.
A tailored fair P/E level, which factors in Corcept Therapeutics' own growth profile, profitability and risk, sits below the current multiple, so on this lens the shares screen as overvalued. Despite the strong Q3 2026 update and the lift in confidence around the cortisol modulator franchise, the valuation still asks you to pay more than this framework suggests for the earnings on offer today. If you want to see how that gap looks in hard numbers and compare it with other healthcare stocks, you can run Corcept Therapeutics through the same P/E lens in the. Explore the numbers behind Corcept Therapeutics's P/E valuation.
The Corcept Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Corcept Therapeutics pick up where the valuation puzzle leaves off by explaining which future paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today's price. Each scenario assigns a fair value to a clear storyline about Corcept Therapeutics' potential catalysts and key risks so you can follow over time which version appears to be taking shape on the Community page.
Community views on Corcept Therapeutics split between those focused on the breadth of the cortisol platform and those zeroed in on Korlym erosion and earnings quality.
Bull case: 44% undervalued
"The shift from a single Cushing’s product to a broader cortisol modulation portfolio, including Lifyorli in ovarian cancer, late-stage oncology programs, and Phase II or III efforts in ALS and MASH, points to a more diversified revenue base..."
Discover why this Narrative puts Corcept Therapeutics at 44% undervalued.
Bear case: 58% overvalued
"The Federal Circuit decision against its attempt to block a generic Korlym entrant raises the possibility of deeper erosion in its largest product line..."
Explore why this Narrative puts Corcept Therapeutics at 58% overvalued.
An unresolved piece of the Corcept Therapeutics puzzle
Price and profits only tell part of the story for Corcept Therapeutics, because the people steering the business and the way they are rewarded can heavily shape what happens next. See who runs Corcept Therapeutics and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com