


EN
Alamar Biosciences (ALMR) Stock May Look Fully Valued Following Raised 2026 Guidance
Alamar Biosciences has seen its stock come under pressure in recent weeks, even as attention focuses on what its commercial progress might mean for the value investors place on its sales. With the price moving quickly while new collaborations and research results keep arriving, the question is how well the current market valuation lines up with the revenue base supporting it.
- The share price has fallen 28.2% over the past month, which puts fresh focus on whether the recent level still reflects what investors are willing to pay for each dollar of Alamar Biosciences' sales.
- New partnerships around the NULISA platform and large proteomic studies can influence how investors think about future revenue potential and the sales multiples they are prepared to accept today.
- Your read on Alamar Biosciences is one view; the desks covering it have another. See what analysts think Alamar Biosciences's shares could be worth.
The issue now is whether the current share price of Alamar Biosciences is justified by its sales when set against the Fair Ratio benchmark.
If you are evaluating Alamar Biosciences using its sales multiple after a sharp 28.2% share price decline over 30 days, it may be helpful to compare this metric with 35 high quality undervalued stocks.
Does Alamar Biosciences Look Pricey on Sales?
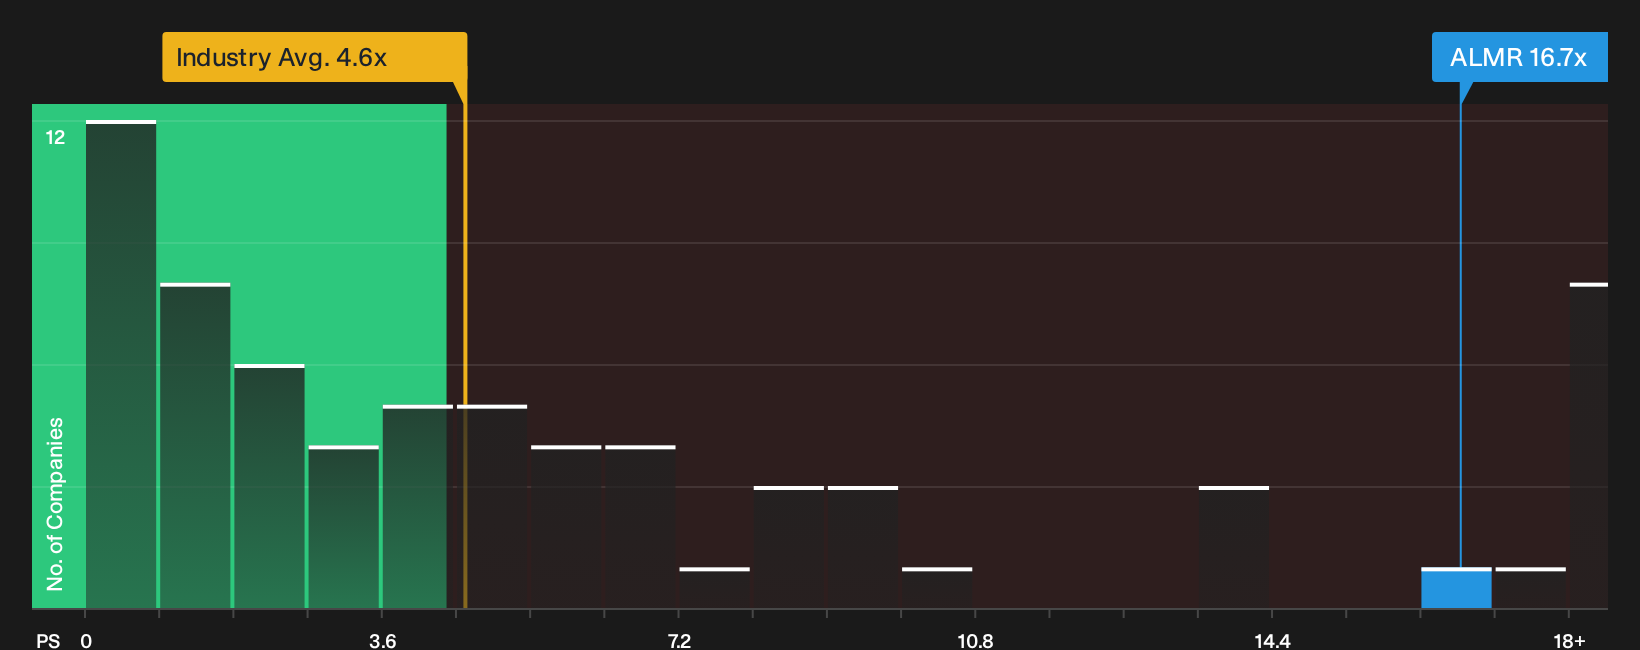
P/S tends to fit Alamar Biosciences because revenue is still the cleaner anchor than earnings for a loss‑making life sciences platform. On this yardstick, the stock trades on a P/S of 16.7x, compared with about 4.6x for the wider Life Sciences industry and roughly 8.3x across closer peers. That is a rich revenue tag in simple sales terms, even before you weigh factors like contract mix, research intensity and how repeatable current projects might be.
The Fair Ratio, which blends the company’s growth profile, margins, market size and risk into a tailored benchmark, sits below the current 16.7x level, so the shares screen as overvalued on this framework. Because the recent Q3 2026 update flagged strong revenue momentum and larger collaborations, the market appears willing to pay a premium multiple for that trajectory. Yet the implied valuation still runs ahead of what this model suggests for Alamar Biosciences at today’s price. Explore the numbers behind Alamar Biosciences's P/S valuation.
The Alamar Biosciences Narrative: What Would Justify Today's Price?
Narratives for Alamar Biosciences pick up where the valuation puzzle leaves off by spelling out which combinations of revenue growth, profitability and earnings power would need to hold for the share price to look meaningfully higher or lower than it does today on Simply Wall St's Community page. Rather than just pointing to a single multiple or model result, each scenario lays out the key drivers behind its view of value so you can compare those building blocks with future results as they emerge.
One of the top community narratives on Alamar Biosciences: 23% undervalued
"Growing use of blood based biomarkers in neurodegenerative research, including tau focused drug programs and co pathology classification, supports higher demand…"
Discover why this Narrative puts Alamar Biosciences at 23% undervalued.
The open question for Alamar Biosciences, what are experts modeling a few years from now?
Valuation tells you what the market is paying today, but the picture feels incomplete until you compare it with where professional coverage sees this business several years out. Explore where analysts expect Alamar Biosciences to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com