


EN
Is Camtek (CAMT) Priced For Perfection Or Still A Bargain?
Camtek has seen a sharp pullback in recent weeks, which puts a fresh spotlight on whether the current share price lines up with what its earnings can support. After a strong multiyear run, the question for investors is how much of the recent news and expectations are already reflected in the valuation.
- Over the past 5 years the stock has returned about 129.9%, which makes the earnings multiple especially important for anyone asking how much upside is left from here.
- Recent company updates point to growing demand tied to high end chip packaging for AI applications, which can support expectations for stronger profitability and influence what investors are willing to pay for each dollar of earnings.
- There is a second opinion on Camtek worth weighing. See what analysts think Camtek's shares could be worth.
The issue now is whether Camtek's current price is justified by its earnings when set against the Fair Ratio benchmark.
If you want more context around Camtek's AI packaging story and valuation debate, it can help to compare it with other 53 AI infrastructure stocks.
Is Camtek Still Cheap on Earnings?
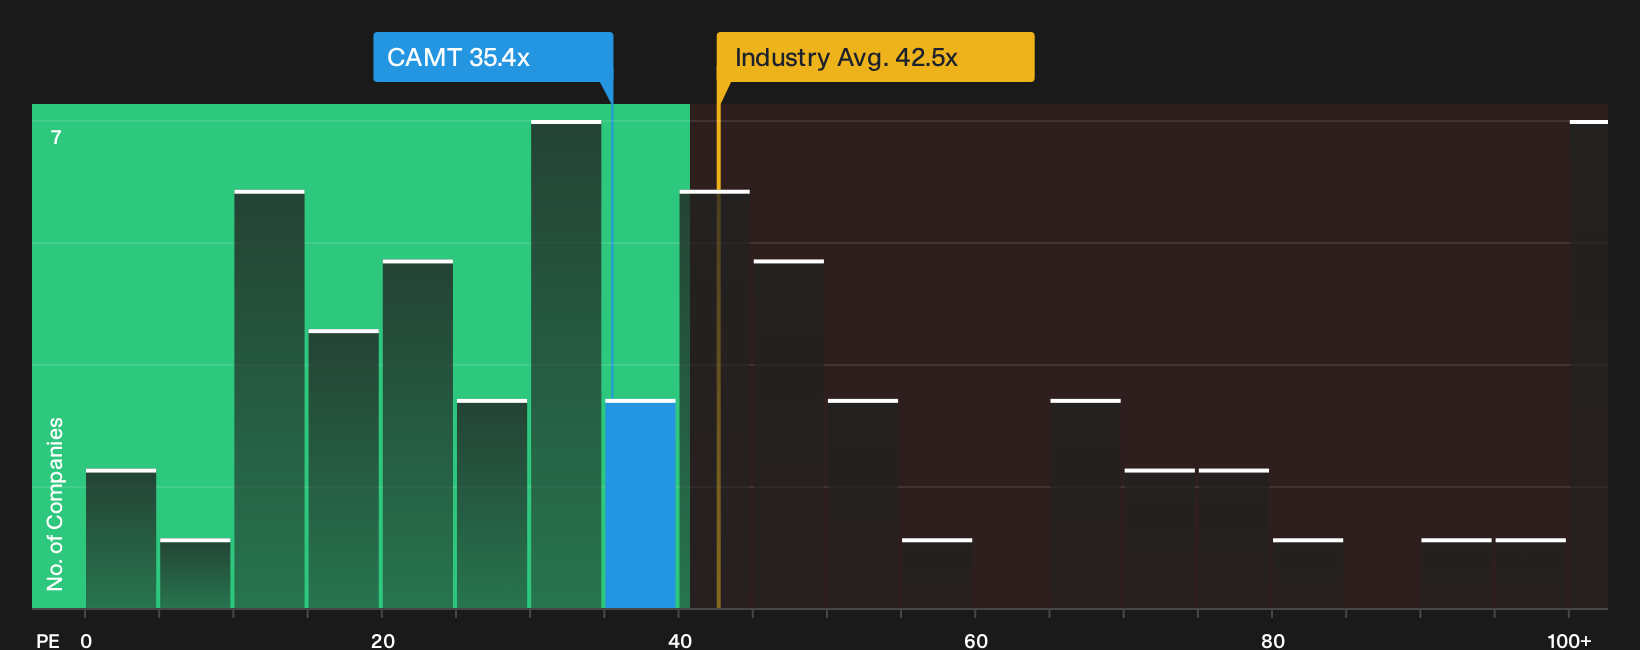
For Camtek, the P/E ratio is a clear way to see what the market is willing to pay for each dollar of current earnings. The stock trades on a P/E of 35.4x, which sits below both the semiconductor sector average of 42.5x and the peer group at 47.6x. As a result, the earnings multiple is not at the top of the range for this corner of the chip equipment space.
Because the Fair Ratio framework looks at factors such as growth expectations, profitability and risk, a P/E below that tailored benchmark points to Camtek trading on an earnings multiple that screens as undervalued on this model. Despite Morgan Stanley flagging pricing pressure in 2D inspection and taking a more cautious stance on midterm targets, the current P/E still implies a discount to what this methodology suggests could be justified by the company’s profile. Explore the numbers behind Camtek's P/E valuation.
The Camtek Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Camtek valuation puzzle leaves off by spelling out which paths for revenue, profitability and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than today’s P/E implies, and they sit on Simply Wall St’s Community page. Each one presents Camtek's fair value as a thesis about the business that can be revisited over time as new information arrives.
One of the top community narratives on Camtek: 40% undervalued
"Rising inspection and metrology intensity in advanced packaging and HBM4, where Camtek is the reference 3D metrology tool for major HBM players..."
Discover why this Narrative puts Camtek at 40% undervalued.
One more Camtek check that sits outside the share price
Before you stop at the P/E and sector comparisons for Camtek, it is worth asking who is steering the ship, how their pay is structured, and whether those incentives align with your goals as a shareholder. See who runs Camtek and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com