


EN
KLA (KLAC) Stock Looks About Right On Fresh AI Growth News
KLA Corporation has had a powerful multi year run followed by a sharp pullback in recent weeks, which puts a spotlight on whether the current share price still lines up with the earnings behind it. With fresh headlines highlighting its role in chip equipment for AI related spending, the question now is how much profit power the market is building into today’s valuation.
- Over the past 5 years, KLA has delivered a total return of 288.9%, so a lot of future earnings strength is already central to the story for anyone buying or holding today.
- Recent updates have highlighted strong profitability and demand tied to investments in AI and high performance computing, which can shape expectations for how resilient KLA’s margins and cash generation might be over the next few years.
- Your read on KLA is one view; the desks covering it have another. See what analysts think KLA's shares could be worth.
The issue now is whether KLA’s current market value is adequately backed by its earnings when measured against the Fair Ratio benchmark.
If you want to stress test the same earnings question that hangs over KLA across a wider set of chip related opportunities, start with 53 AI infrastructure stocks.
Is KLA Fairly Priced on Earnings?
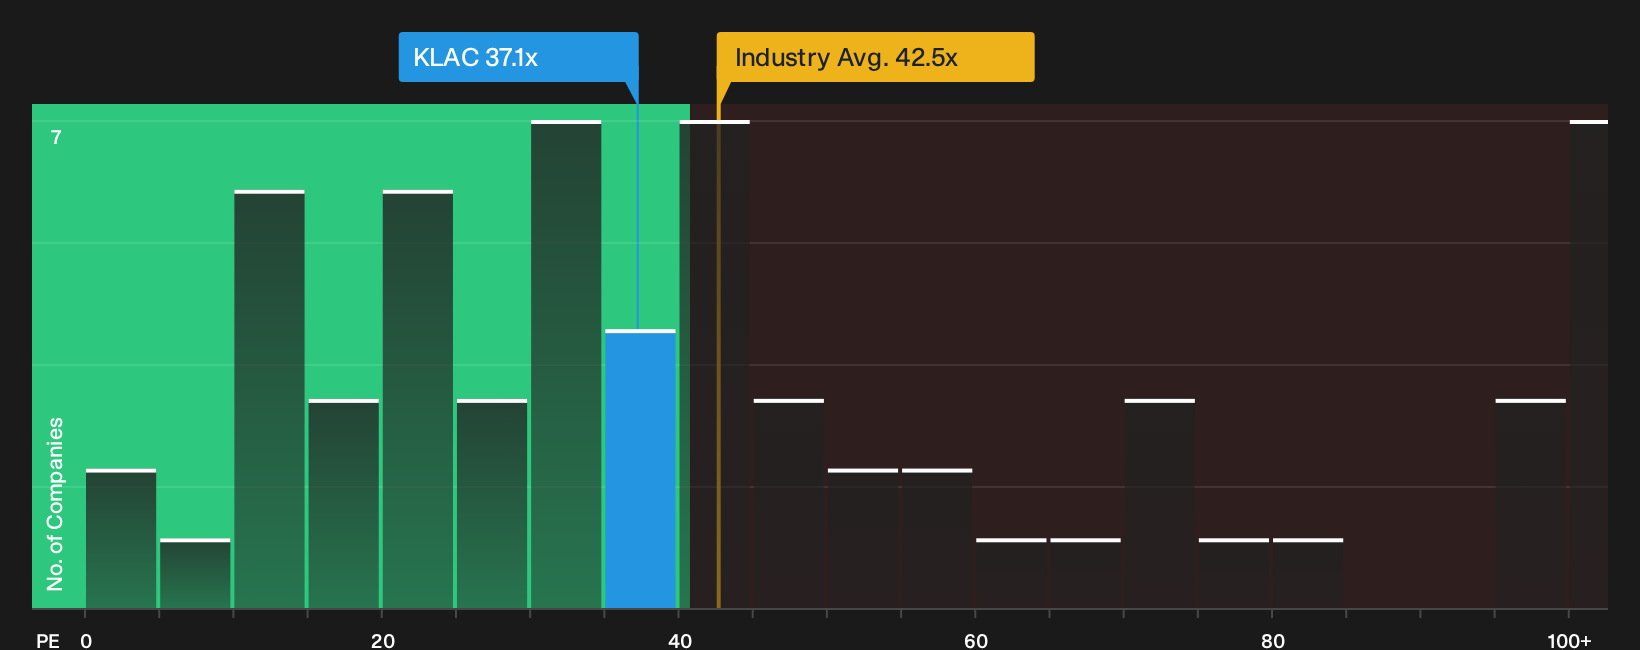
The P/E ratio suits KLA because earnings remain the main anchor for how investors frame its role in the AI equipment cycle. Right now the stock trades on about 37.1x earnings, which is above the semiconductor sector average of 42.5x but slightly richer than the peer group on roughly 34.4x. That sets KLA up as a premium play compared with similar companies rather than with the broader chip industry label.
The Fair Ratio, which reflects what investors might typically pay for a business with KLA’s growth profile, margins, size and risks, sits just below the current P/E so the shares screen broadly about right on this lens. Because the latest results highlighted strong AI driven demand and high profitability, the market seems comfortable keeping KLA stock on a multiple that leans modestly above close peers without stretching far beyond what this framework flags as reasonable. Explore the numbers behind KLA's P/E valuation.
The KLA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for KLA link the valuation puzzle above to concrete expectations about the future. Narratives set out which paths for KLA's growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than today. They sit on the company’s Community page as a way to turn a single ratio into a set of assumptions you can watch over time to see if they still look realistic.
One of the top community narratives on KLA: 33% undervalued
Analysts expect KLA to benefit from strong AI driven wafer equipment demand, rising process control intensity, and growing advanced packaging and services contributions...
Discover why this Narrative puts KLA at 33% undervalued.
The unresolved piece for KLA: what the professionals think comes next
Everything so far has focused on what KLA looks like today. Yet analyst models sketch out where revenue, profits and cash flow might land several years from now, which gives you a different measuring stick for the current valuation. Explore where analysts expect KLA to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com