


EN
Everest Group (EG) Stock Looks Undervalued Despite Reserve Strengthening
Everest Group has enjoyed a strong run in recent years, and with the stock last closing at US$421.30, the central question now is whether that price still lines up with what its earnings can justify. Recent news around portfolio reshaping and reserve decisions only sharpens the focus on how much profit power the market is paying for today.
- Over the past 5 years, Everest Group has delivered a 73.7% share price gain, which puts real pressure on the current earnings base to support that kind of long term wealth creation story.
- The planned exit from commercial retail insurance in Latin America and the decision to build casualty reserves by more than US$850m can influence future profitability, the timing of cash flows, and the level of earnings that become the anchor for any P/E discussion.
- Your read on Everest Group is one view; the desks covering it have another. See what analysts think Everest Group's shares could be worth.
The issue now is whether Everest Group's present earnings profile is strong enough to make the current share price look well supported on an earnings basis.
If you want a second reference point alongside Everest Group while you weigh earnings power against price, a focused stock screen built around 35 high quality undervalued stocks can be a useful place to start.
Does Everest Group Look Undervalued on Earnings?
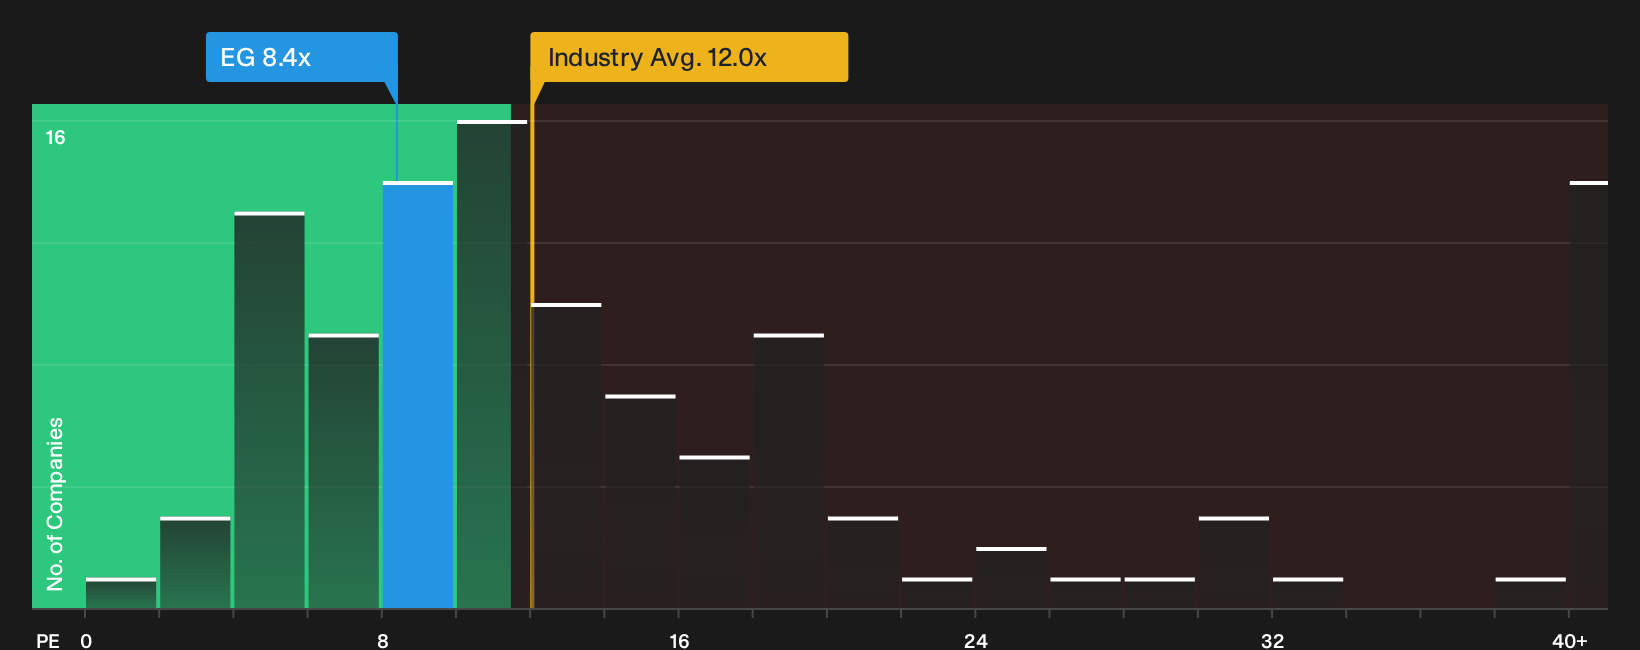
The P/E ratio is a useful lens for Everest Group because investors often anchor insurance valuations on how much they are paying for each dollar of earnings. Everest Group trades on roughly 8.4x earnings, which is below both the Insurance industry average of about 12.0x and a peer group closer to 9.1x. Based on the tailored fair multiple that reflects Everest Group's own return profile and risk set, the current P/E also sits below where the stock might trade if the business were priced in line with those fundamentals.
Because management recently strengthened casualty reserves and is exiting Latin American retail operations, the current earnings stream already factors in some caution around future claims. Even with that more conservative stance on reserves, the market still values Everest Group at a discount on this P/E framework. That gap brings investors back to the question of whether the quality and durability of its earnings justify a closer look at the multiple now. Explore the numbers behind Everest Group's P/E valuation.
The Everest Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Everest Group valuation puzzle leaves off and explain which assumptions on growth, margins and earnings would need to hold for the stock to be worth substantially more or less than today’s price. Each Everest Group narrative is framed as a thesis about how the business might justify its current valuation over time, so you can track how that reasoning holds up as new information arrives on the Community page.
One of the top community narratives on Everest Group: roughly fairly valued
"The current valuation implies that Everest Group's share price does not fully reflect its mid teens operating ROE, high capital return through buybacks and dividends..."
Discover why this Narrative puts Everest Group at roughly fairly valued.
One more Everest Group check before you close the tab
Price multiples tell you what the market pays for Everest Group today, but the projections professionals are using for this insurer a few years from now can completely change how that tag looks. Explore where analysts expect Everest Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com