


EN
Atlanticus Holdings (ATLC) Could Be 25% Undervalued On Q3 Earnings Focus
Atlanticus Holdings (ATLC) moves into focus as investors look ahead to its Q3 2026 earnings release and conference call on November 5, shortly before management appears at the KBW Fintech Ecosystem Conference.
Recent trading has been brisk. Atlanticus Holdings’ 1-day share price return of 7.85% and 30-day share price return of 7.18% contrast with a largely flat 90-day move. At the same time, a 50.34% year to date share price return and very strong multi year total shareholder returns suggest momentum has been building rather than fading.
Scan how Atlanticus Holdings compares by running the same filters across a hand picked 35 high quality undervalued stocks that pair resilient balance sheets with positive share price momentum.
After a 50% year to date run, Atlanticus Holdings still sits at a material discount to analyst targets. Is the market being prudently skeptical, or overly cautious about what the current valuation already reflects?
Most Popular Narrative: 25% Undervalued
Against a last close of $99.75, the most followed narrative pegs Atlanticus Holdings at a fair value of $133.50, with that gap resting on aggressive revenue and earnings assumptions that stretch well beyond the current run rate.
Atlanticus Holdings provides credit and related financial products to near prime and underserved consumers, primarily through general purpose cards and point of sale programs.
The acquisition and integration of Mercury Financial has roughly doubled the balance sheet to about US$7b and brought a US$3b portfolio under Atlanticus portfolio management methods. Management expects this to support higher yields and return on assets over time, directly influencing revenue and earnings.
See why 5 investors see Atlanticus Holdings as 25% undervalued.
Result: Fair Value of $133.50 (UNDERVALUED)
Still, the Atlanticus Holdings story depends heavily on smooth Mercury integration and continued funding support, with any stumble in either area capable of quickly challenging this upbeat narrative.
Find out about the key risks to this Atlanticus Holdings narrative.
Another View: Multiples Paint A Tougher Picture For Atlanticus Holdings
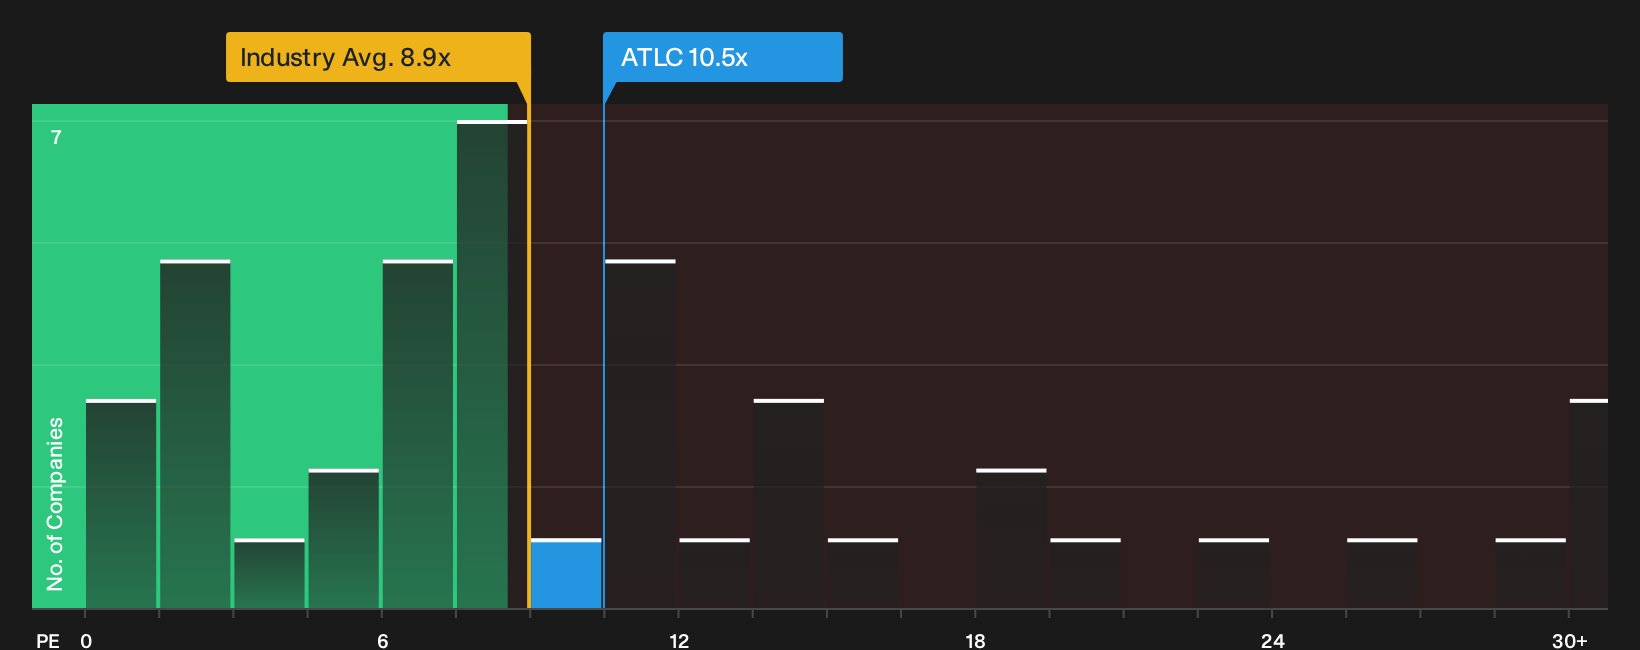
Analyst narratives pitch Atlanticus Holdings as roughly 25% undervalued, yet the current P/E of 10.5x tells a tighter story. The stock trades above both US Consumer Finance peers at 8.5x and its closer peer group at 9.9x, while the fair ratio sits much higher at 16.8x. That mix of premium pricing today and theoretical upside later raises a simple question: How much valuation risk are you really comfortable carrying?
To see how this P/E gap lines up with other fundamentals, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Atlanticus Holdings is clearly mixed, with both optimism and concern in play, so move quickly and pull apart the details for yourself. To weigh those positives against the potential downsides, start with the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Atlanticus Holdings?
If you stop your research with Atlanticus Holdings, you risk missing other opportunities that might suit your goals even better, so widen the net before making a move.
- Target potential upside by scanning a curated 19 high quality undiscovered gems that surfaces under followed businesses with strong underlying fundamentals.
- Prioritise staying power by running your own checks against a list of solid balance sheet and fundamentals (24 results) to see which companies pair resilience with financial discipline.
- Focus on capital protection first and hunt through a 31 resilient stocks with low risk scores designed to spotlight businesses with lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com