


EN
Vulcan Materials (VMC) Posted Mixed Third Quarter Results, Does It Look Fully Valued?
Vulcan Materials (VMC) just released third quarter results that showed slightly lower sales and net income than a year ago, while the nine month figures reflected higher revenue and earnings.
The latest quarterly update has come alongside a sharp shift in sentiment, with Vulcan Materials’ share price posting a 21.22% 1 month share price return and a 12.34% 7 day share price return. The 1 year total shareholder return of 5.20% sits against a much stronger 46.04% over three years, which may suggest that near term momentum has picked up after a steadier stretch.
Scan how Vulcan Materials compares to peers by reviewing our hand picked 31 resilient stocks with low risk scores that have been holding up on quality even as short term earnings headlines shift.
Vulcan Materials has just delivered a strong short term share price bounce on only modest quarterly slippage in sales and profit. For investors, the trade off now is clear: pay up after the run, or wait for a better entry as valuation comes into focus next.
Most Popular Narrative: 4% Undervalued
On the most followed narrative, Vulcan Materials is priced below an estimated fair value of about $311 per share, compared with a last close of $297.69. That gap, even if modest, puts the focus squarely on what might support that valuation over time.
The company's footprint in growing Sunbelt metros continues to line up with a visible pipeline of large public and private projects, including a large volume of data centers and related power and LNG work. About 60% of all large projects are within 50 miles of a Vulcan facility, which can support future aggregates shipments and earnings as those projects move from award to steady production.
See why 14 investors see Vulcan Materials as 4% undervalued.
Result: Fair Value of $311 (UNDERVALUED)
Still, higher diesel costs and any slowdown in government funded projects could quickly pressure Vulcan Materials’ margins and challenge the current undervalued narrative.
Find out about the key risks to this Vulcan Materials narrative.
Another View: Vulcan Materials On Earnings Multiples
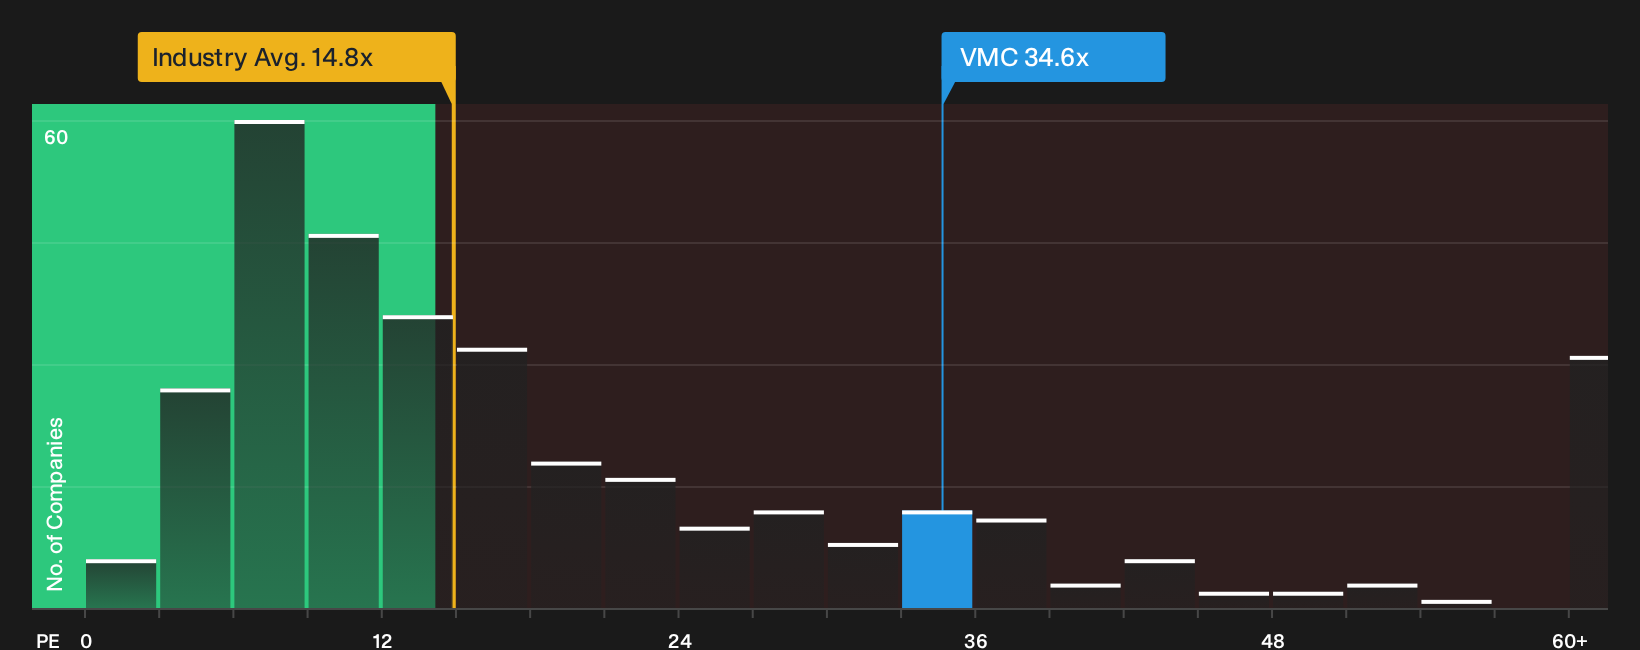
The fair value story built around Vulcan Materials at about $311 per share runs into a very different picture when looking at the P/E ratio. The stock trades on 34.6x earnings, compared with 14.3x for the global Basic Materials industry and 27.2x for its peer group.
Our fair ratio for Vulcan Materials sits at 19.7x, which is well below the current multiple. That gap points to meaningful valuation risk if sentiment cools and the market moves closer to that fair ratio. The question for investors is whether the quality of the business justifies such a premium over time.
For a closer read on how the current price stacks up against earnings power and peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Vulcan Materials so far. If you want to move fast and build your own stance from the data rather than the headlines, start with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Vulcan Materials?
If Vulcan Materials has sharpened your thinking, do not stop here. Broaden your watchlist now with ideas that line up with your own risk and return preferences.
- Target potential mispricings by scanning a curated 35 high quality undervalued stocks that filters for quality businesses trading below what their fundamentals may justify.
- Build a steadier income stream by focusing on a focused 5 dividend fortresses that highlights companies offering higher yields with supporting fundamentals.
- Prioritise financial strength by reviewing a list of solid balance sheet and fundamentals (24 results) so you are not caught off guard when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com