


EN
What Vestas Wind Systems Doubters Got Wrong
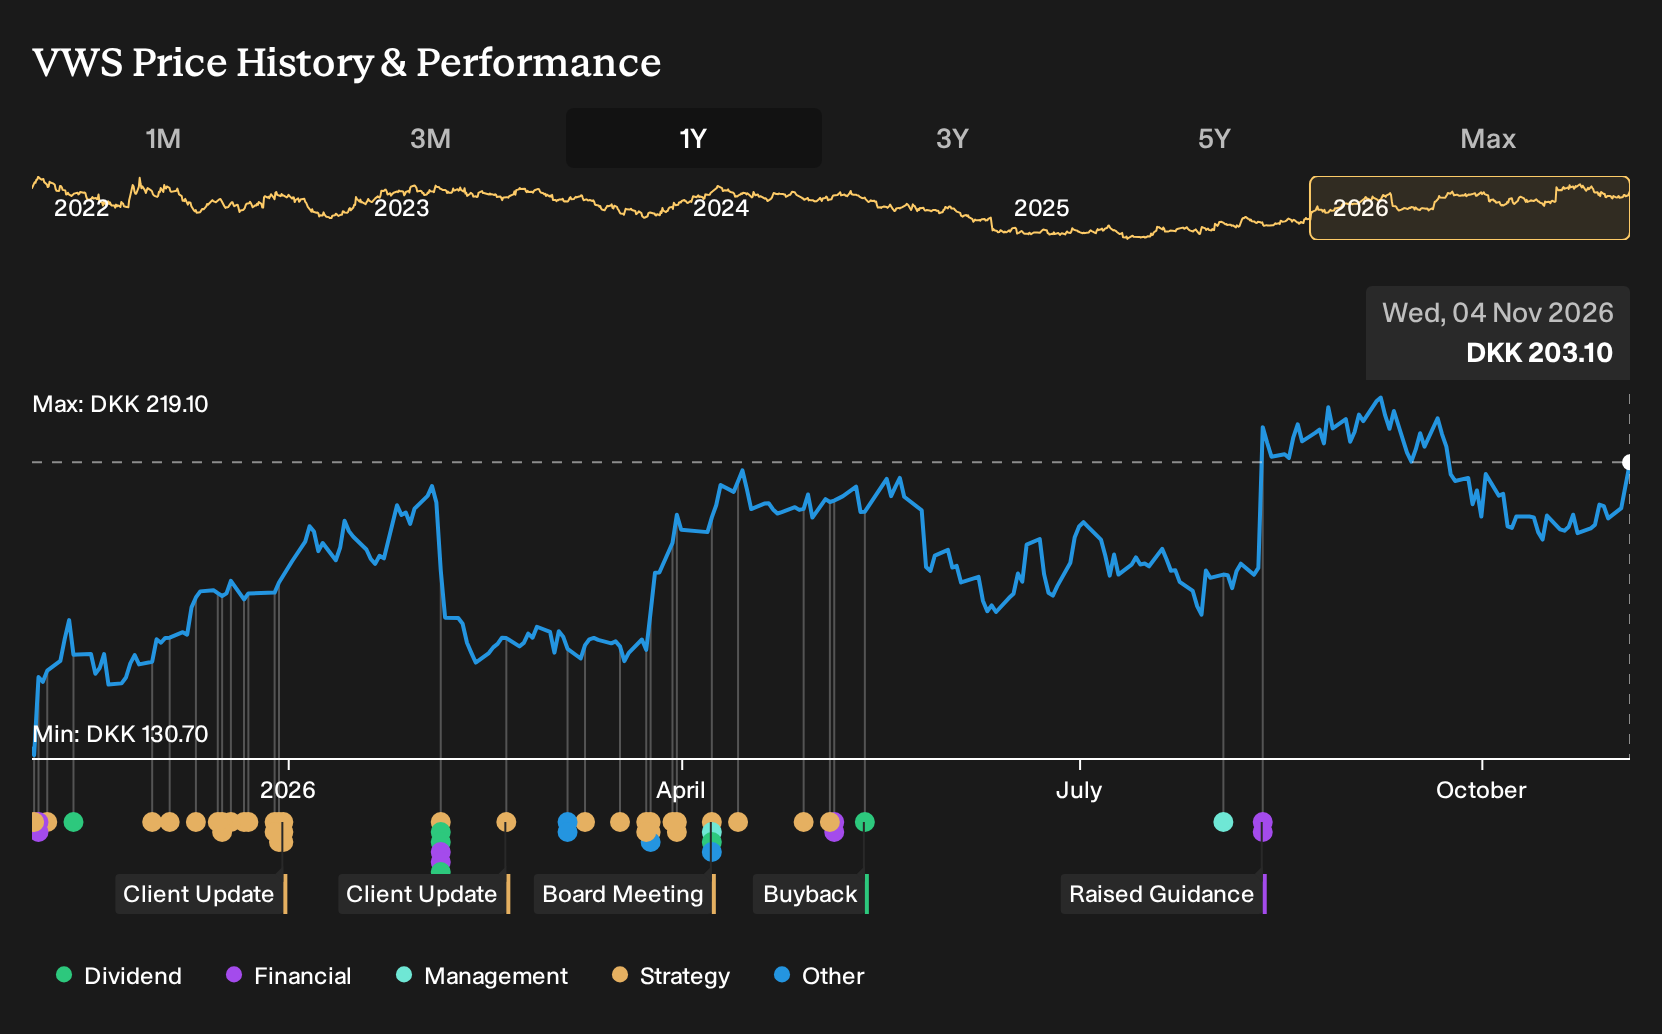
If you only glanced at early 2025 commentary on Vestas Wind Systems, you saw a split screen. One side focused on order momentum and policy support. The other warned about offshore losses, tariffs and pressure from Chinese rivals. Holding Vestas Wind Systems over the past year would have returned 35.9%, including dividends. If you had been weighing those arguments back on 4 November 2025, what did that contrast really signal about the business you were backing?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
This theme extends beyond Vestas Wind Systems. See which of 41 power grid technology and infrastructure stocks may still merit a closer look.
The Argument You Would Have Been Weighing Up On Vestas Wind Systems
The shares cost DKK132 at the start of the period, and investors in Vestas Wind Systems were essentially choosing between two sharply different stories about the future.
The bullish narrative put Fair Value at DKK141, 6% above the start price. It relied on an assumption that revenue could rise 7.6% a year over three years, supported by policy backing and a profit margin reaching 5.8%.
The bearish view anchored Fair Value at DKK60, 55% below the start price. That perspective focused on risks such as rising tariffs and ongoing offshore ramp-up expenses that could keep margins under pressure.
What The Results Changed For Vestas Wind Systems
Vestas Wind Systems raised full year profit guidance and announced a €400 million buyback after Q2 2026 revenue reached €4,723 million and net income came in at €280 million. Net margin moved to 5.9% from 0.9%, which leaned toward the optimistic thesis on profitability, even though earlier order volatility and offshore issues meant the evidence still cut both ways.
The whole episode turned on whether margin expansion would show up in audited numbers. For any other stock built on a similar story, it may be useful to track net margin alongside order news and see whether each results season changes that figure relative to the thesis.
What Vestas Wind Systems’ Price Now Asks You To Believe
Today Vestas Wind Systems trades at DKK203, up over the past year from DKK132. The selected Narrative’s Fair Value sits below that level, reflecting a view that the current quote already bakes in a smoother path than its risk checklist assumes.
This Narrative focuses on offshore technology issues, service profitability and the strain they could place on future capital returns. Anyone paying today’s price is effectively assuming Vestas Wind Systems can reach and defend higher EBIT margins. The question becomes how those offshore failure risks might challenge that path.
"The current valuation implies that Vestas Wind Systems is priced for a smooth path to double digit EBIT margins and sustained high capital returns that leave little room for earnings disappointments or offshore setbacks. Although Vestas Wind Systems is increasing offshore deliveries and reporting better manufacturing and installation efficiency, the recent blade failure at the He Dreiht project highlights that unresolved technology and execution risk could trigger additional remediation work, higher warranty usage and potential project penalties that weigh on EBIT margins and earnings."
The price and this Narrative do not agree. → Uncover what this Narrative says Vestas Wind Systems is actually worth
Go Straight To The Source
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 43% below our estimate - sells composite aircraft and mobility structures while pursuing efficiency gains to boost cash generation.
- Company 2 - 50% below our estimate - expands an asset light hotel network while layering on a fast growing retail platform.
- Company 3 - 39% below our estimate - builds digital platforms linking mortgage, housing and insurance providers to business and retail clients.
Three companies from the same screener. Open every one of the 195 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com