


EN
Fastly (FSLY) Q3 Earnings Put Its Valuation Story To The Test
Fastly (FSLY) just posted its third quarter 2026 numbers, giving investors fresh detail on revenue trends and profitability as the stock reflects earlier enthusiasm about improving business performance.
Fastly’s recent third quarter report, which showed higher sales and a smaller loss than a year earlier, lands after a sharp pullback in momentum. The 7 day share price return is down 18% and the 30 day share price return is also down 18%. This comes even though the year to date share price return is 106% and the 1 year total shareholder return is 91.8%, while the 5 year total shareholder return remains down 58%. The current price near US$21 suggests enthusiasm has cooled in the short run after a strong rebound, but the longer record still reflects past volatility.
Scan the rebound in Fastly alongside other fast-growing software and infrastructure plays by reviewing our curated 19 high quality undiscovered gems that have already started to draw market attention.
Fastly’s shares have swung from sharp gains over 12 months to a sudden pullback this month, which leaves a simple tension: Do the current fundamentals and cash flow expectations still justify fresh risk at around US$21?
Most Popular Narrative: 26% Undervalued
Fastly’s most followed valuation narrative pegs fair value around $28.55, comfortably above the latest close near $21.04. This puts today’s pullback up against a much richer long term story built on security, AI workloads and enterprise wins.
The acceleration of edge computing and AI related workloads is still in play and has moved on as Fastly rolls out AI Runtime Control, AI Firewall and API Enforcement on its edge platform. These offerings can add new usage based revenue streams on top of existing delivery contracts while supporting the company’s 2029 revenue range of US$1.1b to US$1.3b.
See why 34 investors see Fastly as 26% undervalued.
Result: Fair Value of $28.55 (UNDERVALUED)
Still, the Fastly story only holds if larger cloud rivals do not squeeze pricing too hard and if a handful of major enterprise customers continue to generate traffic.
Find out about the key risks to this Fastly narrative.
Another View: Fastly Looks Expensive On Sales
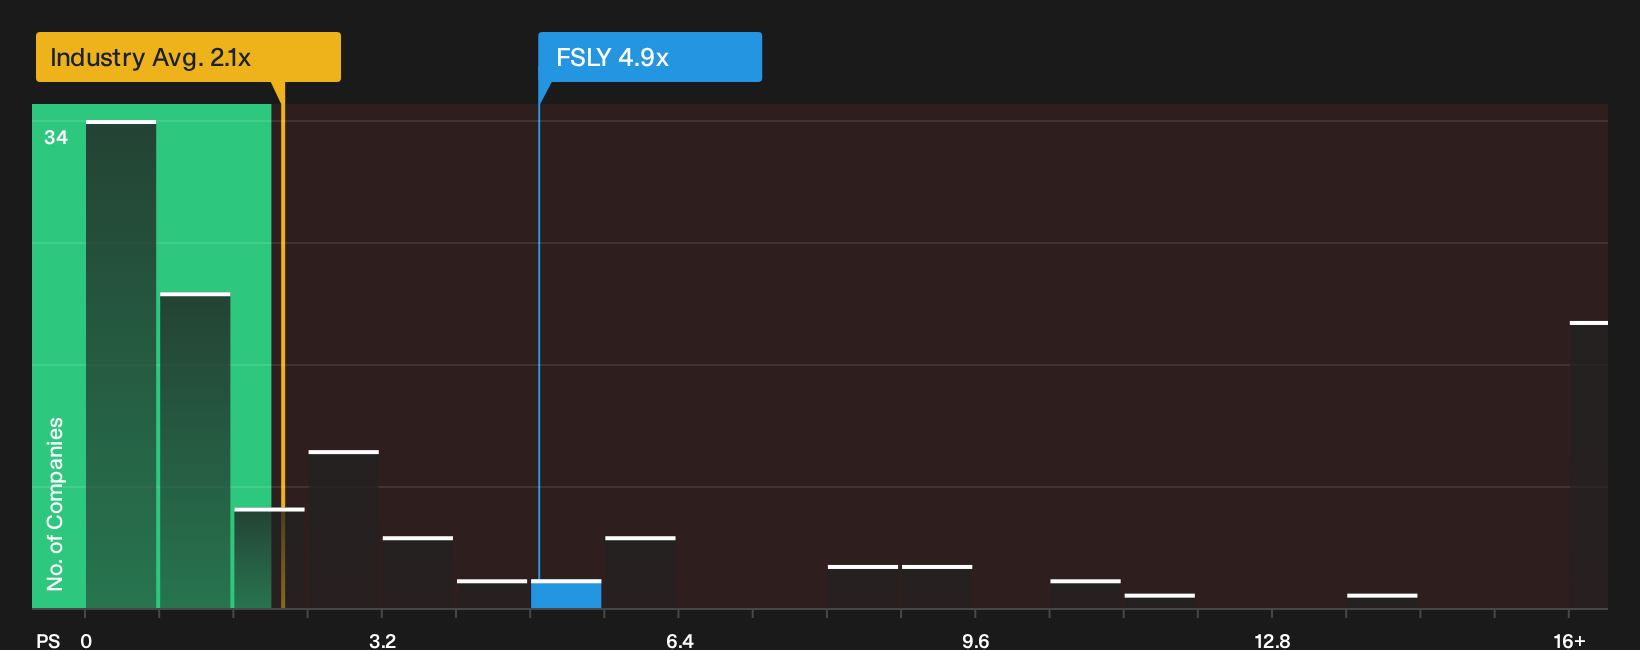
Fastly might appear 26% undervalued against the $28.55 fair value from the popular narrative, but its P/S ratio tells a different story. The stock trades at 4.9x sales versus a 2.1x US IT average and a 2x peer group, above a fair ratio of 4.1x. If the market leans back toward that fair ratio, how comfortable are you with the valuation risk at today’s price?
To see how that sales multiple stacks up against peers in more detail, including where the fair ratio sits over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Fastly’s valuation story and risk profile are exactly when you should move quickly, conduct your own stress test of the numbers, and then decide if the balance of 1 key reward and 3 important warning signs.
Looking for more Fastly-sized opportunities?
If Fastly has your attention, do not stop here. Broaden your watchlist with a few targeted idea lists that can surface fresh opportunities quickly.
- Target resilient cash generators by reviewing a list of solid balance sheet and fundamentals (24 results) that filters for sturdier finances when markets turn choppy.
- Hunt for mispriced quality by scanning a focused 35 high quality undervalued stocks that screens for strong fundamentals at more modest valuations.
- Balance potential and risk by checking a curated 7 elite penny stocks with strong financials that narrows the field to smaller companies with stronger financial markers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com