


EN
3 U.S. Defense Stocks Worth Watching As Missile Demand Stays Elevated
Geopolitics is suddenly front and center again, with missile stocks depleted, carriers shuffled between regions, and a possible Trump, Xi, Putin summit hanging over markets like a storm cloud. That kind of uncertainty often shifts where money flows, which can reward some defense related stocks and sideline others. This article walks through three U.S. contractors that screen as potential beneficiaries of the latest headlines and explains how their exposure to the news might matter for your portfolio.
The three contractors highlighted below are just a starting sample, since the full screen surfaced 39 more U.S. defense related businesses with equally compelling narratives that are not covered in this article. To identify and analyze those additional missile, naval, and munitions exposed stocks directly, go straight to the U.S. Defense Contractors screener.
Ducommun (DCO)
Ducommun plugs directly into the U.S. Defense Contractors theme, supplying the circuitry, structures, and engineering that keep missiles, aircraft, and space hardware in service. This is often where investors looking for real defense exposure start to pay attention.
Ducommun generates about US$492.9 million from Electronic Systems and US$372.1 million from Structural Systems, with a product mix anchored in defense and commercial aerospace platforms. The stock’s market value of roughly US$2.5b places it in the mid cap contractor bracket.
"Elevated global defense spending and the replenishment of missile and radar inventories, with Ducommun reporting its missile business up 68% year-on-year in Q2 2026 and missiles, radar and electronic warfare now over 20% of total revenue, points to ongoing program ramps that can support higher defense revenue and earnings over the next several years."
What happens to Ducommun’s earnings path if a single assumption about future defense program mix or pricing power breaks?
If that question is front of mind, read the full narrative for Ducommun to understand how Ducommun’s defense mix, pricing power and capital choices could be decoupling from headline risk.

Lyntris (LYNX)
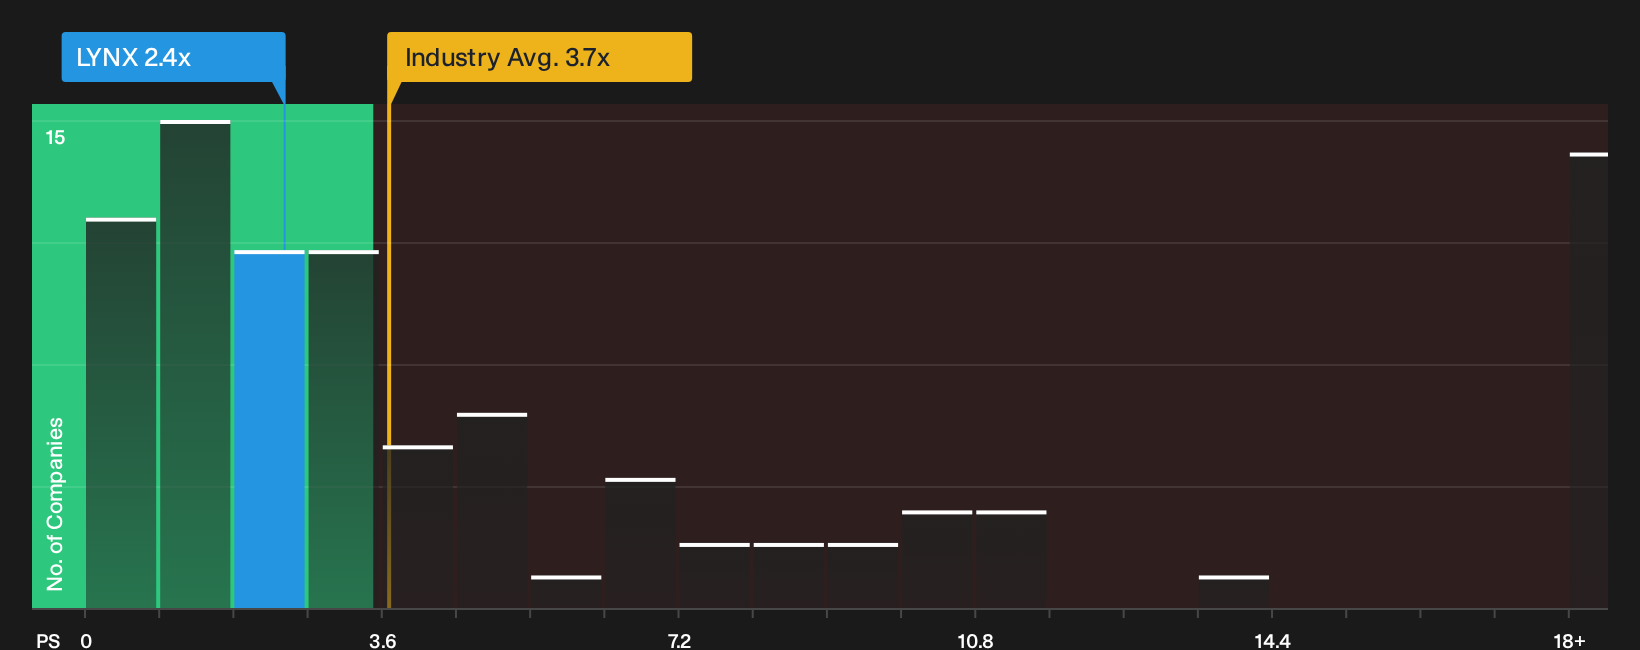
Lyntris is a pure-play defense technology stock built around battlespace connectivity, wiring together U.S. military communications and command and control across space, air, land, and sea. It generates about US$451 million from Aerospace & Defense and is valued at roughly US$1.3b.
For U.S. defense exposure that ties directly to communications and command systems rather than hardware, Lyntris is the purest expression of the screener theme. The stock trades on a relatively low P/S for this niche. This may matter if military demand for connected sensors keeps rising and one unresolved pressure on its path to sustainable profitability moves in the right direction.
That unresolved pressure is exactly what investors should quantify through the analysis report for Lyntris before Lyntris’ path to durable profitability is fully reflected in expectations.
Elmet Group (ELMT)
Elmet Group gives this defense contractor screen a different angle, because it sits further up the chain supplying the critical metals and high energy systems that missile and interceptor programs rely on. The business generates about US$196 million from Critical Materials and Components and US$32 million from Engineered Microwave Products, and the stock’s roughly US$613 million market cap keeps it very much in small cap territory.
Elmet Group manufactures refractory metal components and microwave systems that feed directly into aerospace, defense and government programs, which puts it close to the missile and advanced weapons focus of this screen.
"Rising global defense spending and replenishment needs in missile and interceptor programs such as PrSM, Patriot, Hellfire and Javelin are feeding into a larger ADG backlog. This ties Elmet Group more closely to higher margin defense content and supports gross margin and earnings."
What really matters now is how one pressure in this supply chain affects Elmet Group’s ability to turn that higher value defense work into lasting margin expansion.
That supply chain pressure is exactly what the full narrative for Elmet Group unpacks. It reveals where Elmet Group’s defense leverage might be quietly accelerating while headline risk keeps attention elsewhere.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Breakout momentum, dropping entry points, and under the radar stocks rarely stay quiet for long. Scan the next wave of opportunities and get in early.
- Spot income workhorses before yields get compressed by late money and lock onto the 5 dividend fortresses while it matters most.
- Track early-stage AI momentum before headlines catch up by zeroing in on curated 40 profitable AI stocks that aren't just burning cash already generating real cash instead of just burning it.
- Front run infrastructure demand linked to electrification trends by reviewing the hand picked 41 power grid technology and infrastructure stocks still flying under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com