


EN
Dorian LPG Ltd. (NYSE:LPG) Passed Our Checks, And It's About To Pay A US$1.25 Dividend
Some investors rely on dividends for growing their wealth, and if you're one of those dividend sleuths, you might be intrigued to know that Dorian LPG Ltd. (NYSE:LPG) is about to go ex-dividend in just 3 days. The ex-dividend date is one business day before the record date, which is the cut-off date for shareholders to be present on the company's books to be eligible for a dividend payment. The ex-dividend date is important because any transaction on a stock needs to have been settled before the record date in order to be eligible for a dividend. Meaning, you will need to purchase DorianG's shares before the 9th of November to receive the dividend, which will be paid on the 24th of November.
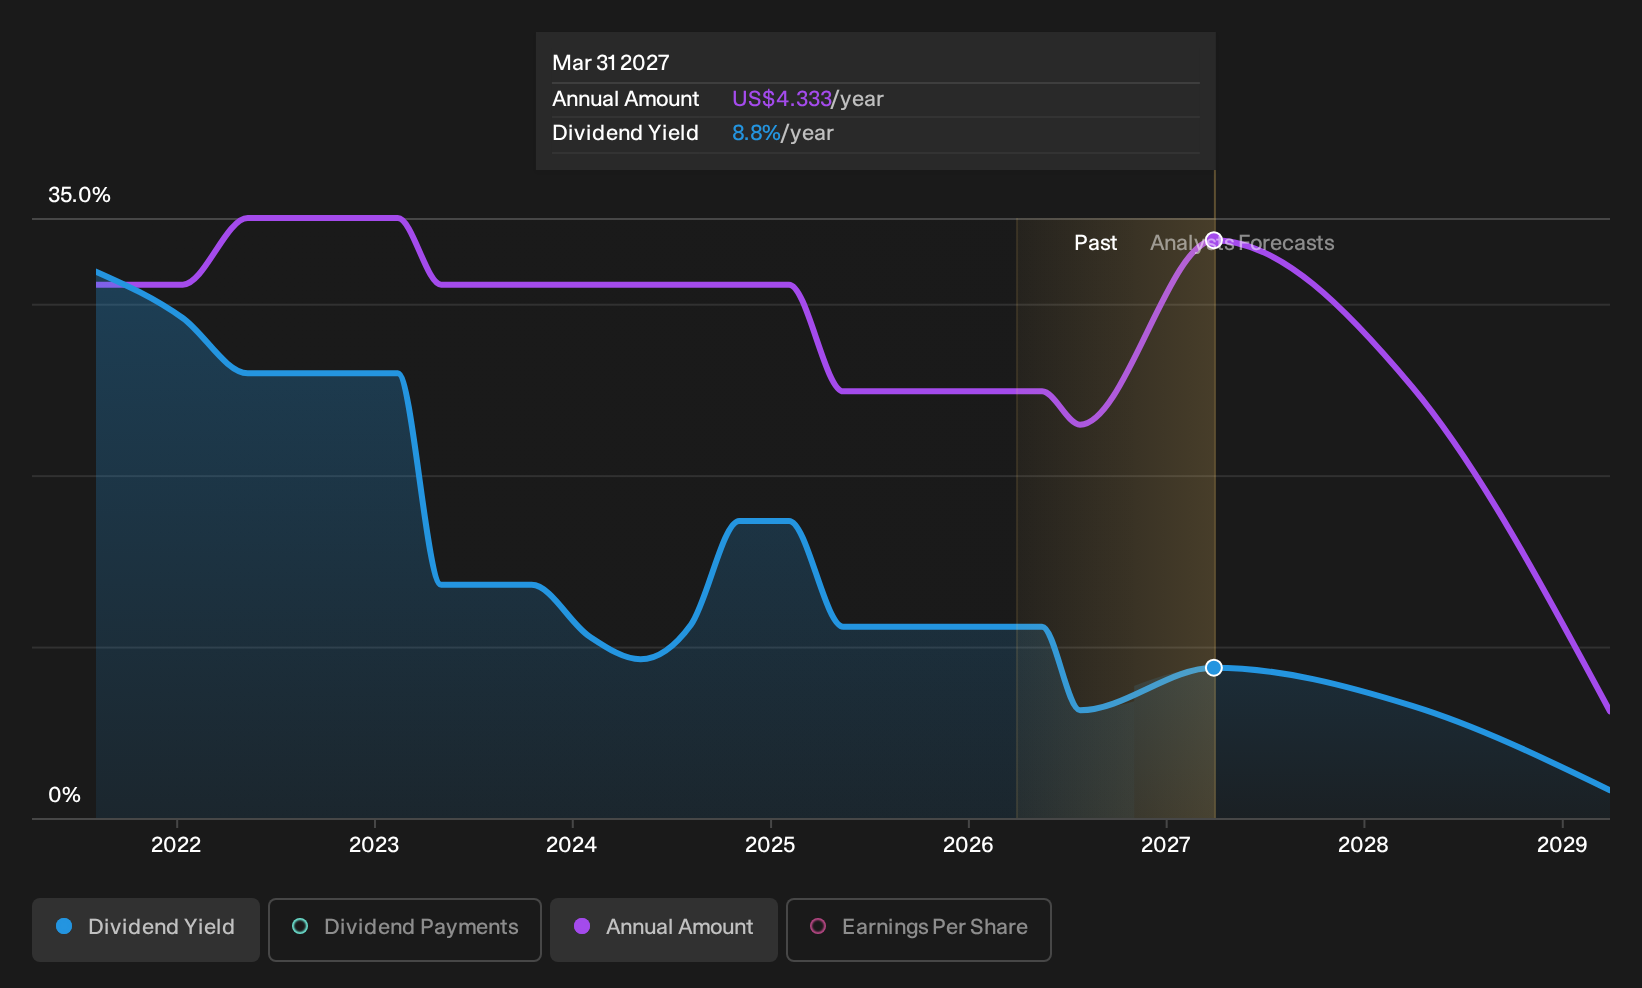
The company's next dividend payment will be US$1.25 per share. Last year, in total, the company distributed US$2.95 to shareholders. Calculating the last year's worth of payments shows that DorianG has a trailing yield of 6.0% on the current share price of US$49.43. Dividends are a major contributor to investment returns for long term holders, but only if the dividend continues to be paid. As a result, readers should always check whether DorianG has been able to grow its dividends, or if the dividend might be cut.
Dividends are usually paid out of company profits, so if a company pays out more than it earned then its dividend is usually at greater risk of being cut. Fortunately DorianG's payout ratio is modest, at just 44% of profit. That said, even highly profitable companies sometimes might not generate enough cash to pay the dividend, which is why we should always check if the dividend is covered by cash flow. It paid out 85% of its free cash flow as dividends, which is within usual limits but will limit the company's ability to lift the dividend if there's no growth.
It's positive to see that DorianG's dividend is covered by both profits and cash flow, since this is generally a sign that the dividend is sustainable, and a lower payout ratio usually suggests a greater margin of safety before the dividend gets cut.
View our latest analysis for DorianG
Click here to see the company's payout ratio, plus analyst estimates of its future dividends.
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. If earnings fall far enough, the company could be forced to cut its dividend. That's why it's comforting to see DorianG's earnings have been skyrocketing, up 32% per annum for the past five years.
Another key way to measure a company's dividend prospects is by measuring its historical rate of dividend growth. DorianG has seen its dividend decline 5.9% per annum on average over the past five years, which is not great to see. DorianG is a rare case where dividends have been decreasing at the same time as earnings per share have been improving. It's unusual to see, and could point to unstable conditions in the core business, or more rarely an intensified focus on reinvesting profits.
Final Takeaway
Is DorianG worth buying for its dividend? From a dividend perspective, we're encouraged to see that earnings per share have been growing, the company is paying out less than half of its earnings, and a bit over half its free cash flow. It's a promising combination that should mark this company worthy of closer attention.
On that note, you'll want to research what risks DorianG is facing. Every company has risks, and we've spotted 3 warning signs for DorianG (of which 1 can't be ignored!) you should know about.
A common investing mistake is buying the first interesting stock you see. Here you can find a full list of high-yield dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.