


EN
How Investors May Respond To Reinsurance Group Of America Stock Ahead Of Earnings
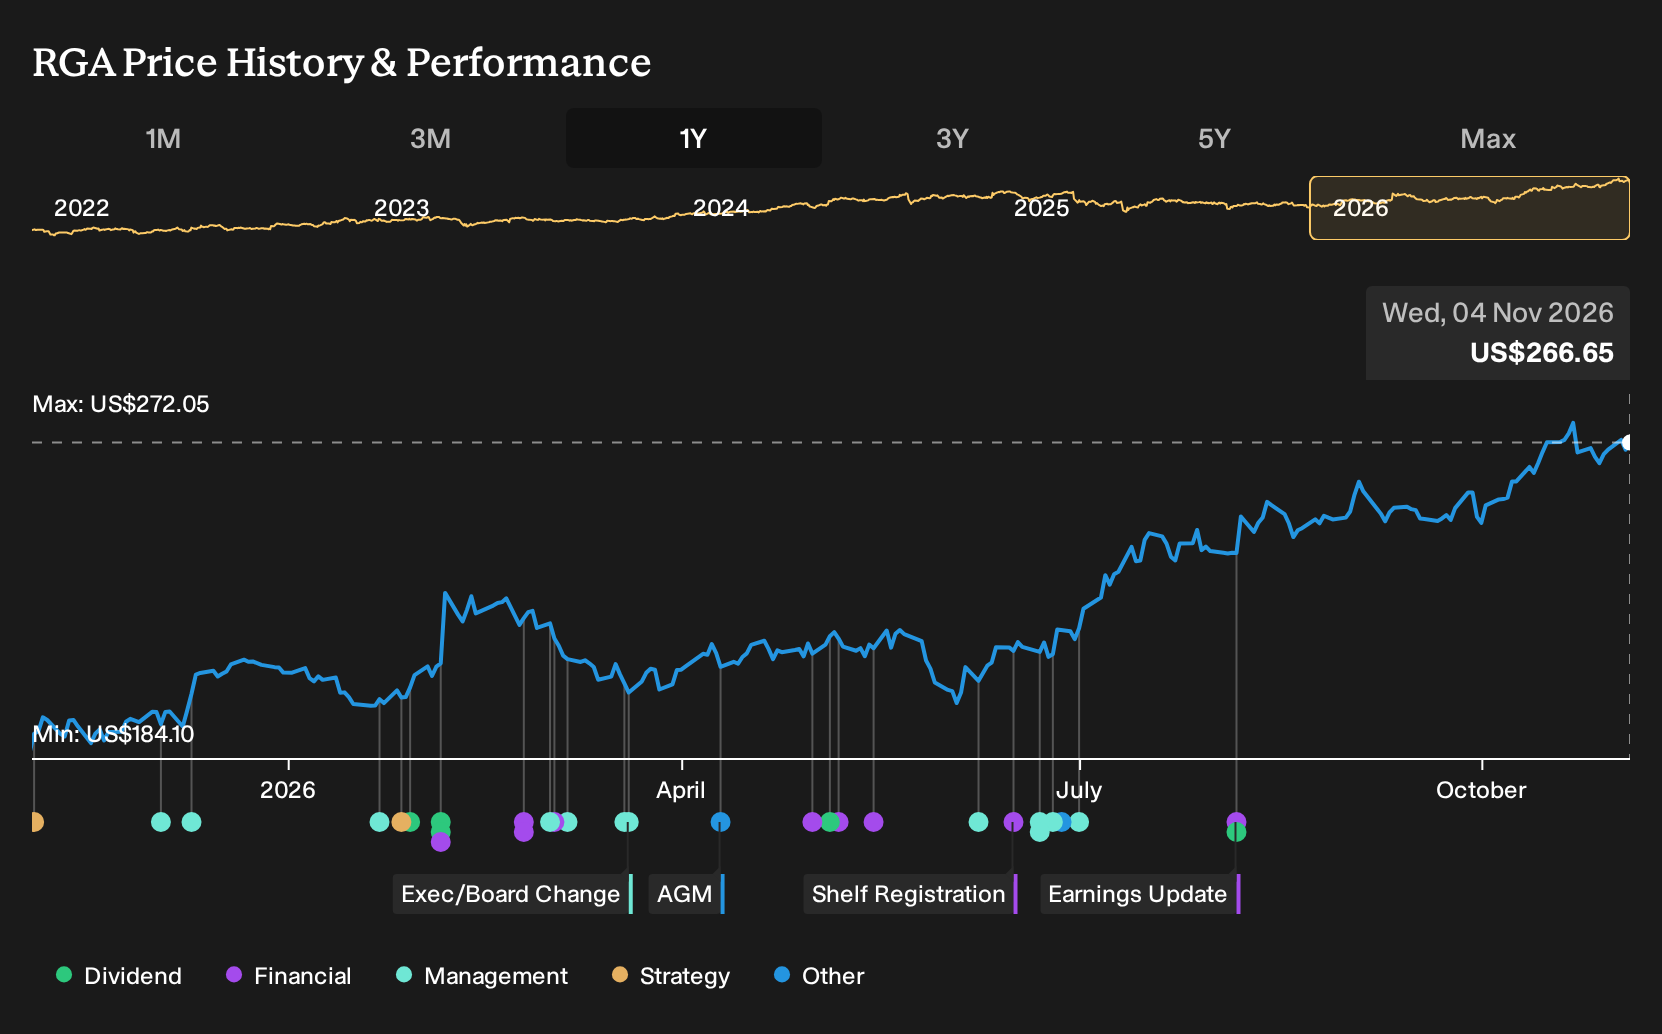
- Reinsurance Group of America is heading into its next earnings release with consensus forecasts of $6.98 EPS and $6.62b in quarterly revenue, both higher than the figures reported for the same period last year.
- The upward 0.4% revision to EPS estimates over the past month points to rising expectations for near term profitability and operating momentum at Reinsurance Group of America.
- We will now look at how Reinsurance Group of America’s investment narrative could be influenced by these firmer quarterly earnings expectations.
Compare Reinsurance Group of America's setup ahead of earnings with other financially resilient opportunities by scanning our hand picked 31 resilient stocks with low risk scores.
Reinsurance Group of America Investment Narrative Recap
To own Reinsurance Group of America, you need to be comfortable with a life and health reinsurer that leans heavily on biometric risk expertise, international expansion and capital hungry deals. The near term story revolves around whether core underwriting and investment income can keep supporting earnings quality while pension risk transfer volumes in the U.S. and U.K. remain subdued.
The upcoming quarter is the key checkpoint. Consensus points to higher EPS and revenue, yet the more immediate swing factor is how management balances growth opportunities against slow pension flows and complex liabilities. If pension activity stays muted, the short term impact on the broader investment narrative looks manageable rather than transformational.
The most relevant reference point for this earnings setup is the recent focus on expected quarterly EPS of US$6.98 and revenue of US$6.62b, both above the same period last year. That backdrop puts execution under a brighter spotlight, because Reinsurance Group of America is already carrying expectations for mid single digit revenue growth and improving margins over time.
For you as an investor, the link to catalysts is straightforward. Strong delivery around that US$6.98 EPS mark would support the idea that digital underwriting programs, Asia Pacific new business and efficient capital deployment are feeding through to the income statement. Any stumble, especially if tied to slower pension risk transfer or weaker profitability in biometric heavy deals, would raise questions about how quickly those longer term drivers can show up in reported results.
Reinsurance Group of America's narrative projects revenue of US$30.9b and earnings of US$2.1b by 2029. This setup assumes 6.0% yearly revenue growth and an earnings increase of about US$600m from current earnings of US$1.5b.
Uncover how Reinsurance Group of America's fair value indicates a 4% potential upside to its current price before the market closes the discount.
Exploring Other Perspectives
Some of the lowest ranked analysts frame Reinsurance Group of America through the risk of a longer pension risk transfer slump rather than the upside of Asia or digital underwriting. They were working off 2029 earnings of about US$2.0b on roughly US$30.8b of revenue. That is a more cautious setup. Use this earnings release to evaluate which narrative you find more convincing.
Explore 3 other Reinsurance Group of America fair value estimates, including one that suggests it could be worth just $277.33.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Reinsurance Group of America research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Reinsurance Group of America. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Reinsurance Group of America's overall financial health at a glance.
Looking for more Reinsurance Group of America style investment ideas?
If the setup around Reinsurance Group of America has sharpened your thinking, use that same checklist to scan a wider field of companies. Let the Simply Wall St Screener help you find other opportunities that fit the balance of quality, risk and income you are looking for.
- For investors who want potential upside without stretching quality too far, take a look at 19 high quality undiscovered gems that may not yet be crowded with attention.
- If capital protection and robust fundamentals sit at the top of your priorities, filter the market using our list of solid balance sheet and fundamentals (24 results) to see which businesses match that profile.
- For those aiming to build a more income focused portfolio, scan the 5 dividend fortresses and see which higher yielding companies align with your risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com