


EN
TransAlta (TSX:TA) Stock May Trade At A Premium On Portfolio Rotation News
TransAlta has delivered a 73.1% share price gain over the past three years, yet the bigger question for you today is whether that move still lines up with what the company earns. With the stock recently closing at $18.57 and the business actively reshaping its asset mix, the focus now shifts to what that price implies about its earnings power.
- The 73.1% return over three years puts meaningful expectations into the current share price, which makes the link between TransAlta’s earnings and that performance worth scrutinising.
- The sale of a 49% interest in the Oklahoma wind portfolio and the purchase of Colorado gas assets rework the generation mix, which can influence margins, cash flow timing and the earnings base that investors are paying for.
- The analysts covering TransAlta have run their own numbers. See what analysts think TransAlta's shares could be worth.
The issue now is whether the earnings that TransAlta generates today, and may reasonably sustain, are enough to justify the current share price on this basis.
If you like testing whether a price move is backed by earnings, it can help to benchmark TransAlta against a wider field using a focused screen of 41 power grid technology and infrastructure stocks
Has TransAlta Run Too Far on Earnings?
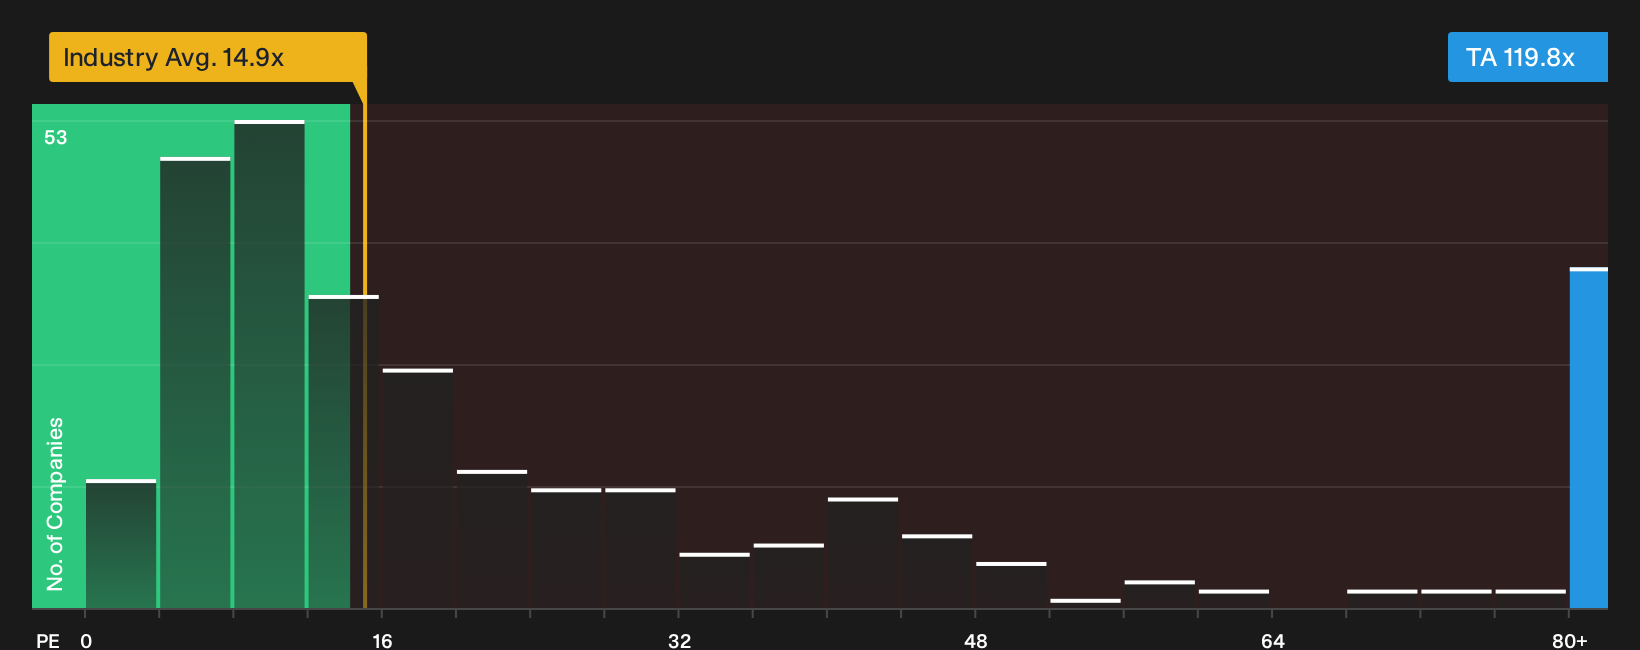
The P/E ratio suits TransAlta because earnings remain a key anchor for how investors judge a capital intensive power producer. On that yardstick, the stock trades on roughly 119.8x, far above the Renewable Energy sector average of about 14.9x. Against a broader peer group that clusters closer to 33.2x, the gap is wide there too.
On this framework, the tailored fair multiple that blends TransAlta’s risk profile, profitability and growth assumptions sits well below the current P/E. This points to the shares screening overvalued on earnings. Despite the recent Oklahoma wind sale and Colorado gas purchase giving the portfolio more contracted cash flow, the present ratio still prices TransAlta on a far richer earnings tag than both its sector and peers suggest. Explore the numbers behind TransAlta's P/E valuation.
The TransAlta Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for TransAlta pick up where this valuation puzzle leaves off. They spell out what sort of growth, margins and earnings profile would need to unfold for the current market price to look either stretched or conservative, and each one effectively ties a fair value to a particular storyline about TransAlta's potential catalysts and risks. This makes it easier to track over time which version of events appears closer to reality on the Community page.
Community views on TransAlta are split between those leaning into the contracted growth story and those worried that weak Alberta pricing already limits the upside.
Bull case: 21% undervalued
"TransAlta’s program to acquire and recycle assets into longer term contracted positions, as seen in the C$1 billion Colorado peaking acquisition with 25 to 30 year contracts and the contracted Far North assets in Ontario, is gradually increasing portfolio contractedness and average contract life, which can stabilize revenue and reduce earnings volatility…"
Discover why this Narrative puts TransAlta at 21% undervalued.
Bear case: 15% overvalued
"Although TransAlta is working to position underutilized Alberta gas-fired steam units for new AI and data center demand, the recent Alberta spot prices in the low C$30s per MWh suggest that if this load arrives more slowly than anticipated these assets could remain underused…"
Explore why this Narrative puts TransAlta at 15% overvalued.
One more crucial angle on TransAlta that the market is already watching
Everything so far has focused on what TransAlta looks like today. Analyst models outline where they expect this business to be a few years from now and provide a fresh yardstick to compare with the current valuation. Explore where analysts expect TransAlta to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com