


EN
Is Wingstop (WING) Fully Priced On Its Q3 Earnings Beat And 2026 Guidance?
Wingstop (WING) just packed several signals into one week, combining a quarterly dividend decision, fresh 2026 guidance, and third quarter results that beat profit forecasts but came in light on revenue.
Wingstop’s latest updates landed after a sharp rebound in the share price, with a 56.9% 1 month share price return and a 43.7% 3 month share price return helping offset a year to date share price decline of 34.7% and a 1 year total shareholder return decline of 33.2%. This suggests sentiment has recently warmed even as longer term holders are still in modestly positive territory over five years.
Compare Wingstop's rebound and guidance with other consumer-focused stocks that have also packed strong catalysts into recent weeks by scanning our curated list of 19 high quality undiscovered gems.
After a 1 month surge and only a modest discount to recent analyst targets, the key tension for Wingstop now is simple: Is most of the recovery already priced in, or does valuation still leave room ahead?
Most Popular Narrative: 11% Undervalued
Wingstop’s most followed narrative places fair value at about $187.92, above the last close at $167.62. This puts recent gains in a sharper context for anyone weighing what still might be implied in the price.
The current global development pipeline of more than 2,200 committed restaurants, alongside 15% to 16% unit growth guidance and domestic AUVs around US$2 million on roughly US$580,000 build costs, points to continued mix shift toward royalty and franchise fee income. This can support growth in high margin revenue and earnings even when domestic traffic is under pressure.
See why 28 investors see Wingstop as 11% undervalued.
Result: Fair Value of $187.92 (UNDERVALUED)
Still, that 7.5% drop in Q2 2026 domestic same store sales and softer traffic from pressured lower income guests could easily rewrite the Wingstop upside story.
Find out about the key risks to this Wingstop narrative.
Another View: Wingstop Through A Cash Flow Lens
The earlier fair value of $187.92 leans on analyst earnings forecasts and multiples. A second approach, the SWS DCF model, points in the opposite direction. On this view, Wingstop at $167.62 trades above an estimated future cash flow value of $144.08, which suggests less upside and more downside risk if cash generation disappoints.
For readers who want to see how this cash flow view is built line by line, our SWS DCF model is unpacked in detail in Look into how the SWS DCF model arrives at its fair value.
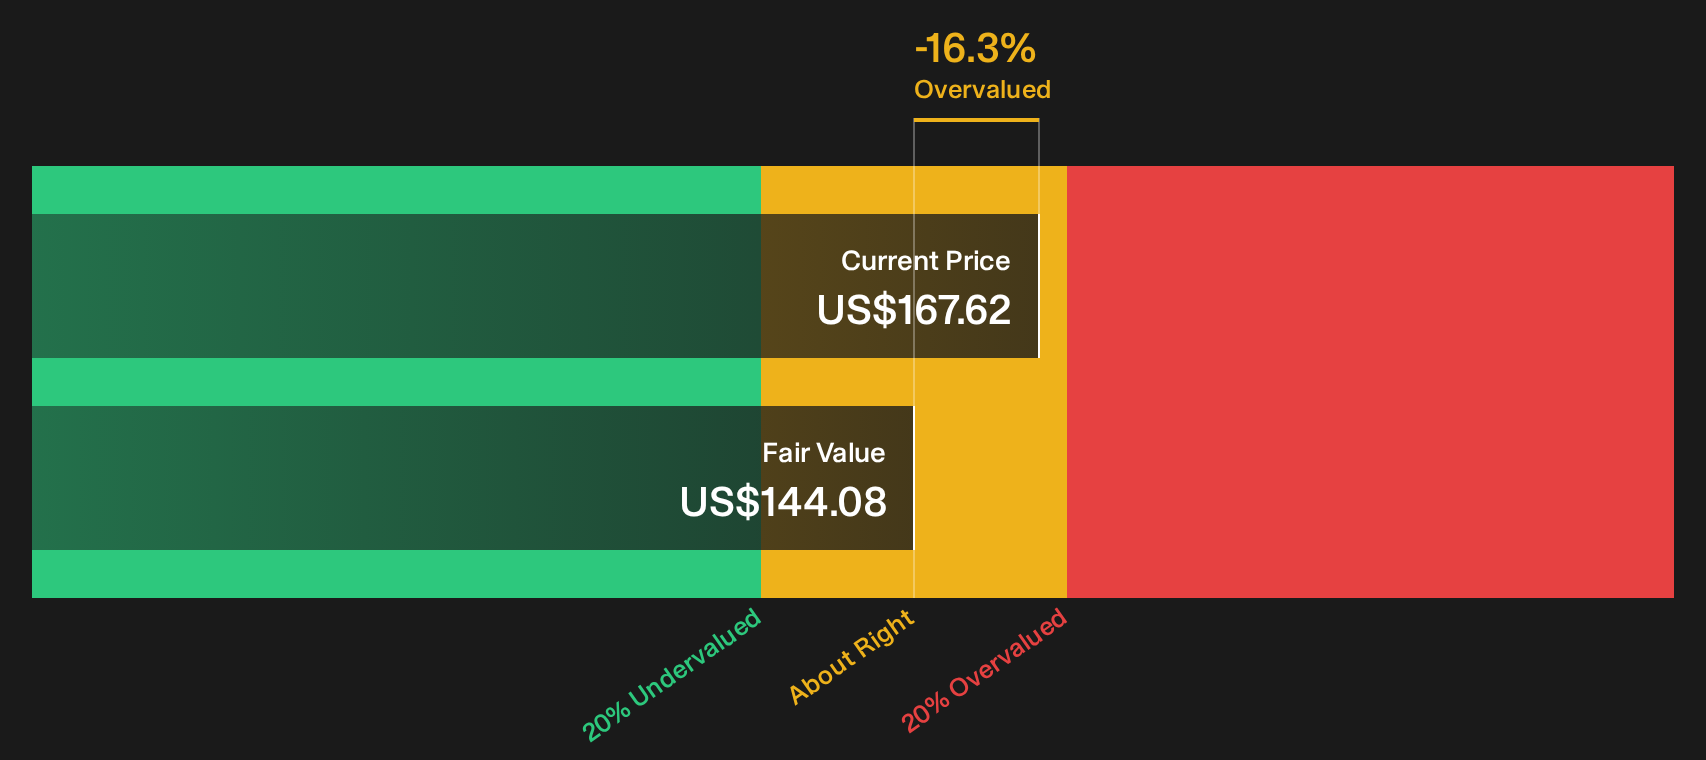
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Wingstop for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the recent Wingstop headlines, with both risks and rewards in play, make this a moment to check the numbers yourself and move quickly. To weigh those cross currents for your own portfolio, start with the 1 key reward and 3 important warning signs.
Looking for more Wingstop sized investment ideas?
If Wingstop has you thinking about what else might be hiding in plain sight, use this moment to widen your watchlist before the next move passes you by.
- Target long term compounding potential by reviewing companies that pair quality fundamentals with appealing pricing through the 35 high quality undervalued stocks.
- Prioritise resilience and capital protection by scanning businesses that earn strong marks on financial strength with the list of solid balance sheet and fundamentals (24 results).
- Hunt for overlooked opportunities with healthy fundamentals by running a focused search across the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com