


EN
Halozyme Therapeutics (HALO) Could Be 14% Undervalued As Earnings Estimates Rise
Halozyme Therapeutics (HALO) heads into its Q3 2026 earnings release and call on November 5 after the market close, with attention centered on forecast gains in royalties and product sales.
Recent price action has been strong, with Halozyme Therapeutics delivering a 20.34% 1 month share price return and a 51.98% 3 month share price return. The 1 year total shareholder return of 90.83% suggests that momentum has been building rather than fading.
Scan other potential breakouts by comparing Halozyme Therapeutics with a curated list of quality companies showing strong momentum in royalties, product revenue and earnings upgrades through the 35 high quality undervalued stocks
After a move like Halozyme Therapeutics has just posted, the question comes straight at you. Should you lean into the momentum now, or wait and see if the upcoming earnings and current valuation terms offer a cleaner entry point?
Most Popular Narrative: 14% Undervalued
Against a last close of $130.34, the most followed valuation narrative for Halozyme Therapeutics points to a fair value of $151.83. This frames the recent share price surge as only part of the story rather than the whole move.
Most investors view Halozyme Therapeutics through a single lens: ENHANZE®. That perception made sense several years ago, when ENHANZE® was the company's primary growth engine and the overwhelming source of value. Today, however, management's vision appears far broader. Halozyme is no longer building around one platform. It is attempting to create a portfolio of drug-delivery technologies that could eventually support multiple royalty streams across different therapeutic modalities.
See why 4 investors see Halozyme Therapeutics as 14% undervalued.
Result: Fair Value of $151.83 (UNDERVALUED)
Still, a setback for ENHANZE or Hypercon royalties, or slower uptake from partners, could quickly challenge the idea that Halozyme Therapeutics is misunderstood.
Find out about the key risks to this Halozyme Therapeutics narrative.
Another View On Halozyme Therapeutics
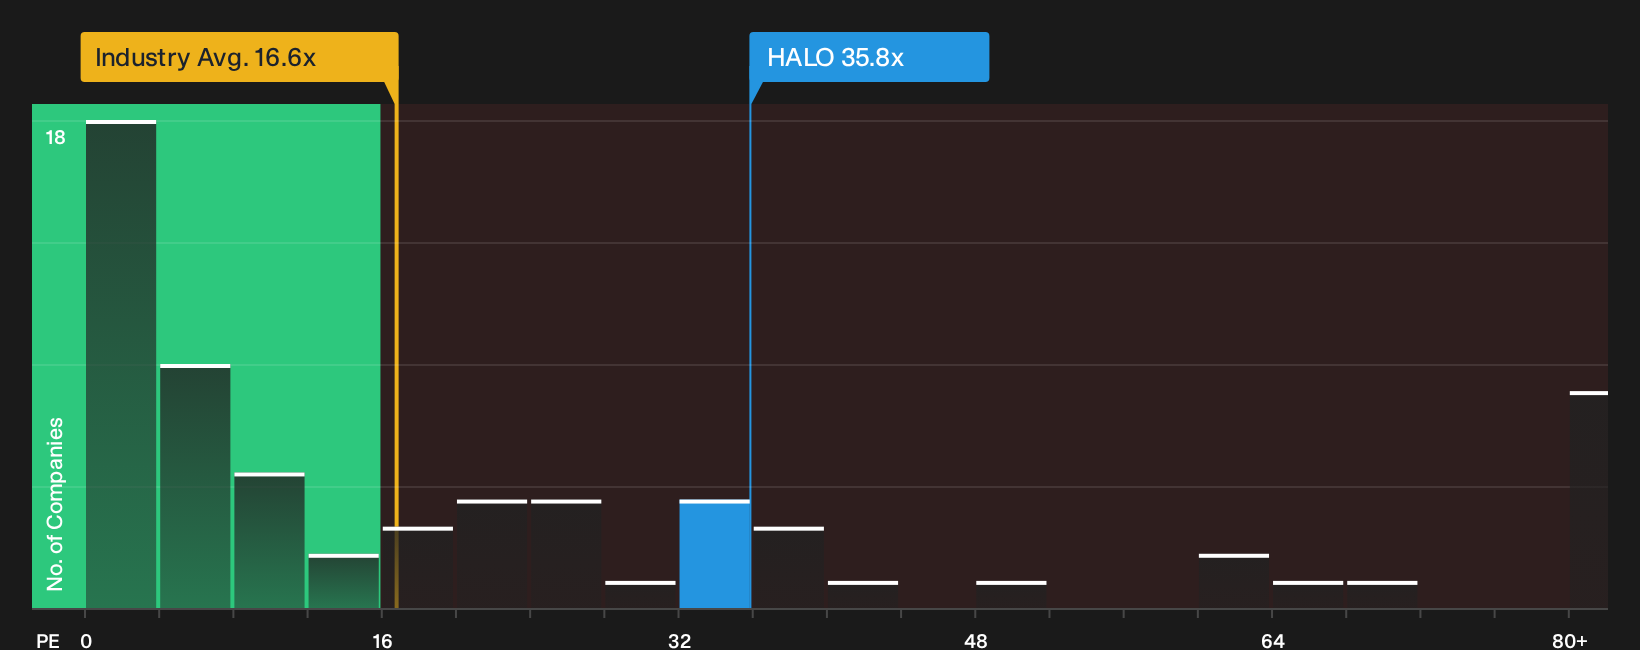
A different lens on Halozyme Therapeutics comes from its P/E ratio. The stock trades at 35.8x earnings, compared with a fair ratio estimate of 23.3x, the US Biotechs group at 16.6x and peer average of 28.6x. That gap points to valuation risk if sentiment cools or growth expectations reset.
For a closer look at how this earnings-based yardstick stacks up against the current price, review the See what the numbers say about this price — find out in our valuation breakdown.
For a visual sense of how Halozyme compares with sector pricing, see the latest
Next Steps
Feeling torn between the excitement around Halozyme Therapeutics and the concerns raised in the valuation work is normal. Act while the details are fresh and weigh both sides of the story by reviewing the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Halozyme Therapeutics?
Do not stop with one opportunity. Broaden your watchlist with a few focused screens that surface different types of potential setups across the market.
- Spot potential value opportunities early by scanning the 35 high quality undervalued stocks to find companies that pair quality fundamentals with pricing that still looks reasonable.
- Prioritise resilience and sleep better at night by reviewing the 31 resilient stocks with low risk scores to see companies with stronger risk profiles.
- Hunt for lesser-known potential opportunities before the crowd catches on by checking the 19 high quality undiscovered gems to identify companies that combine solid financials with lower visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com