


EN
Earnings Reset Change The Bull Case For Acerinox (BME:ACX)?
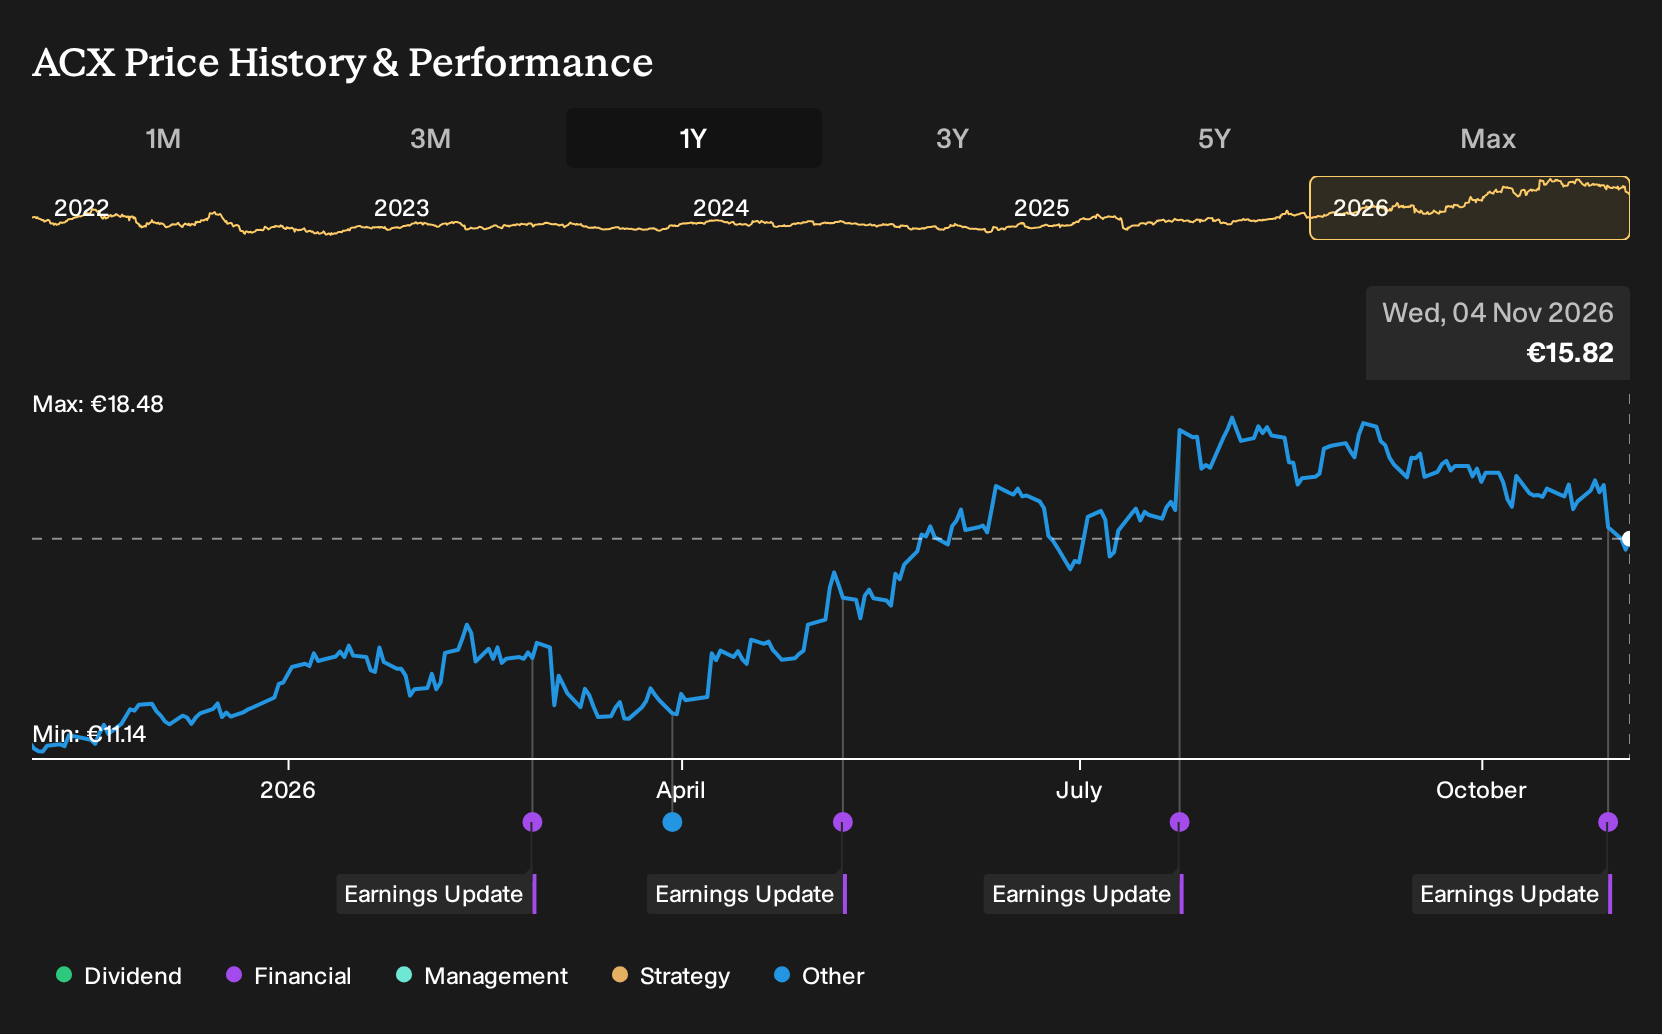
- Acerinox reported third quarter 2026 sales of €1,591 million and net income of €85 million, with nine month sales of €4,556 million and net income of €162 million, all higher than the same periods in 2025.
- The sharp shift in profitability, from single digit euro net income in the first nine months of 2025 to triple digit millions in 2026, highlights how Acerinox’s operating leverage and product mix can affect earnings when volumes and pricing conditions improve together.
- The next area of attention will be how Acerinox’s stronger net income profile may reshape the investment narrative built around efficiency and alloys.
Scan how Acerinox’s earnings reset compares with peers by reviewing our curated list of 195 high quality undervalued stocks, which pairs stronger cash generation with disciplined balance sheets.
Acerinox Investment Narrative Recap
Acerinox appeals most to shareholders who buy into a simple idea. The group is trying to turn higher value stainless and high performance alloys, plus efficiency programs, into sturdier earnings through the cycle. The latest quarter, with €85 million profit on €1,591 million sales, supports that the operating model can convert slightly better pricing and volumes into a much cleaner income statement.
The short term swing factor is still demand recovery in U.S. stainless and European alloys as new NAS capacity and capex come on stream. The biggest risk remains that subdued consumption and high project exposure in energy and process industries collide with elevated investment and leverage, which would keep utilization, margins and cash generation under pressure.
The most relevant fresh datapoint is the nine month 2026 result. Sales of €4,556 million and net income of €162 million compare with €4,473 million and €7 million a year earlier, showing how sharply the income line can move when the product mix and pricing backdrop improve at the same time.
For you as an investor, these figures plug directly into the existing catalysts around NAS expansion, the Beyond Excellence efficiency program and the high performance alloys platform. The higher earnings base gives Acerinox more room to service roughly €1.27 billion of net debt and to keep funding capex, while any setback in end market activity or project timing would quickly test that improved headroom.
Acerinox's current analyst narrative points to revenues of €7.7 billion and earnings of €495.9 million by 2029, based on projections of 10.5% yearly revenue growth and an earnings increase of about €441.8 million from €54.1 million today.
Uncover why Acerinox's fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into the bullish capacity story. Before this earnings beat, the most optimistic analysts were already pencilling in €8.7b of revenue and €649.8m of earnings by 2029, supported by NAS and HPA expansion. You can now compare those upbeat forecasts with the latest Acerinox results and decide which narrative feels closer to your own expectations.
Explore another Acerinox fair value estimate, including one that suggests potential upside of up to 36% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Acerinox research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Acerinox. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Acerinox's overall financial health at a glance.
Looking For More Ideas Beyond Acerinox?
Once you have a view on Acerinox, it can help to set it alongside other opportunities that fit different portfolio roles. The Simply Wall St Screener lets you compare businesses on the factors that matter most to you, from resilience to income potential.
- If capital preservation comes first for you, start with a focus on resilience and risk by screening for 222 resilient stocks with low risk scores that may help anchor your portfolio.
- For investors who care most about financial strength, broaden your watchlist with a list of solid balance sheet and fundamentals (196 results) and see which companies pair prudent leverage with healthier fundamentals.
- If you want to hunt for potential future leaders before the crowd catches on, scan a targeted 602 high quality undiscovered gems that already show robust fundamentals but receive less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com