


EN
Unity (U) Stock May Look Fully Priced Despite New Financing Partnership
Unity Software has seen its share price move around sharply over the past few years, and the latest swings put fresh focus on a simple question for you as an investor. Is the current US$42.46 price supported by what the company is generating in sales, or is the market leaning too hard on the story around the business?
- Over the last 5 years the stock has fallen 75.9%, which puts a lot of weight on whether today’s valuation can still be explained by its revenue base.
- The new user acquisition financing partnership with PvX may support expectations for future game developer activity on Unity’s platform, which feeds directly into how much investors are willing to pay for each dollar of sales.
- Your read on Unity Software is one view; the desks covering it have another. See what analysts think Unity Software's shares could be worth.
The issue now is whether the price investors see on screen is in line with what Unity Software is generating in sales today and what the market expects from that revenue line ahead.
If you are weighing Unity Software against other ways to pay for top line potential rather than current earnings, it can help to compare it with 35 high quality undervalued stocks.
Has Unity Software Run Too Far on Sales?
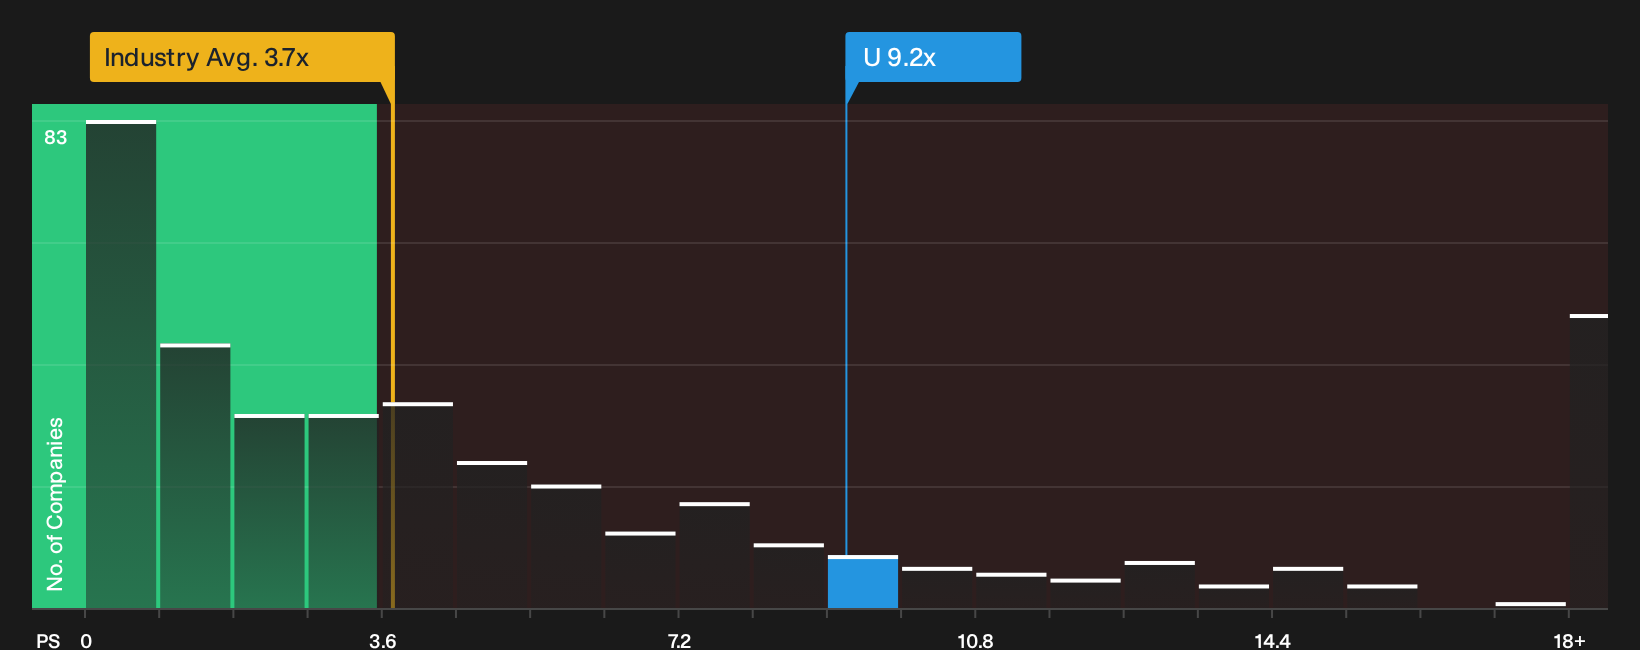
P/S works better than P/E for Unity Software right now because the market is clearly anchoring more on revenue than on current earnings. At about 9.2x P/S, the stock trades well above the broader Software industry level of roughly 3.7x. It also prices in a sizeable premium to closer peers, which are around 5.5x on average.
The tailored fair multiple implied by the valuation model sits below the current 9.2x P/S, so this framework flags Unity Software as overvalued on sales. The recent PvX financing partnership may help explain why investors accept a richer revenue multiple, since it speaks directly to activity on Unity’s platform, yet the price still assumes you are willing to pay more per dollar of sales than both the sector and peer group. Explore the numbers behind Unity Software's P/S valuation.
The Unity Software Narrative: What Would Justify Today's Price?
Unity Software's valuation puzzle only really makes sense once you spell out the future paths that would justify a higher or lower price, which is where Simply Wall St Narratives come in on the Community page. Each narrative ties its number to a specific view on how Unity Software's growth, profitability and risk profile could evolve, giving you a reference point you can revisit as fresh results and news update the picture.
Community views on Unity Software pull in opposite directions, with one group leaning into the Vector upside and another focused on concentration and valuation risk.
Bull case: 16% undervalued
"The main priority is Unity’s shift from legacy ad network and publishing revenue toward higher-margin, AI-native Vector and related data products…"
Discover why this Narrative puts Unity Software at 16% undervalued.
Bear case: 290% overvalued
"So the bull narrative is defensible, not a bargain, it is a bet that Vector's momentum is durable and not partly borrowed from a rival's data…"
Explore why this Narrative puts Unity Software at 290% overvalued.
One more Unity Software check that belongs next to the price tag
Share price and sales multiples only tell part of the story, because who is steering Unity Software and how those leaders are rewarded can heavily influence what happens next. See who runs Unity Software and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com