


EN
Are Wall Street Analysts Bullish on Mosaic Stock?
The Mosaic Company (MOS) is a global fertilizer producer and marketer headquartered in Tampa, Florida. With a market capitalization of $5.9 billion, it specializes in potash and phosphate fertilizers essential for crop growth and also develops biological solutions to improve nutrient efficiency and crop performance, serving customers in more than 40 countries.
Shares of this leading fertilizer company have substantially underperformed the broader market over the past year. MOS has dipped 18.6% during this period, while the broader S&P 500 Index ($SPX) has rallied nearly 13.5%. Likewise, the stock is down 10.3% year-to-date, underperforming the index's 12.3% gain over the same period.
Narrowing the comparison, MOS has continued to lag the State Street Materials Select Sector SPDR ETF (XLB), which has risen 27.2% over the past year and 18.9% year-to-date.
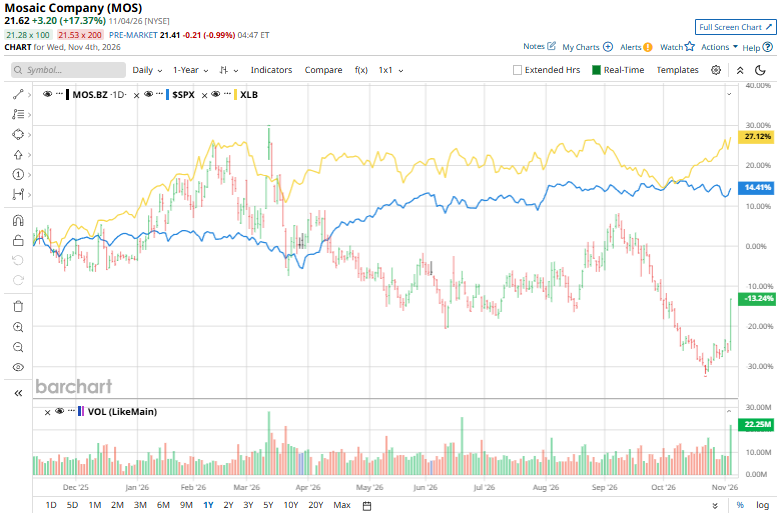
Despite missing earnings expectations, Mosaic shares staged a sharp rebound, jumping 17.4% in the following trading session after the company reported its Q3 2026 results on Nov. 3. Net sales declined 10.2% year over year to $3.10 billion, while adjusted EBITDA fell 59.8% to $324 million. Adjusted loss per share was 19 cents, compared with adjusted EPS of $1.04 in the prior-year quarter. Operating cash flow increased to $284 million from $229 million, while free cash flow improved to approximately breakeven from a $135 million outflow.
Looking ahead, Mosaic expects full-year 2026 capital expenditures of approximately $1.2 billion and potash production of 8.6 million tonnes. For the fourth quarter, the company projects phosphate sales volumes of 1.3 million to 1.6 million tonnes at DAP prices of $820 to $840 per tonne, and potash sales volumes of 2.3 million to 2.6 million tonnes at MOP prices of $255 to $275 per tonne. Mosaic also secured its fourth-quarter sulfur supply contract at $615 per long ton, which is expected to support free cash flow. For 2027, the company is targeting capital expenditures below $1 billion and has refinanced and extended all long-term debt maturities through 2028.
For the current fiscal year, ending in December 2026, analysts expect MOS’s diluted EPS to decrease sharply by 86.3% to 31 cents. The company has also missed Wall Street’s consensus EPS estimates in three of the past four quarters, while exceeding expectations only once.
Among the 19 analysts covering MOS stock, the consensus rating is “Moderate Buy.” That’s based on six “Strong Buy” ratings, 12 “Hold” ratings, and one “Strong Sell” rating.
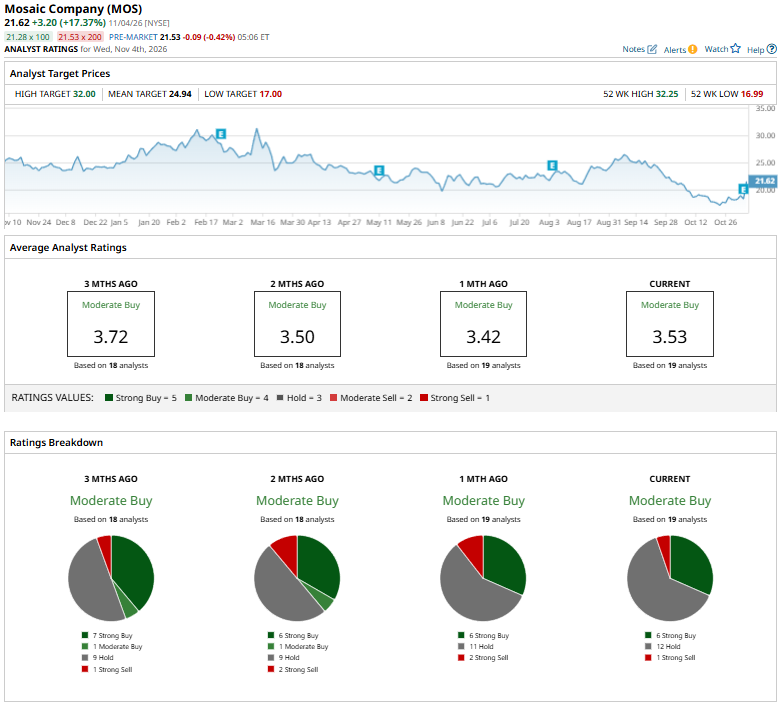
The configuration is more bearish than it was three months ago, when the stock had seven “Strong Buy” recommendations.
On Nov. 4, 2026, Mizuho Securities analyst Edlain Rodriguez maintained a “Hold” rating on The Mosaic Company and lowered his price target to $20 from $22.
The mean analyst price target of $24.94 implies a 15.4% premium to MOS's current share price, while the Street-high target of $32 suggests a potential premium of 48%.
On the date of publication, Abhishek Bhuyan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.