


EN
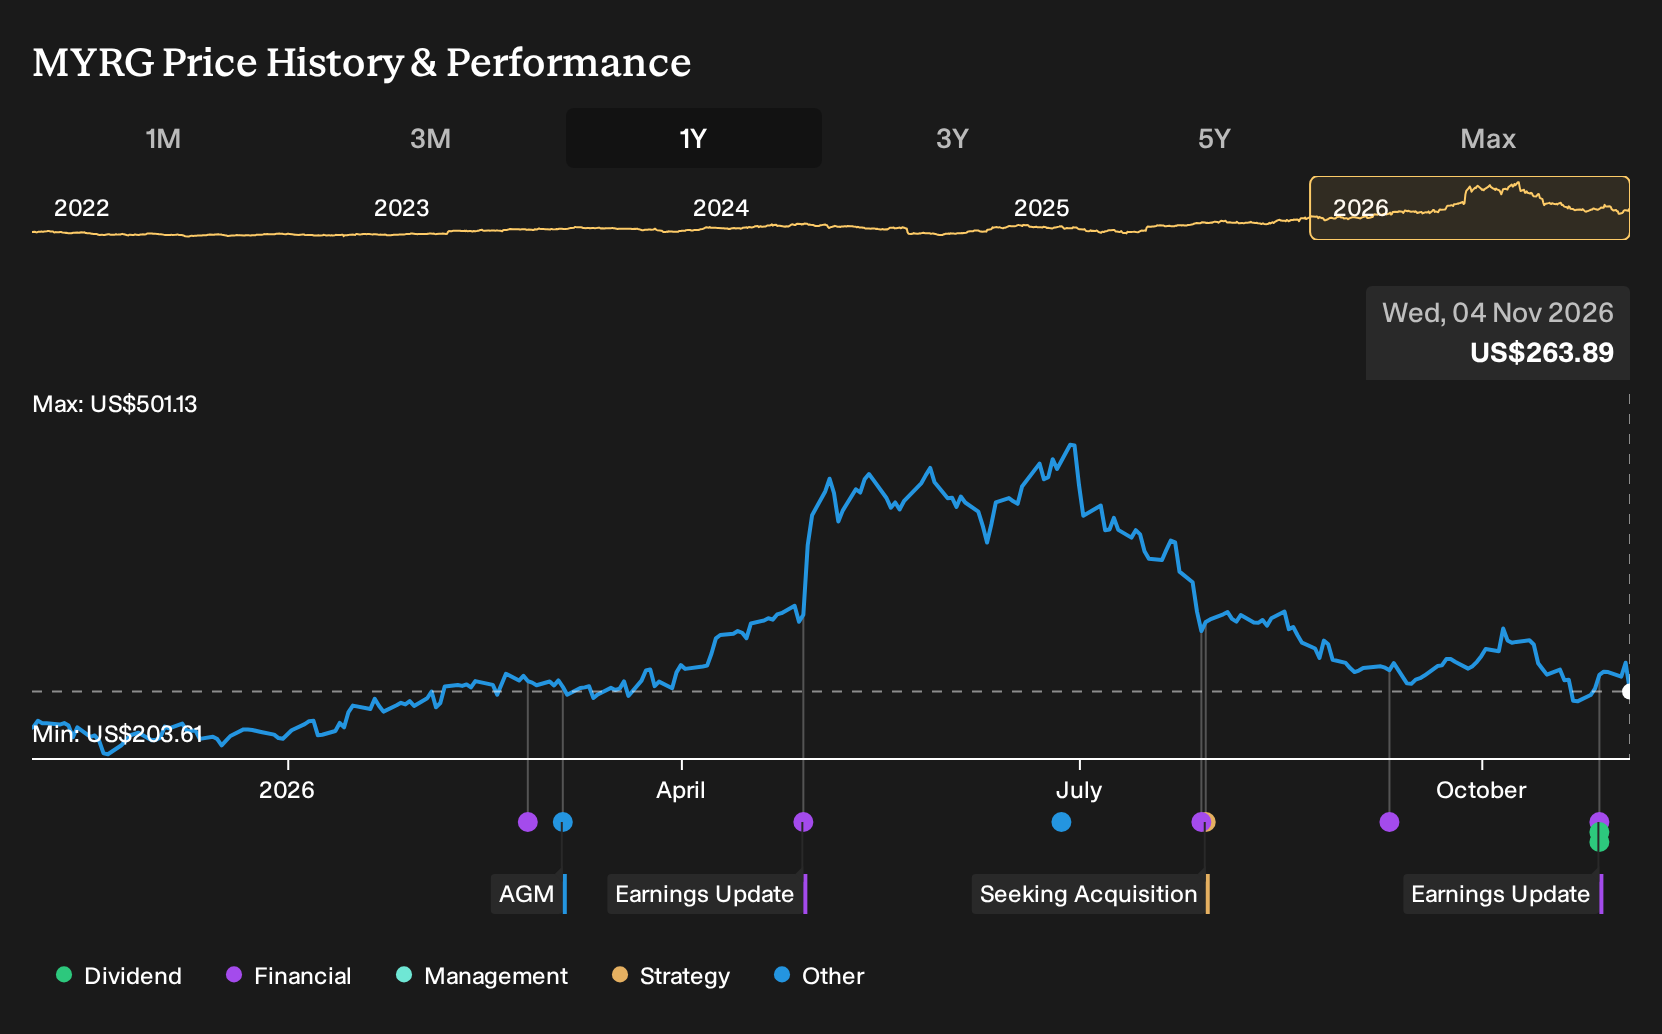
MYR Group Stock In Focus After Earnings Beat And $100 Million Buyback
- MYR Group reported third quarter 2026 sales of US$1,259.03 million and net income of US$60.01 million, with higher basic and diluted earnings per share from continuing operations than the same period in 2025.
- The newly authorized US$100 million share repurchase plan, funded by cash and the revolving credit facility, adds a capital allocation lever alongside MYR Group’s recent earnings strength.
- We will explore how MYR Group's investment narrative is affected by this strong earnings print and the newly announced share repurchase program.
MYR Group Investment Narrative Recap
To own MYR Group, you need to be comfortable with a construction contractor that leans on large grid, data center and infrastructure programs and then turns that backlog into clean execution. The latest quarter delivered higher sales and earnings per share than a year ago, which keeps that core thesis about project delivery and margin progress intact rather than changing it.
The more immediate swing factor is whether strong reported earnings translate into steadier cash generation as working capital moves around larger projects. Integration of Valley Holdings and any ongoing cash drag from timing, tax and capex remain key operational watchpoints, while the fresh earnings update itself does not materially shift those near term risks.
The announcement that MYR Group’s board has authorized up to US$100 million of share repurchases is the most relevant new data point here. It introduces another capital allocation choice alongside reinvestment in transmission, distribution and commercial or industrial work, and uses both existing cash and the revolving credit facility.
For shareholders, this buyback sits alongside upcoming transmission awards, the Valley Holdings acquisition and margin targets as moving parts that can influence per share results. Execution on large projects and acquisition integration, together with any cash strain from working capital or borrowings under the revolver, will shape how helpful this repurchase plan becomes around those catalysts.
MYR Group's current analyst narrative points to US$6.1b in revenue and US$304.2 million in earnings by 2029, based on an assumed 15.0% yearly revenue growth rate and an earnings increase of about US$139 million from US$165.3 million today.
Discover how MYR Group's fair value reflects a 45% potential upside to its current price before other investors respond to that difference.
Exploring Other Perspectives
One alternate view leans on backlog strength as the key catalyst. Bullish analysts were already penciling in about US$6.7b of revenue and US$343.3 million of earnings by 2029 for MYR Group before this earnings beat and buyback plan. You can use those more optimistic assumptions to test how much your own narrative might shift now.
Explore 4 other MYR Group fair value estimates, including one that suggests potential upside of up to 49% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MYR Group research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for MYR Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MYR Group's overall financial health at a glance.
Looking for more investment ideas beyond MYR Group?
Once you have a view on MYR Group, it can help to cross check that thesis against a wider field of potential opportunities using the Simply Wall St screener tools.
- If capital preservation is your priority, compare MYR Group with a broader pool of steadier businesses by screening for 31 resilient stocks with low risk scores that may suit a more cautious approach.
- If quality at a reasonable price is your focus, line up MYR Group against a curated 19 high quality undiscovered gems that may not yet be widely followed.
- If balance sheet strength matters most to you, weigh MYR Group against a list of solid balance sheet and fundamentals (24 results) to see which companies better match your comfort level on financial resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com