


EN
Lyft (LYFT) Stock Looks Undervalued As Privacy Settlement Raises Questions
Lyft has delivered a powerful 3 year share price rebound, which puts fresh focus on a simple but important question for investors who care about fundamentals. Is the current price around US$18.74 adequately supported by the ride hailing group's earnings power, given both recent returns and the latest headlines around the business.
- The stock has climbed 74.8% over the past 3 years, which raises the stakes on whether that move is aligned with what the underlying earnings can justify.
- A US$1.8 million privacy settlement with California authorities highlights ongoing regulatory and compliance demands that can influence future profitability and the timing of any excess cash available to shareholders.
- Your read on Lyft is one view; the desks covering it have another. See what analysts think Lyft's shares could be worth.
The issue now is whether the earnings generated by Lyft give enough support to the current share price, given this mix of stock performance and recent developments.
For context on Lyft's recent rebound, it can help to compare it with other transport and mobility plays using the 41 power grid technology and infrastructure stocks.
Is Lyft Still Cheap on Earnings?
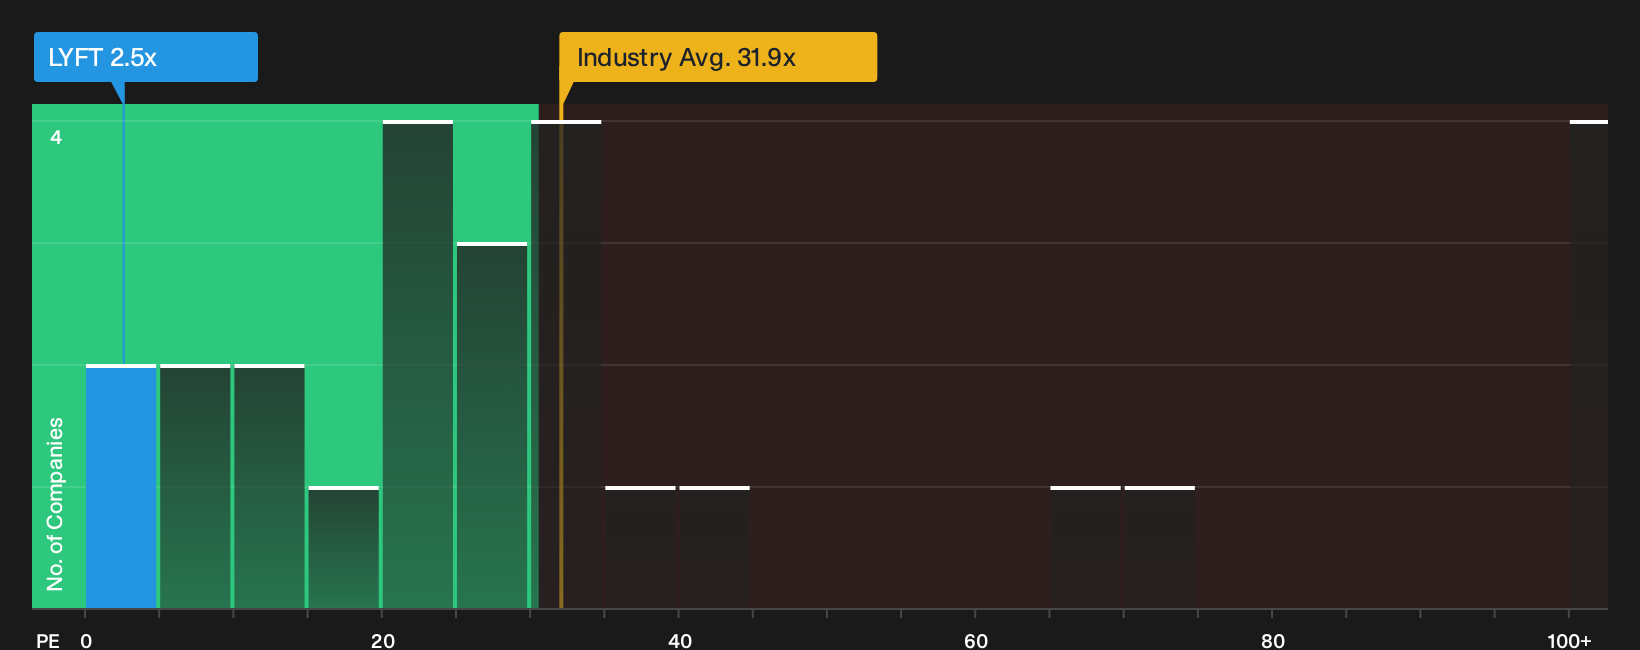
For Lyft, the P/E multiple fits because investors are weighing the price of the stock directly against the earnings power it currently reports. At a P/E of 2.5x, the shares trade far below the broader Transportation industry on 31.9x and also well under the 48.4x peer average, which points to a steep discount on this metric. A tailored fair multiple that blends Lyft's growth profile, profitability, sector and risk backdrop sits higher than the market is currently paying, so the stock comes through as undervalued on this framework.
Because the recent US$1.8 million privacy settlement adds regulatory friction rather than boosting near term profit, the fact that Lyft still trades at such a low P/E relative to this fair benchmark suggests the market is pricing in a lot of caution already. For readers, the key question is whether the earnings that anchor this ratio are robust enough to support a re rating closer to that implied fair level over time. Explore the numbers behind Lyft's P/E valuation.
The Lyft Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Lyft valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to look meaningfully mispriced. Each scenario links a fair value estimate to a clear storyline about possible drivers and threats, so over time you can see which version of Lyft's future appears to be aligning with real world developments on the Community page.
Lyft followers are split between those who see more upside in the current setup and those who think the risks are being underpriced.
Bull case: roughly fairly valued
"Premium modes like Lyft Black, Black SUV and TBR chauffeuring, which have recorded double digit yearly growth for 12 consecutive quarters and now draw from a higher share of professional drivers, point to a larger mix of higher fare rides that can support average revenue per trip and help lift net margins…"
Discover why this Narrative puts Lyft at roughly fairly valued.
Bear case: 34% overvalued
"Even as the California Gig Workers Union begins collective bargaining under Assembly Bill 1340, the combination of this organized driver representation with the precedent of the largest wage and hour misclassification settlement in state history and rising safety related lawsuits raises the risk that future agreements embed structurally higher pay and protection standards, locking in a cost base above what current models assume and compressing long term net margins…"
Explore why this Narrative puts Lyft at 34% overvalued.
Lyft's valuation still leaves one key concern hanging
Price and narratives only tell part of the story for Lyft, since our checks have also flagged specific operational and financial pressure points that deserve your attention before you lean too hard on the headline multiples. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com