


EN
Learn Why The Bull Case For Paycom Software Stock Could Change Following Earnings Beat
- Paycom Software reported third quarter 2026 revenue of US$543.8 million and net income of US$133.2 million, with earnings per share above analyst estimates and full year guidance raised after the period closed.
- The business linked its stronger earnings to greater use of its automated decisioning platform, suggesting product adoption is feeding through to operating efficiency and profitability rather than just headline top line growth.
- The next step is to assess how Paycom Software's upgraded full year outlook might reshape the existing investment narrative built around automation-led earnings power.
Scan how Paycom Software's automation story compares with other high efficiency software businesses by reviewing the 40 profitable AI stocks that aren't just burning cash that are already turning product adoption into earnings power.
Paycom Software Investment Narrative Recap
To hold Paycom Software, an investor needs to believe its automation suite, especially tools like IWant and Beti, keeps turning product usage into resilient recurring revenue and efficient earnings. The latest quarter supports that narrative, with revenue of US$543.8 million and net income of US$133.2 million pointing to an operation that is currently scaling without obvious strain.
The near term catalyst remains clear. Higher adoption of AI driven features and newer modules has to keep feeding into margins and wallet share. The main risk is that rivals narrow the tech gap or customers slow adoption, which would matter more than this single earnings beat.
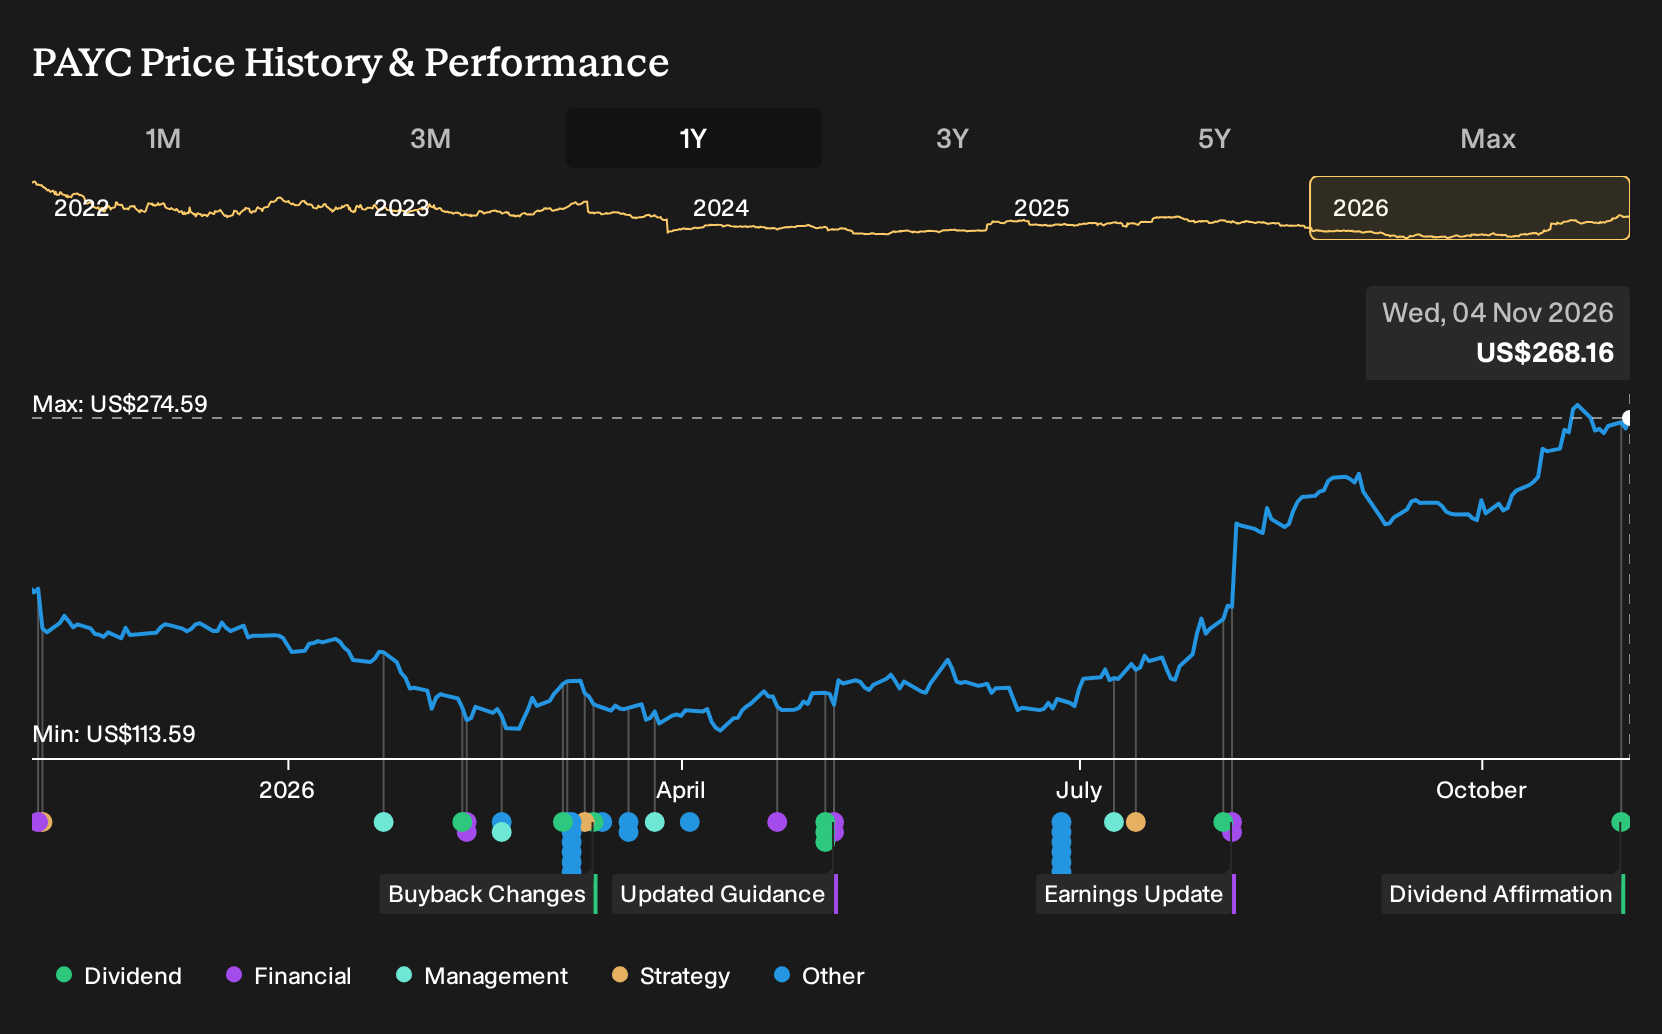
The earnings release on 4 November is the announcement that most directly shapes that catalyst. Paycom Software reported third quarter basic EPS of US$3.01 from continuing operations, up from US$1.97 a year earlier, and lifted full year revenue guidance to a range of US$2.21 billion to US$2.22 billion. That points to automation benefits showing up in the income statement, not just in marketing slides.
For you, the link is straightforward. Stronger profitability and updated guidance support the idea that prior spending on AI ready data centers and platform rollouts is translating into operating leverage. The flip side is that expectations around execution are now higher, so any slowdown in module adoption or any need for heavier ongoing infrastructure spend could become more visible in future results.
Paycom Software's narrative projects US$2.6b revenue and US$626.9 million earnings by 2029. This assumes 7.0% yearly revenue growth and an earnings increase of about US$139.3 million from US$487.6 million today.
Uncover why Paycom Software's fair value indicates a 9% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
For a different angle, consider the risk that Paycom Software’s newer modules do not significantly shift its payroll-heavy profile. The lowest analyst forecasts were for about US$2.6b of revenue and US$544.0 million of earnings by 2029, with margins easing. Those expectations were set before this earnings beat, so use them as a reference point and compare both scenarios side by side.
Explore 3 other Paycom Software fair value estimates, including one that suggests as much as 9% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Paycom Software research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Paycom Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Paycom Software's overall financial health at a glance.
Looking for more investment ideas beyond Paycom Software?
If Paycom Software has sharpened your thinking about automation and earnings quality, use that same lens across a broader watchlist. The Simply Wall St Screener can help you quickly sort through companies that fit different risk, income, and balance sheet profiles so you are not relying on a single story.
- If capital preservation comes first for you, start with a group of companies that score well on stability and risk by reviewing 31 resilient stocks with low risk scores for potential candidates.
- If you want to focus on resilient finances, filter for businesses with stronger balance sheets and consistent fundamentals through the list of solid balance sheet and fundamentals (24 results) that keeps quality front and center.
- If you are hunting for opportunities the crowd may have overlooked, widen the search with a 19 high quality undiscovered gems that already show solid fundamentals but receive less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com