


EN
Simply Good Foods (SMPL) Stock Could Sit Above Fair Value On Sales
Simply Good Foods has just delivered a sharp bounce in its share price after a long slide, which puts the spotlight squarely on whether the current valuation lines up with the sales the company is generating. After such a mixed return profile, the key issue now is how much revenue investors are effectively paying for at today's price.
- Over the past 5 years the stock has fallen 66.6%, which raises the question of whether the market is still reassessing what its sales are worth.
- The business model leans on branded nutrition products that can support steady revenue, so the price investors pay today may hinge on how durable those sales prove to be over time.
- The analysts covering Simply Good Foods have run their own numbers. See what analysts think Simply Good Foods's shares could be worth.
The stock's next move may depend on whether Simply Good Foods' share price is now in line with what its current and potential sales can justify.
If you are weighing whether Simply Good Foods' recent rebound lines up with the sales investors are paying for, a focused stock screen is a useful second reference point, starting with 35 high quality undervalued stocks.
Has Simply Good Foods Run Too Far on Sales?
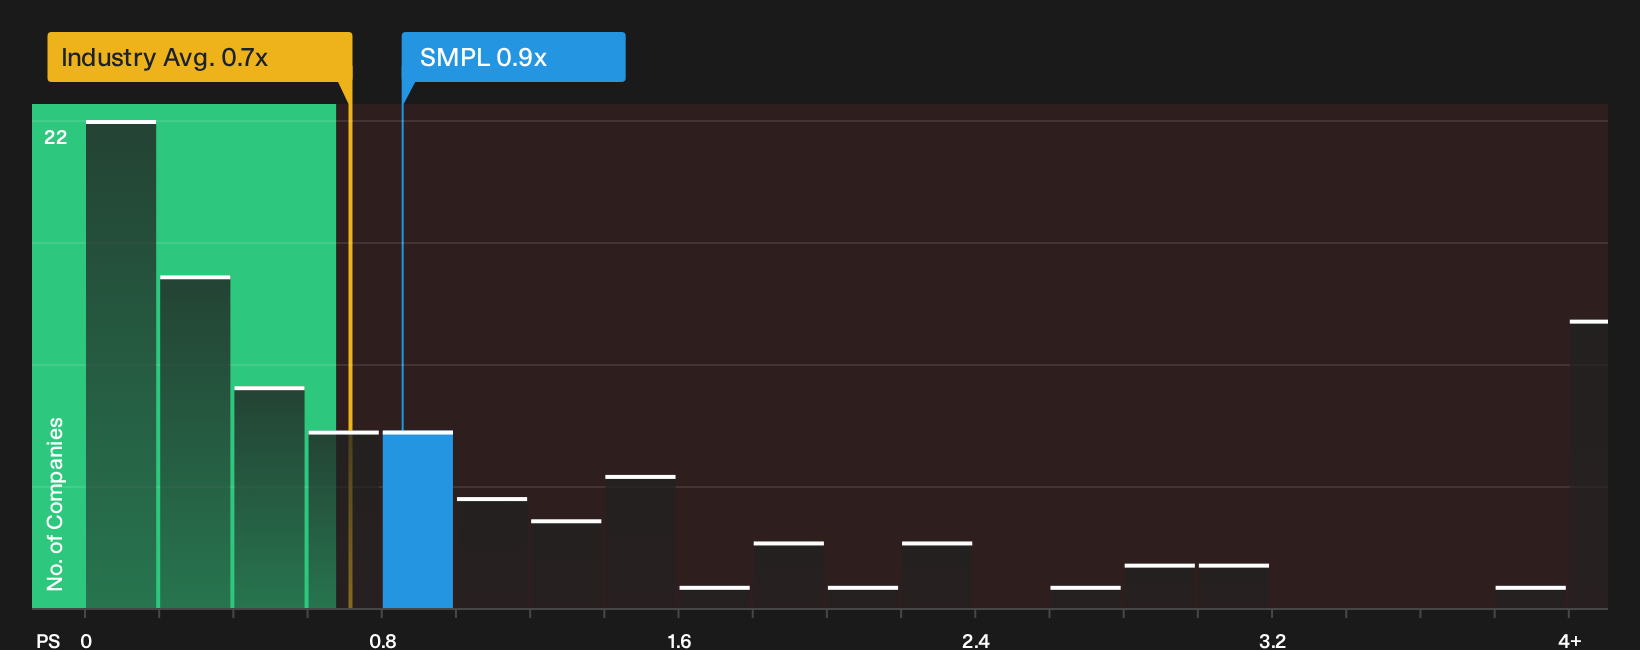
P/S is a clean way to look at Simply Good Foods because the business is built around branded nutrition products where revenue is a key anchor for value. On this yardstick, the stock trades on a P/S of about 0.9x, compared with a Food industry average around 0.7x and a peer group near 0.6x.
That gap suggests investors are paying a premium to the level that a tailored fair P/S estimate would point to, which leans toward Simply Good Foods looking overvalued on this measure. For you, the question is whether the brand strength, product mix and execution quality justify paying more sales dollars per share than both the industry and the model imply. Explore the numbers behind Simply Good Foods's P/S valuation.
The Simply Good Foods Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that P/S puzzle leaves off. They spell out which future paths for Simply Good Foods' growth, margins and earnings would need to play out for the stock to look meaningfully higher or lower than today’s valuation. Instead of a single ratio or model output, they unpack the set of assumptions behind it so you can see what the current number rests on and watch whether reality matches it over time on the Community page.
Simply Good Foods splits opinion, with one camp arguing the recent slide has gone too far while another sees the rebound already baking in a tough reset story.
Bull case: 30% undervalued
"The multi year plan to rebuild gross margin using high single digit pricing, supply chain productivity and lower promotion spend is being supported by confirmed cocoa cost deflation…"
Discover why this Narrative puts Simply Good Foods at 30% undervalued.
Bear case: 11% overvalued
"Persistent declines in the Atkins brand, which represents a meaningful share of net sales and is currently seeing retail takeaway fall more than 20% alongside distribution losses and an impairment charge on brand intangibles, could continue to drag on overall company growth and gross margin…"
Explore why this Narrative puts Simply Good Foods at 11% overvalued.
The open question for Simply Good Foods, and what the pros think happens next
Valuation only shows what the market is paying today. The bigger curiosity is how professional forecasters currently see Simply Good Foods a few years out compared with that price. Explore where analysts expect Simply Good Foods to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com