


EN
CoreCivic (CXW), What Is Behind The Latest Attention?
CoreCivic (CXW) just delivered third quarter results that sharply reshaped its recent story, reporting revenue of US$744.09 million and net income of US$1,344.14 million. This resulted in basic earnings per share from continuing operations of US$14.62.
CoreCivic’s share price has eased in the short term, with a 1-month share price return down 9.52% and a 90-day share price return down 5.33%. However, the year-to-date share price return of 60.46% and 1-year total shareholder return of 63.73% still point to strong momentum building over a multi year horizon.
Scan opportunities beyond CoreCivic by reviewing the hand picked 31 resilient stocks with low risk scores that have shown resilience even when sentiment around specific sectors swings hard on policy headlines.
CoreCivic now trades well below the average analyst price target, yet the stock has cooled after the latest political shock. Is that discount a cushion, or is it a warning sign for valuation work ahead?
Most Popular Narrative: 27% Undervalued
The most followed CoreCivic thesis points to a fair value of $41.80, which sits well above the last close at $30.52. The gap between price and narrative expectations is material.
The surge in ICE detainees housed at CoreCivic facilities, with populations up about 59.6% between early 2025 and mid 2026 and nationwide detention counts near historic highs, points to ongoing federal demand that can support higher occupancy and revenue as enforcement and funding cycles play through future periods.
The rebound in ICE detention volumes after the DHS funding related disruption, alongside improving but still sub pre pandemic Residential occupancy in the high 70% range, leaves capacity for further utilization gains that can add operating leverage and support higher adjusted EBITDA and net income if beds continue to fill.
See why 15 investors see CoreCivic as 27% undervalued.
Result: Fair Value of $41.80 (UNDERVALUED)
Still, this CoreCivic story leans heavily on continued ICE detention demand and ongoing federal funding. As a result, contract changes or policy shifts could quickly unsettle that thesis.
Find out about the key risks to this CoreCivic narrative.
Another View On CoreCivic’s Valuation
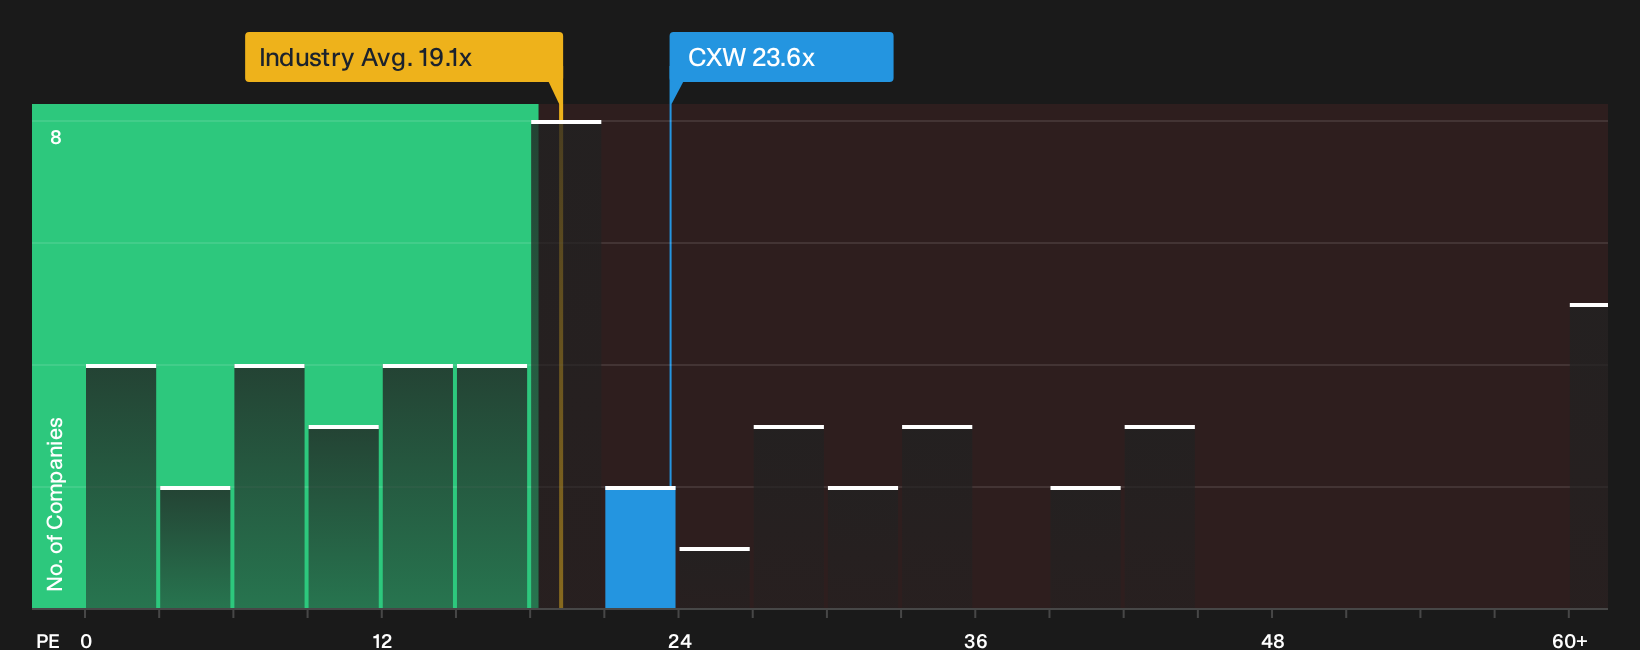
The narrative points to CoreCivic looking 27% undervalued at a fair value of $41.80, yet the current P/E of 23.6x tells a different story. That multiple is higher than the US Commercial Services industry at 18.9x and above a fair ratio of 9.8x, which signals meaningful valuation risk if sentiment cools.
When a stock trades at a richer P/E than both peers and its own fair ratio, future returns can depend more on continued contract strength and earnings delivery than on multiple expansion. That raises a simple question: is this a discount to fair value or a premium to what the cash flows and risks really justify?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on the story so far, or just curious where you stand on CoreCivic yourself? Act quickly, review the underlying data, and weigh both the upside and the red flags by digging into the 2 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond CoreCivic?
CoreCivic might be front of mind today, yet your next strong idea could come from a very different corner of the market if you are willing to look wider.
- Target sturdier balance sheets by scanning the list of solid balance sheet and fundamentals (24 results) that pair healthier finances with business models built to handle tougher conditions.
- Hunt for mispriced potential through the 19 high quality undiscovered gems that combine quality fundamentals with limited coverage and fresh upside scenarios.
- Strengthen your income focus by reviewing the 5 dividend fortresses that offer higher yields while still keeping an eye on sustainability and payout discipline.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com