


EN
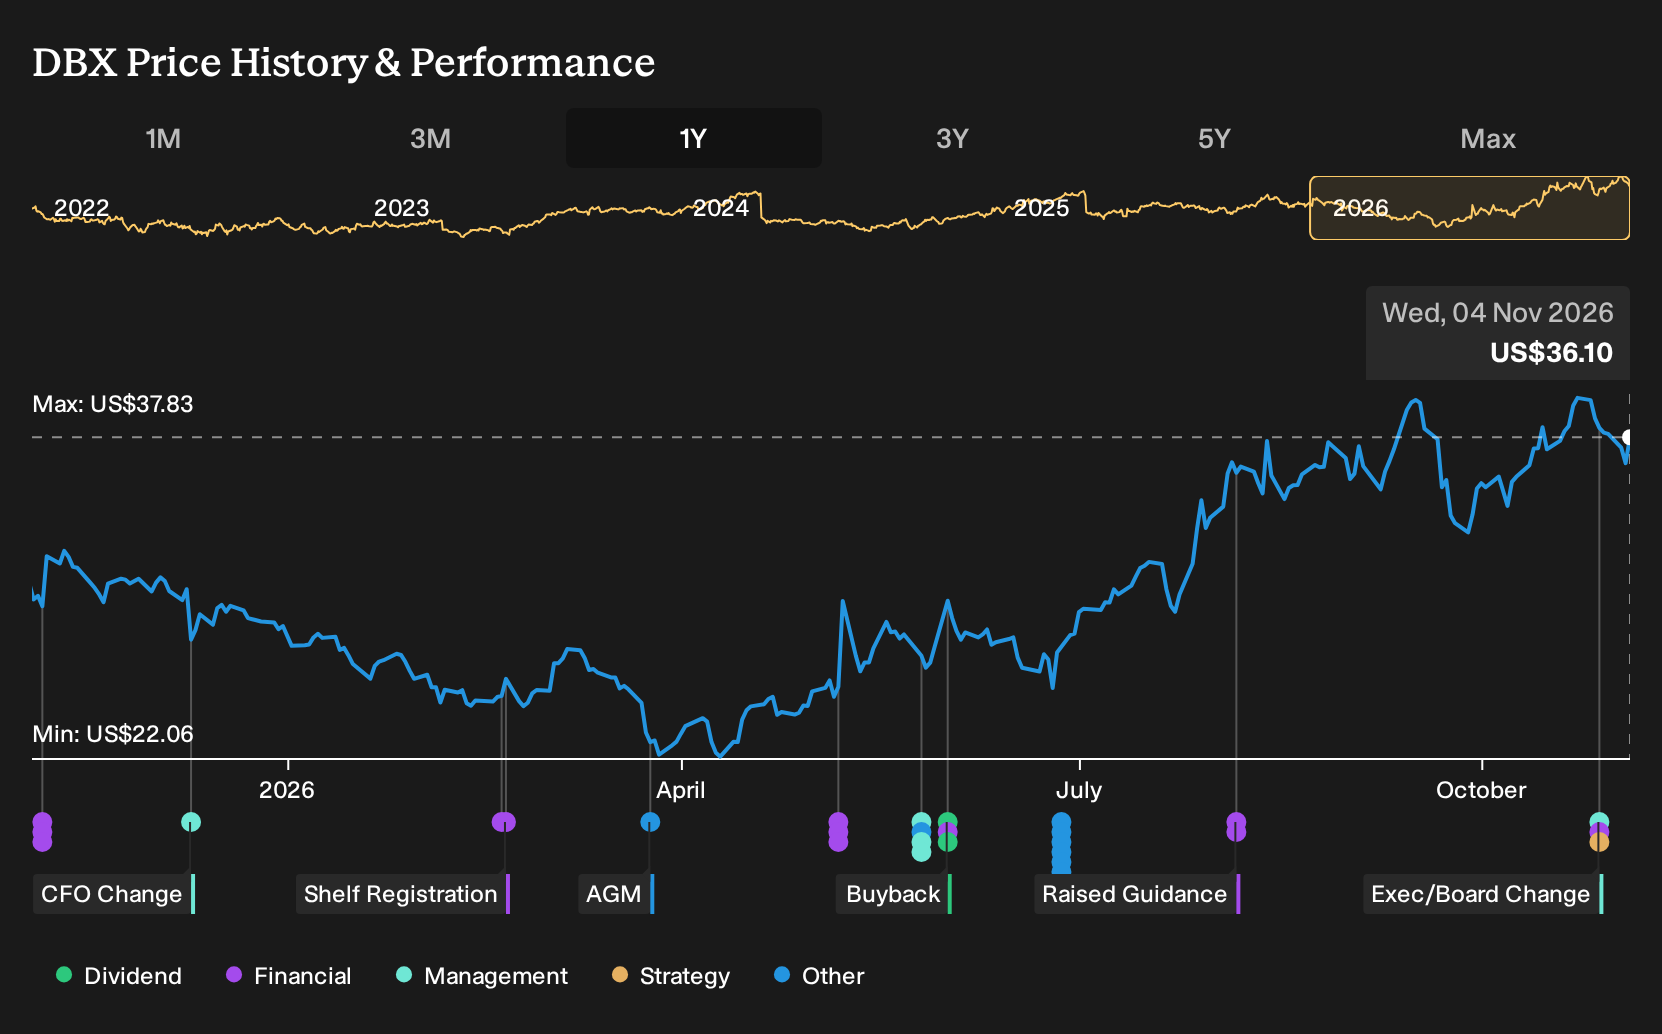
How Investors Are Reacting To Dropbox Stock 9% Workforce Cut
- Dropbox reaffirmed that third quarter 2026 revenue should land in line with or above prior guidance, while at the same time cutting roughly 9% of its global workforce and preparing for CTO Ali Dasdan’s departure, tied to a reorganization around top product and AI priorities.
- The restructuring carries estimated cash costs of about US$27 million to US$33 million and US$20 million to US$25 million of incremental expenses. This concentrates Dropbox’s spending on AI centric products and content workflows, while near term profitability absorbs the severance and related payouts.
- We will now look at how Dropbox’s investment narrative could shift as it trims 9% of staff to refocus on AI centric products.
Scan beyond Dropbox and compare this pivot to AI focused peers by reviewing the 40 profitable AI stocks that aren't just burning cash that already back their ambition with real earnings power.
Dropbox Investment Narrative Recap
To own Dropbox, you need to believe its AI centric tools can turn a large free user base into steadier subscription demand without eroding profitability through higher compute and infrastructure costs. The reaffirmed guidance for Q3 2026 revenue staying in line with or above prior ranges suggests the restructuring does not materially change the near term revenue catalyst.
The bigger swing factor sits on the cost and execution side. A 9% headcount cut and related severance, plus CTO turnover, introduces some operational risk while management reorganizes around top product and AI priorities. Short term earnings will absorb restructuring charges, which may weigh on reported profitability until those costs roll off.
The most relevant announcement here is the workforce reduction tied to AI focused priorities. Cash expenditures of roughly US$27 million to US$33 million and US$20 million to US$25 million of incremental expenses concentrate resources on AI products like Dash and content workflows at a time when gross margins already face pressure from infrastructure and compute costs.
For you, the key question is whether this reset helps Dropbox convert engagement in AI tools into higher average revenue per user and more durable subscription trends without further margin strain. Execution on security, given the August 2026 hack, and careful management of infrastructure spending remain important watchpoints as the business leans harder into AI heavy workloads.
Dropbox's consensus narrative points to US$2.6b in revenue and US$464.7m in earnings by 2029, with analysts assuming fairly flat annual revenue growth over that period and an earnings increase of about US$21.9m from US$442.8m today.
Uncover why Dropbox's fair value indicates a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
The sharpest contrast comes from how bearish analysts treat AI costs at Dropbox. Where the baseline view focuses on stable margins, the lowest forecasts lean into the risk that AI stays mostly a cost center. They were penciling in about US$2.5b of 2029 revenue and US$453.1m of earnings before this news, so their story could shift meaningfully from here.
Explore 2 other Dropbox fair value estimates, including one that suggests there may be up to 7% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Dropbox research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Dropbox. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dropbox's overall financial health at a glance.
Looking for more investment ideas beyond Dropbox?
If this Dropbox reset around AI has you thinking about portfolio balance, it can help to line it up against other opportunities that match your risk tolerance and return goals.
- For investors who care most about financial strength and staying power, start with a list of solid balance sheet and fundamentals (24 results) that can help you focus on resilience first.
- If your priority is reducing downside risk while still aiming for steady compounding, filter the market using a 31 resilient stocks with low risk scores that screens for more measured profiles.
- When you want to hunt for underfollowed potential, cast a wider net across a 19 high quality undiscovered gems that highlights lesser known businesses with strong fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com