


EN
HealthEquity (HQY) Jumped, But What Is Drawing Fresh Attention Now?
HealthEquity (HQY) heads into a key date after scheduling its third quarter fiscal 2027 results release for December 1, 2026, with a same day investor call drawing fresh focus to the stock.
Recent trading suggests momentum has picked up, with a 1-day share price return of 6.67% and a 30-day share price return of 19.54% lifting HealthEquity to US$108.84. The 1-year total shareholder return of 17.36% and 3-year total shareholder return of 60.65% point to a stronger multi year record than the recent quarter alone implies.
Scan how HealthEquity's momentum fits alongside other potential breakouts by running the same lens over a hand picked set of 35 high quality undervalued stocks.
HealthEquity now trades near a fresh high after that sharp run, so the key question is whether the current price still presents a more favorable upside-to-downside balance as valuation comes into sharper focus.
Most Popular Narrative: 9% Undervalued
On Simply Wall St's most followed narrative, HealthEquity screens as undervalued, with a fair value of about $119.33 against the recent $108.84 close. That view leans heavily on how the business uses custodial cash, digital engagement and buybacks to turn its HSA footprint into earnings power.
The recent regulatory expansion that allows direct primary care, pre-deductible telehealth and new ACA Bronze and catastrophic plan members to qualify for HSAs continues to enlarge HealthEquity’s addressable market. This can feed future HSA account and asset growth and support revenue.
See why 6 investors see HealthEquity as 9% undervalued.
Result: Fair Value of $119.33 (UNDERVALUED)
Still, the HealthEquity narrative can crack if weak employment growth slows new HSA onboarding or if ongoing fee pressure keeps service revenue trailing overall top line progress.
Find out about the key risks to this HealthEquity narrative.
Another View on HealthEquity’s Valuation
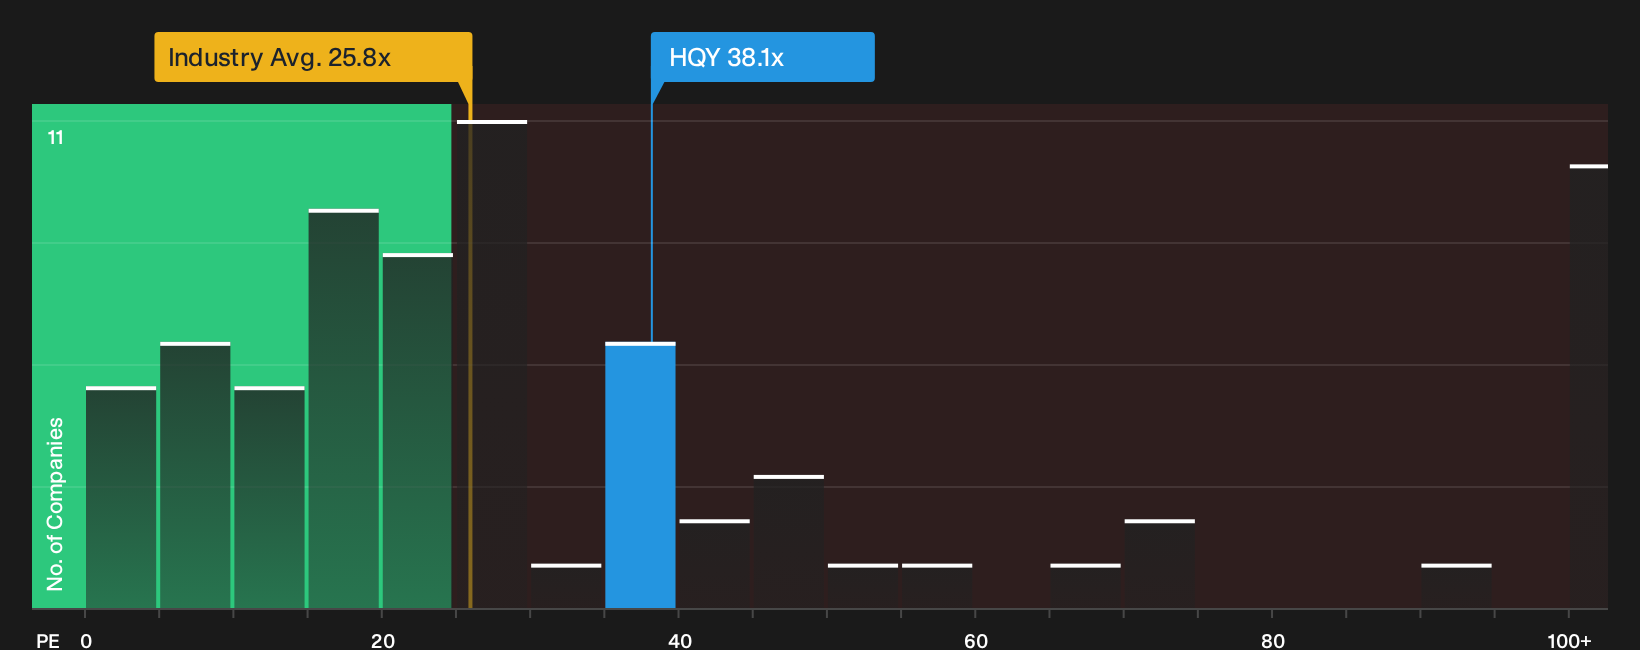
The first narrative leans on fair value around $119.33, yet HealthEquity trades on a P/E of 38.1x. That is above the estimated fair ratio of 27.3x and above the wider US Healthcare industry on 24.8x, which points to meaningful multiple risk if sentiment cools.
If you prefer to anchor your work in this kind of ratio check, it is worth stress testing what would need to go right for earnings to fully justify today’s richer P/E, and what a move toward the fair ratio might mean for your return expectations. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around HealthEquity is clearly optimistic, yet the real edge comes from testing those assumptions against your own work and time frame. If you want to see which potential upsides other investors are focusing on right now, start with the 3 key rewards.
Looking For More Investment Ideas Beyond HealthEquity?
If HealthEquity has sharpened your thinking, do not stop here. Broaden your watchlist with a few targeted filters that surface specific strengths and potential opportunities.
- Target durable balance sheets by reviewing a curated list of solid balance sheet and fundamentals (24 results) that highlights businesses with financial footing built to handle tougher conditions.
- Hunt for mispriced quality through the 19 high quality undiscovered gems and see which lesser known stocks combine healthy fundamentals with under-the-radar potential.
- Dial up resilience by scanning the 31 resilient stocks with low risk scores so you are not leaving calmer, steadier return profiles on the table while attention chases headlines.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com