


EN
Luckin Coffee (LKNCY) Stock May Trade At A Discount As Buyback News Lands
Luckin Coffee has delivered a very strong 5 year share price run, which naturally raises the question of whether the current US$34.45 quote is still aligned with the cash the business can generate. With investors also watching fresh company announcements, the focus now turns to what its underlying cash flows say about today's valuation.
- The stock is up 135.2% over 5 years, so anyone looking at Luckin Coffee now is implicitly taking a view on whether that long haul gain is supported by its future cash generation.
- Management has reported revenue growth alongside margin improvements and a large new share repurchase plan, which can influence how much cash is available for reinvestment versus returning money to shareholders over time.
- Prefer to judge Luckin Coffee on earnings? See what Luckin Coffee's 17.0x P/E says about the price.
For investors, the debate is whether Luckin Coffee's current share price is justified by the intrinsic value implied by its cash flows today.
If you want to see how Luckin Coffee's cash flow story compares with other opportunities, you can evaluate it alongside companies in the 35 high quality undervalued stocks.
Is Luckin Coffee a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) approach here focuses on the cash Luckin Coffee can return to shareholders over time. On this model, the group is generating last twelve month free cash flow of about CN¥4.8b, with analysts expecting that figure to move higher over the next decade, which implies a growing cash base rather than a shrinking one. Those projections help explain why the DCF output sits substantially above the current US$34.45 share price, even without assuming extreme expansion.
Because the latest Q3 2026 update points to higher revenue, a larger store footprint and wider operating margins, the projected ramp in free cash flow is broadly consistent with how Luckin Coffee is currently being run. The new US$500m buyback plan also matters because it can spread that CN¥ cash pool over fewer shares if fully executed, which supports the DCF outcome relative to today’s market quote. That is why the model indicates the estimated intrinsic value is substantially above where the stock trades today. Find out what Luckin Coffee could be worth using our Discounted Cash Flow (DCF) estimate.
The Luckin Coffee Narrative: What Would Justify Today's Price?
Narratives for Luckin Coffee pick up where the cash flow puzzle leaves off. They spell out which specific paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or less than today’s market price. These narratives sit on Simply Wall St’s Community page as scenarios that each link an implied value to a clear view on how Luckin Coffee's expansion, margins and risks could evolve, giving you something concrete to revisit when fresh information arrives.
One of the top community narratives on Luckin Coffee: 29% undervalued
"The main factor that has to go right is that Luckin Coffee converts its rapid footprint growth and heavy spending on rentals, delivery, and technology into durable store-level productivity and margins..."
Discover why this Narrative puts Luckin Coffee at 29% undervalued.
One more piece of the Luckin Coffee puzzle investors should check
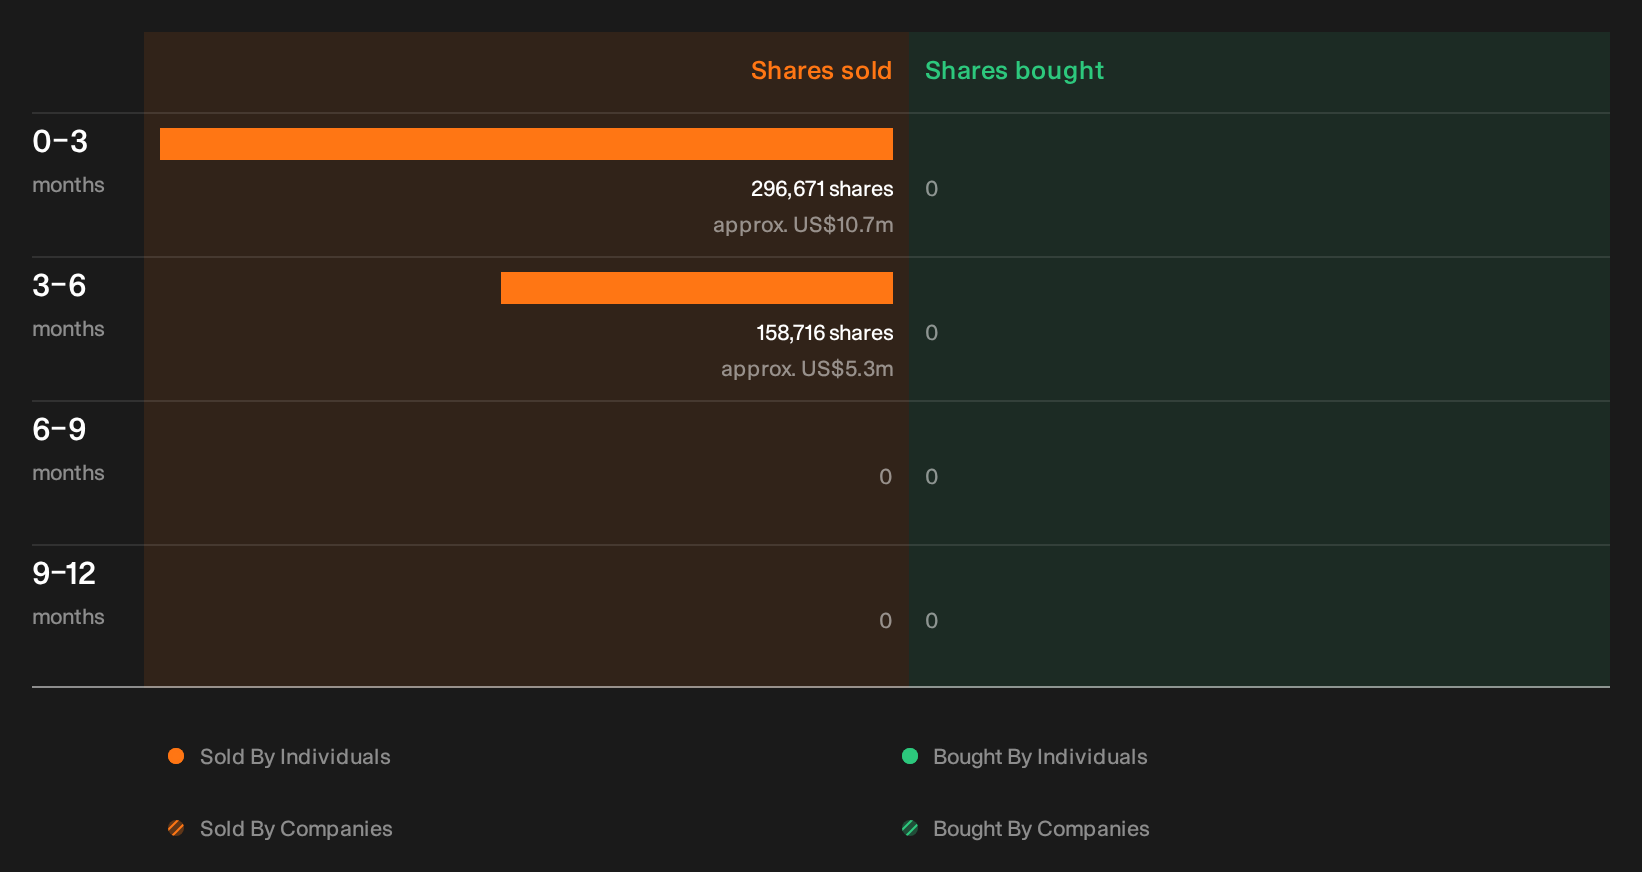
Before you move on from Luckin Coffee, there is one more angle that deserves a closer look, recent deals by people inside the business that our checks have picked up. See the recent insider selling flagged for Luckin Coffee.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com