


EN
How Investors Are Reacting To Knight Swift Stock After An Earnings Beat
- Riverwater Partners recently increased its stake in Knight-Swift Transportation Holdings after the carrier reported an earnings beat paired with conservative guidance and a cautious outlook.
- In the same quarter, hedge fund ownership in Knight-Swift expanded from 53 to 69 portfolios, signaling deeper institutional focus on trucking’s early-cycle recovery narrative.
- Next, the investment narrative for Knight-Swift Transportation will be weighed against this renewed institutional interest following the latest earnings beat.
Scan how institutions are positioning around trucking’s early-cycle recovery by lining up Knight-Swift Transportation against the hand-picked 19 high quality undiscovered gems that investors are starting to notice.
Knight-Swift Transportation Holdings Investment Narrative Recap
To own Knight-Swift Transportation Holdings, you need to believe that a broad trucking and logistics cycle is gradually turning in its favor and that the company can convert that into cleaner margins across truckload, LTL, logistics and intermodal. The recent earnings beat with conservative guidance supports the idea that operations are stabilising, but it does not remove the near term freight softness that has limited pricing power and kept returns under pressure.
The key short term catalyst is whether freight demand and mix are strong enough for Knight-Swift Transportation Holdings to make recent cost and technology investments show up consistently in operating ratios. The biggest immediate risk is that LTL integration costs, higher insurance and tighter logistics carrier vetting continue to weigh on profit metrics while the market watches for firmer evidence of a sustained cycle upturn.
The most relevant development is the earnings report that prompted Riverwater Partners to add to its position. The company delivered results ahead of expectations while pairing that outcome with cautious guidance, which keeps the focus squarely on whether operational execution, rather than optimism about a trucking recovery, can sustain better profitability from here.
For you as a shareholder, that update links directly to the existing catalysts around LTL expansion, technology rollouts and a more diversified freight mix. Those levers only matter if they translate into steadier operating income and justify Knight-Swift Transportation Holdings trading on what has recently been a relatively high P/E multiple, given past EPS declines and still modest revenue growth.
Knight-Swift Transportation Holdings is modeled to reach US$9.8b in revenue and US$746.2m in earnings by 2029. Analysts build this on an assumed 8.1% yearly increase in sales and an earnings rise of about US$703m from current earnings of US$42.9m.
Discover how Knight-Swift Transportation Holdings' fair value indicates a 36% potential upside to its current price that may not last.
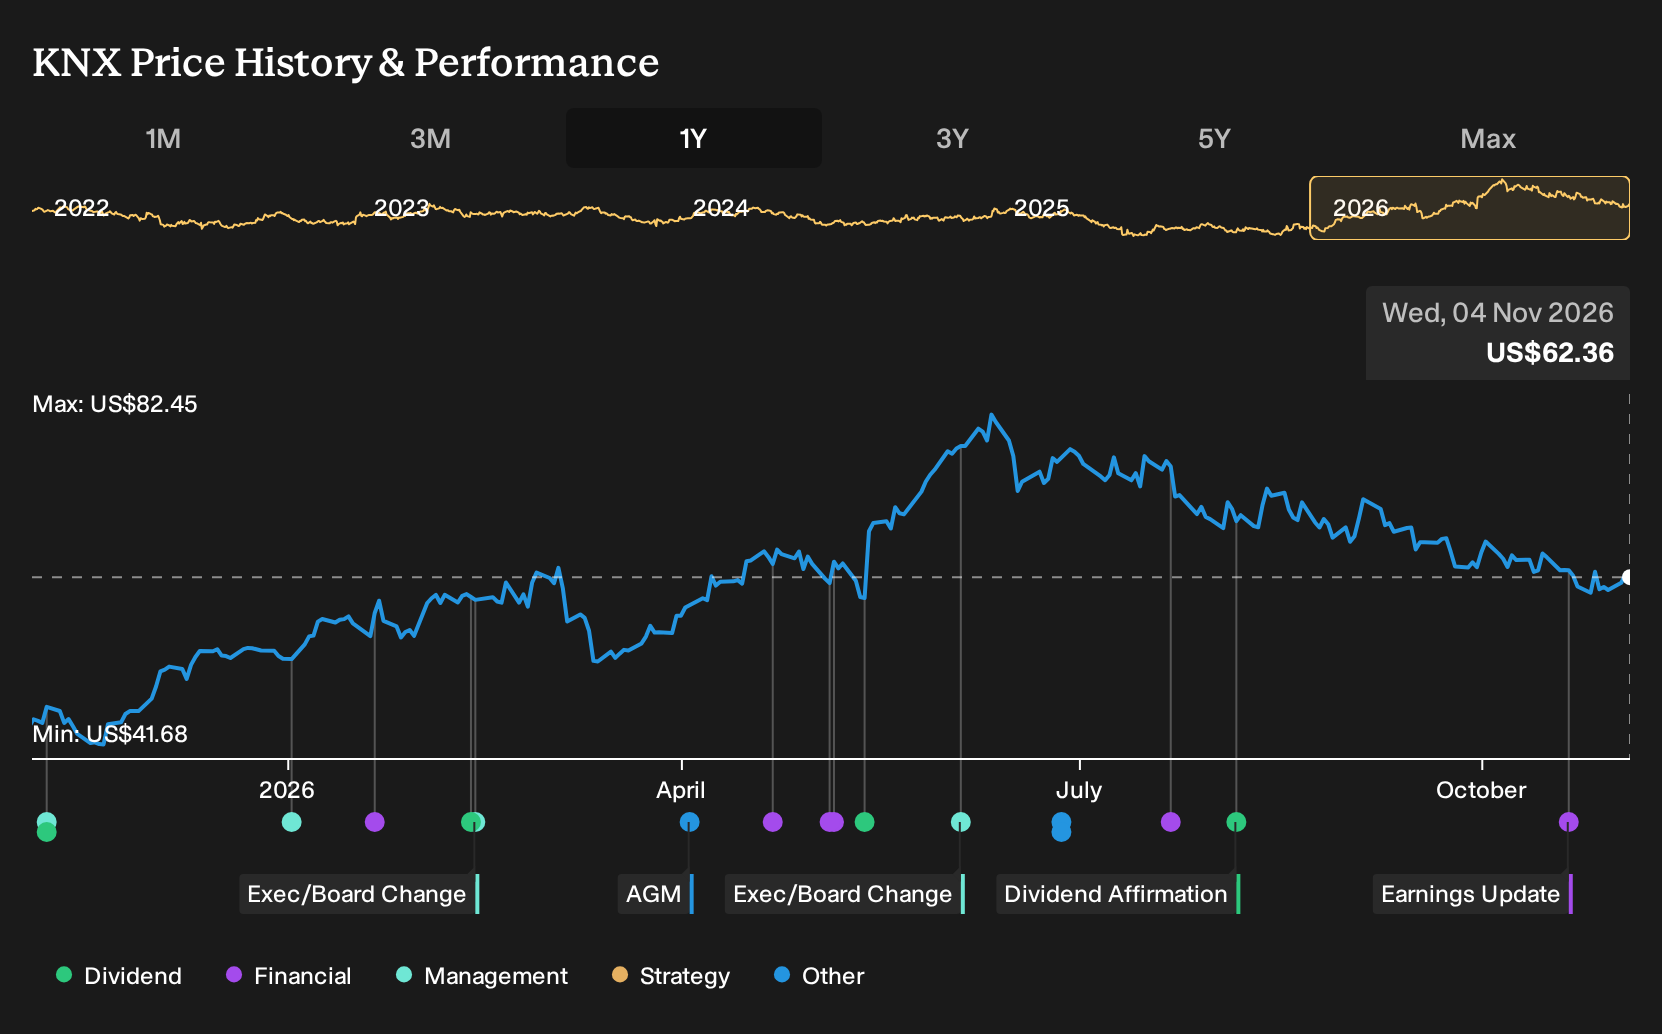
Exploring Other Perspectives
One alternate story around Knight-Swift Transportation highlights insurance and compliance costs as the real swing factor. The most cautious analysts were only penciling in about 5% annual revenue growth to roughly US$9.3b and earnings of around US$807.5m by 2029. That is a much more restrained setup. The latest earnings beat and extra hedge fund interest could nudge those assumptions, so it may be useful to compare several viewpoints before deciding how this fits a portfolio.
Explore 3 other Knight-Swift Transportation Holdings fair value estimates, including one that suggests as much as 19% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Knight-Swift Transportation Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Knight-Swift Transportation Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Knight-Swift Transportation Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Knight-Swift Transportation?
Once you have a handle on Knight-Swift Transportation Holdings and how it might fit your goals, it can help to widen the lens and compare it with other opportunities that share similar qualities, whether that is valuation support, balance sheet strength or income potential.
- If you want to focus on quality businesses that the market is pricing cautiously, scan through 35 high quality undervalued stocks to see which tickers currently combine solid fundamentals with a lower market expectation.
- For investors who care most about staying on the front foot with financial resilience, sort companies using the list of solid balance sheet and fundamentals (24 results) and see which ones pair robust finances with fundamental stability.
- If a steady stream of cash returns matters to you, filter for income-focused opportunities by reviewing the 5 dividend fortresses and compare yields, payout ratios and consistency.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com