


EN
Insulet Stock Has The Bull Case Changed After Earnings Beat
- Insulet reported past third quarter 2026 revenue of US$842 million and net income of US$141.1 million, beating analyst expectations and lifting earnings per share to US$2.03 from US$1.24 a year earlier.
- The Board also approved a share repurchase program of up to US$1 billion through 2028, signaling confidence in Omnipod-driven recurring cash generation and long-term profitability.
- The focus is now on how Insulet's strong Q3 beat and US$1 billion buyback authorization could reshape the medium-term investment narrative.
Scan how Insulet's latest earnings beat and buyback plan compare with other potential opportunities by checking the hand-picked 38 healthcare AI stocks on Simply Wall St.
Insulet Investment Narrative Recap
To own Insulet, you essentially need to believe the Omnipod platform keeps attracting more users and keeps them engaged long enough to support that high margin, recurring pod model. The latest quarter, with US$842 million of revenue and US$141.1 million of net income, reinforces that the current operating setup is delivering meaningful scale.
The near term swing factor is still execution in type 2 diabetes and retention, where weaker early utilization has already fed into softer U.S. growth assumptions. Strong Q3 numbers help cushion that, but they do not remove the risk that ongoing pricing and adherence pressure in type 2 holds back the next leg of progress.
The US$1 billion share repurchase program running through 2028 is the announcement that ties most directly into this earnings beat. Management is effectively committing material capital to reduce the US$10.7b market cap share base while the business is generating rising profits, with basic EPS at US$2.03 for the quarter and US$4.70 for the first nine months.
For you as an investor, the key question is how this buyback sits alongside the main operating levers. Execution on Omnipod adoption, international expansion, and retention in type 2 remains the primary catalyst, while the recall history, potential quality related costs, and any sustained weakness in U.S. type 2 behavior stay at the top of the risk list.
Insulet's narrative points to revenues of US$4.5b and earnings of US$675.9m by 2029, based on analysts assuming 13.7% yearly revenue growth and earnings rising by roughly US$300.6m from US$375.3m today.
Uncover why Insulet's fair value indicates that Insulet is roughly in line with its current price.
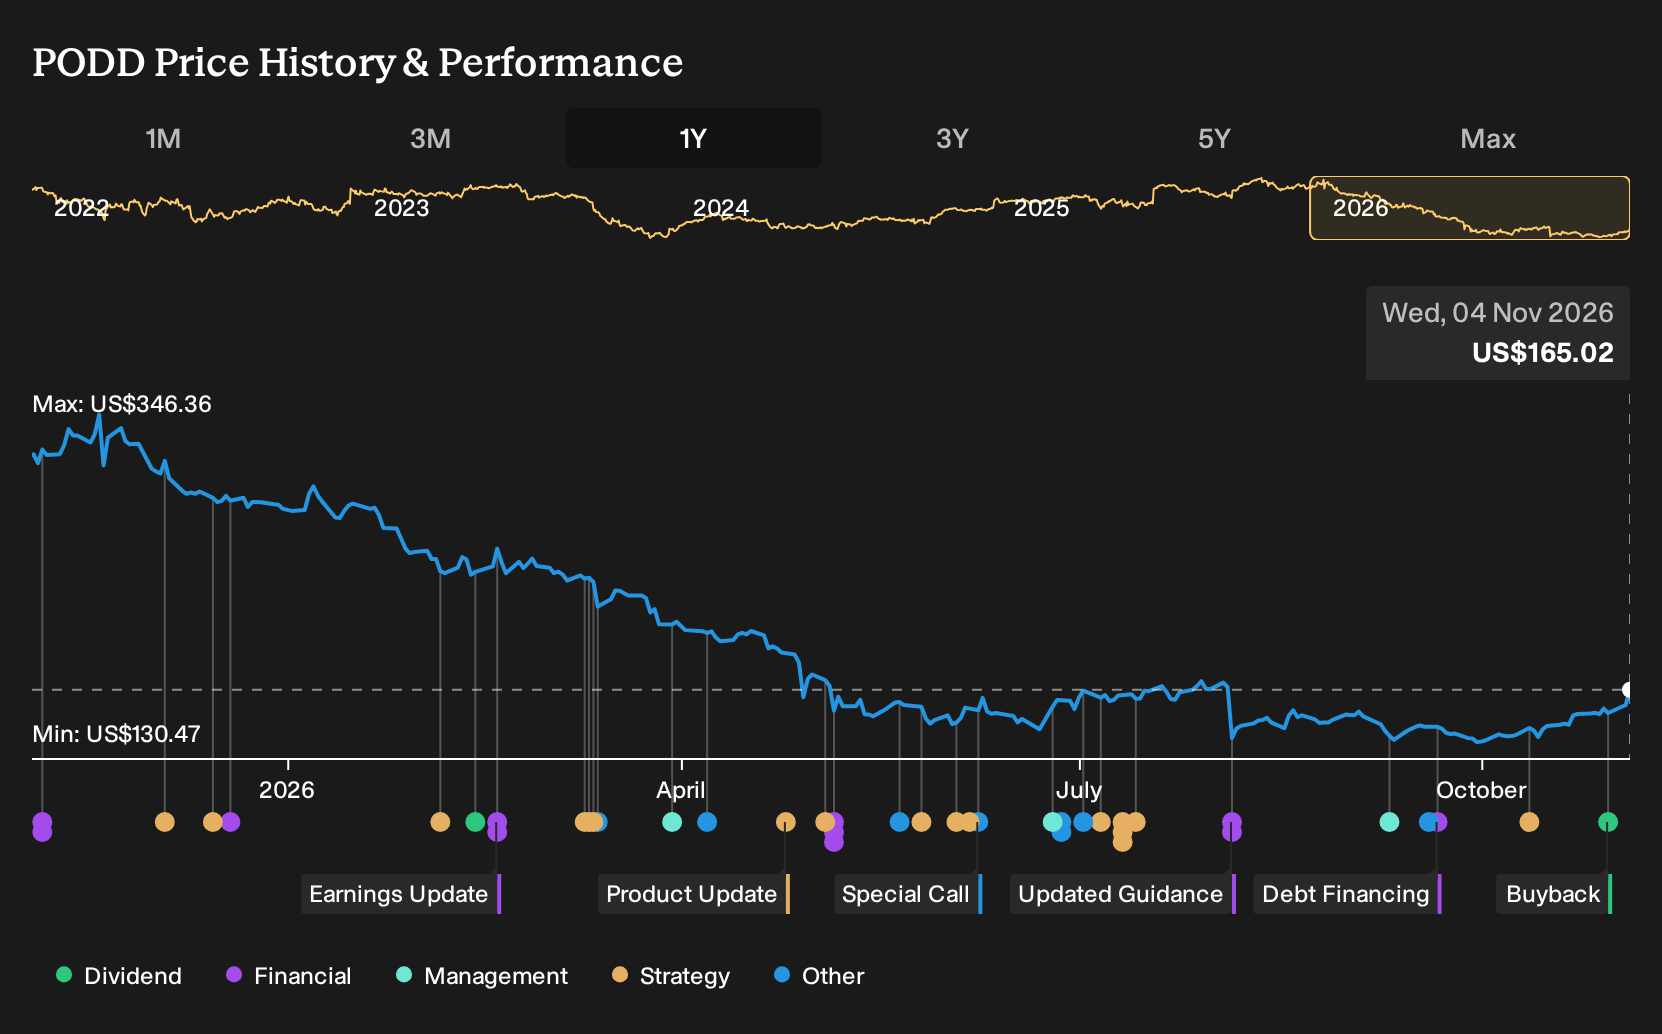
Exploring Other Perspectives
One alternate view puts more weight on the risk that Omnipod adoption in type 1 slows. The lowest analysts were working off roughly 10.1% yearly revenue growth and earnings of about US$682.2m by 2029 before this Q3 beat and US$1b buyback. Use that as a reference point and compare several narratives for Insulet.
Explore 4 other Insulet fair value estimates, including one that suggests as much as 27% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Insulet research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Insulet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insulet's overall financial health at a glance.
Looking For More Investment Ideas Beyond Insulet?
If Insulet has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you quickly surface other stocks that fit your style and risk comfort.
- If you care most about quality at a reasonable entry point, scan a curated 35 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect them yet.
- For investors who put resilience first, filter for companies with steadier profiles using a 31 resilient stocks with low risk scores that highlights businesses with lower risk scores.
- If balance sheet strength is your anchor, focus on a list of solid balance sheet and fundamentals (24 results) so you can zero in on companies with stronger financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com