


EN
Tripadvisor (TRIP) Stock Still Looks Like A Bargain Today
Tripadvisor has seen a sharp share price reset over the past few years, and with fresh questions around traffic from Google’s AI Overviews, investors are increasingly asking whether the current US$10.20 price still lines up with what the business generates in sales.
- The stock has fallen 67.0% over the past 5 years, which puts the focus squarely on whether the revenue it brings in can still justify even this lower equity value.
- Management has pointed to fewer casual visitors arriving from Google search after AI Overviews, which can affect how efficiently Tripadvisor converts its audience into revenue and may influence what multiple investors are willing to pay for its sales.
- Your read on Tripadvisor is one view; the desks covering it have another. See what analysts think Tripadvisor's shares could be worth.
For investors, the debate is whether Tripadvisor’s current market value is appropriately supported by its sales, given both the long slide in the share price and the shifting traffic backdrop.
If you are weighing Tripadvisor against other ways to play the AI traffic shake up, a focused stock screen of 41 AI small caps can be a useful second starting point for research.
Is Tripadvisor a Bargain on Sales?
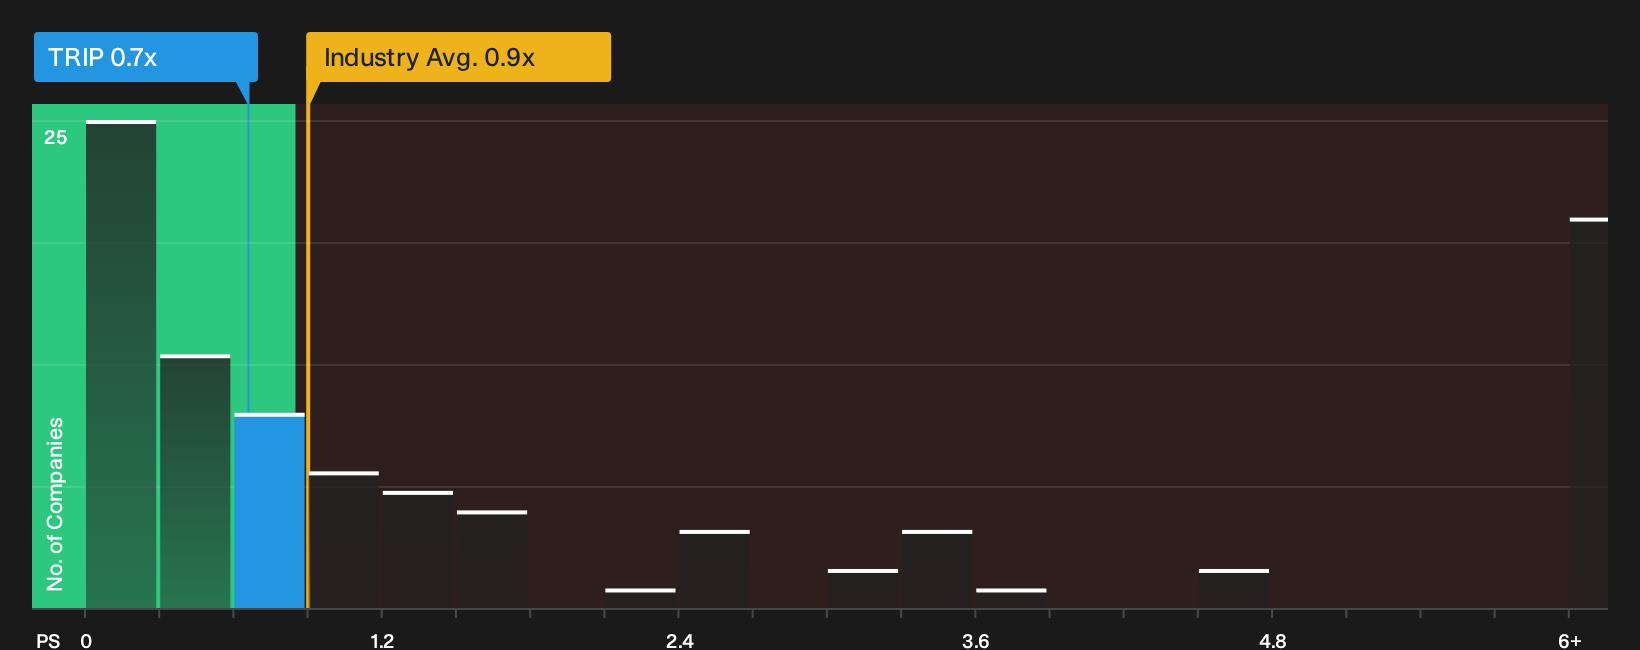
P/S works well for Tripadvisor because investors are weighing the value of its traffic and transactions relative to the revenue they create, especially with earnings distorted by one off factors. On this yardstick, the stock trades on a P/S of 0.7x, below both the Interactive Media and Services industry average of 0.9x and the peer group around 1.3x. The fair value framework, which blends the company’s growth profile, profitability, size and risk into a tailored “expected” multiple, also indicates that the current P/S is on the cheaper side of where it might usually trade.
Because management has already flagged softer “drive by” visitors from Google’s AI Overviews, this discount suggests the market is already incorporating traffic risk into what it is prepared to pay for Tripadvisor’s revenue. That gap between today’s P/S and the level implied by the model is what readers need to examine more closely to decide whether it reflects caution on AI related disruption or an overly pessimistic read on the travel platform’s future revenue power. Explore the numbers behind Tripadvisor's P/S valuation.
The Tripadvisor Narrative: What Would Justify Today's Price?
Tripadvisor Narratives on Simply Wall St pick up where the valuation puzzle leaves off by explaining which growth, margin and earnings paths would need to occur for the stock to be worth materially more or less than today’s market price. Each scenario links its figures to a clear view of how Tripadvisor’s revenue mix, profitability and risk profile might change, giving you something concrete to revisit as new information becomes available.
The community is split on Tripadvisor, with one camp seeing underappreciated Experiences and AI upside while the other worries the traffic and margin drag already tells the story.
Bull case: 26% undervalued
"Tripadvisor's focus on scaling its experiences marketplace through Viator and Tripadvisor Experiences now rests on a business that generated over US$4.7b of experiences gross booking value in 2025..."
Discover why this Narrative puts Tripadvisor at 26% undervalued.
Bear case: 27% overvalued
"Bearish analysts expect Tripadvisor's legacy hotels and media businesses to keep losing high margin traffic as SEO and AI driven changes to search behavior continue to weigh on revenue..."
Explore why this Narrative puts Tripadvisor at 27% overvalued.
One more piece of the Tripadvisor puzzle worth checking
Valuation only tells you what the market is paying today, while the analyst models for Tripadvisor a few years out give you a separate yardstick to compare against that price. Explore where analysts expect Tripadvisor to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com