


EN
Fabrinet Stock Is The Bull Case Changed After Record Results And Strong Guidance
- Fabrinet reported record Q1 FY2027 results, with US$1.474b in sales, US$103.5m in net income and GAAP diluted EPS of US$2.86. The company also issued Q2 guidance for US$1.6b to US$1.65b in revenue and GAAP EPS of US$3.81 to US$3.96 as of early November 2026.
- The business is rapidly adding manufacturing capacity and highlighting new data center optics and optical switch programs. Together, these developments indicate that management is aligning Fabrinet’s operations with rising demand across AI focused data center, communications, automotive and industrial customers.
- We will now look at how Fabrinet’s investment narrative could be affected by its record Q1 results and strong Q2 guidance.
Scan other AI focused hardware plays moving on similar data center demand with our curated list of 53 AI infrastructure stocks.
Fabrinet Investment Narrative Recap
To own Fabrinet, you need to be comfortable with a business that is tightly linked to AI heavy data center and communications projects and is expanding factories ahead of fully proven utilization. The Q1 FY2027 record quarter and strong Q2 outlook keep the main near term catalyst squarely on how quickly new optics and switch programs translate into sustained, repeat orders.
The biggest risk still sits with concentration in a handful of very large customers and the possibility that component tightness or program shifts leave some of the new capacity underused. Recent results do not remove that concern. They simply show the company is operating into strong demand today while carrying meaningful execution risk on those expansions.
The clearest announcement to focus on is Fabrinet’s Q2 FY2027 guidance for US$1.6b to US$1.65b in revenue and GAAP EPS of US$3.81 to US$3.96. That update ties directly to the data center and transceiver programs that management has been talking about and gives investors a concrete near term check point on how those wins are flowing into the income statement.
This guidance also matters for risk assessment. If the firm delivers within that range while continuing to ramp capacity in Thailand and the US, it supports the idea that new buildings and program wins in hyperscale transceivers and optical switches are tracking close to plan. Any shortfall would quickly refocus attention on customer concentration, component availability and the payback on the recent build out.
What Analysts Are Baking Into The Fabrinet Story
Fabrinet's narrative projects US$9.1b in revenue and US$930.8m in earnings by 2029. Analysts are assuming revenue growth of 25.1% per year, with earnings rising by roughly US$457.8m from US$473.0m today to reach that level.
Uncover why Fabrinet's fair value indicates a 96% potential upside to its current price, which could narrow quickly.
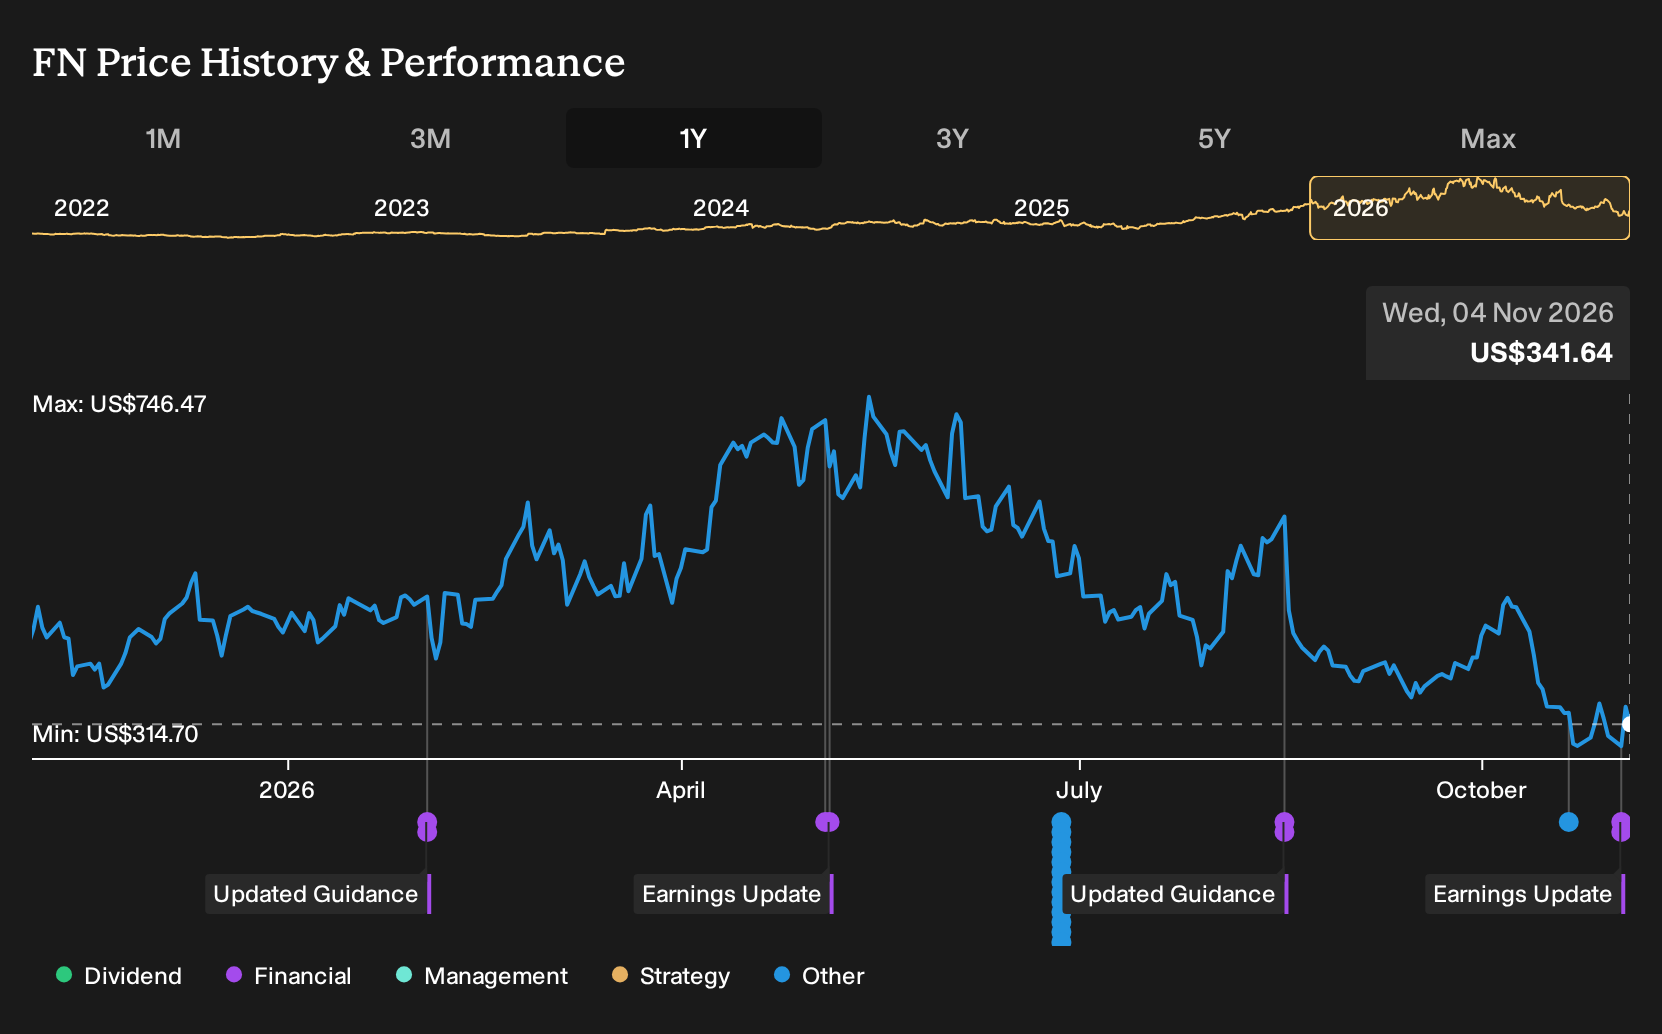
Exploring Other Perspectives
One alternate take on Fabrinet leans hard on the risk that heavy factory spending fails to translate into strong free cash flow. Before this Q2 guidance and Q1 print, the most cautious analysts were working off about US$9.0b in 2029 revenue and US$976.9m in earnings. That group pins its lower price target on a much cheaper 20.3x P/E, and assumes the stock already bakes in big capacity utilisation gains. You can use this more pessimistic path as a reference point, then decide whether the fresh guidance justifies revisiting those older assumptions.
Explore 8 other Fabrinet fair value estimates, including one that suggests it could be worth just $431.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fabrinet research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Fabrinet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fabrinet's overall financial health at a glance.
Looking For More Ideas Beyond Fabrinet?
If Fabrinet has sharpened your focus on where capital-intensive growth stories can lead, it can be useful to line it up against other opportunities with very different risk and income profiles. The Simply Wall St Screener lets you filter for themes and balance sheet traits so you can build a watchlist that actually fits your goals, instead of copying the crowd.
- For investors who want potential upside with strict quality filters on financial strength, check out our curated 19 high quality undiscovered gems and see which smaller companies still fly under most radars.
- If capital preservation and resilience sit at the top of your checklist, focus on businesses that clear our stability tests and review the 31 resilient stocks with low risk scores that emerge from that process.
- For readers aiming to pair quality with ongoing income, you can narrow the field to companies offering meaningful yields and consistent payments by scanning our 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com