


EN
SolarEdge Stock After Narrower Losses and Mixed Sales In Earnings Report
- SolarEdge Technologies reported third quarter 2026 results, with sales of US$326.08 million compared with US$340.18 million a year earlier and a net loss of US$8.39 million compared with a loss of US$50.06 million.
- Over the first nine months of 2026, SolarEdge Technologies recorded sales of US$982.82 million versus US$849.09 million a year before and a significantly smaller cumulative net loss of US$96.5 million compared with US$273.33 million, reflecting changes in cost control and operations.
- Next, the focus shifts to how SolarEdge Technologies' sharply narrowed losses, alongside mixed revenue trends, may influence the broader investment narrative.
Compare SolarEdge Technologies' earnings reset with other power and grid players by scanning the 41 power grid technology and infrastructure stocks that filters for listed operators across related technologies.
What Is SolarEdge Technologies' Investment Narrative?
To own SolarEdge Technologies, you need confidence that a loss making but scaled energy hardware platform can tighten execution while demand and pricing stay rational enough to support that effort. The latest quarter fits that story only partly. Sales for the period eased year on year, yet the loss shrank sharply, which points to cost control and operational adjustments taking hold even as the revenue line moves unevenly.
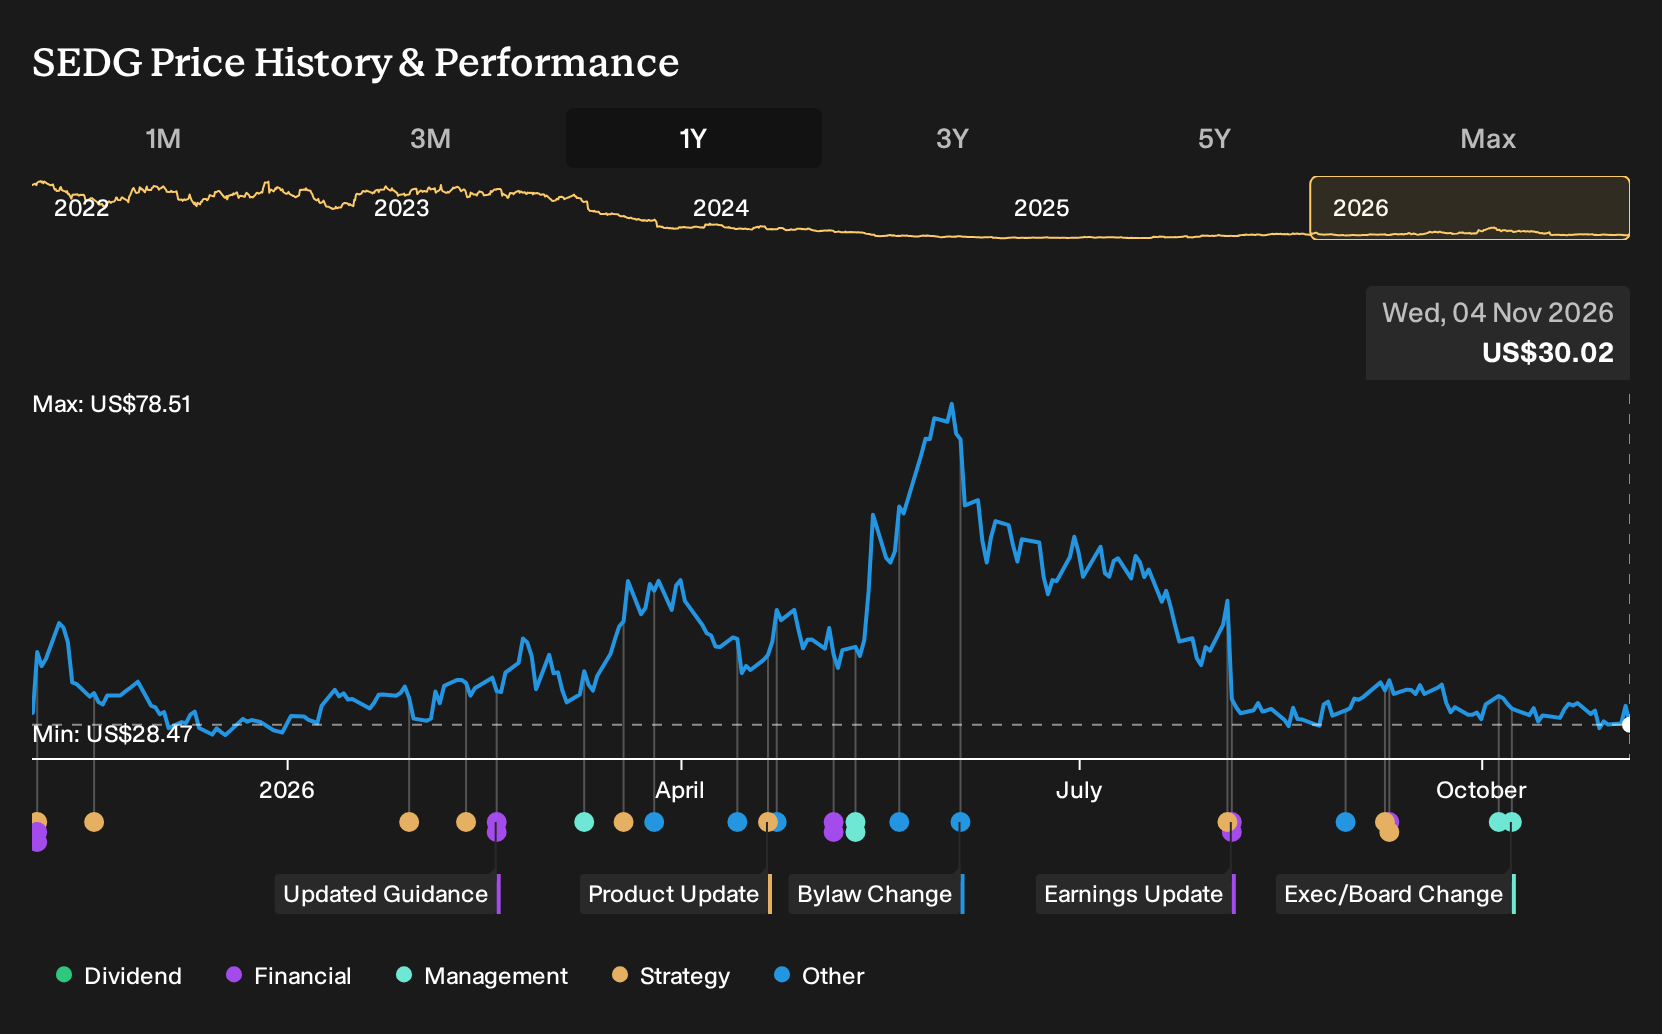
In the short term, the key questions are about order flow and pricing for inverters, optimizers, storage, and related services, as well as how much capital SolarEdge Technologies must keep committing to inventory, manufacturing, and product support while it remains unprofitable. Management now has some proof of reduced burn over nine months, but the share price has been volatile and the business still carries higher risk funding with no customer deposits underpinning the balance sheet.
That said, there is a less comfortable wrinkle once you set those improving loss figures against the longer record of rising cumulative losses and...
There's only one way to know the right time to buy, sell or hold SolarEdge Technologies. Head to Simply Wall St's company report for the latest analysis of SolarEdge Technologies's Fair Value.
Exploring Other Perspectives
SolarEdge Technologies looks very different if you focus on the risk that storage and AI data center projects slip. The most bearish analysts were modelling only about 3.8% annual revenue growth and no profit over the next 3 years, yet still pencilled in about US$1.5b of sales and US$299.6 million of earnings by 2029. Their view had not factored in this latest earnings report, so treat it as one starting point and compare it with other opinions before deciding how this new information might shift your own narrative.
Explore 3 other SolarEdge Technologies fair value estimates, including one that suggests there could be as much as 7% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SolarEdge Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SolarEdge Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SolarEdge Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond SolarEdge Technologies?
If SolarEdge Technologies has sharpened your interest in power, grid, and energy hardware exposure, it can help to widen the lens and compare it with other businesses that share some financial traits but sit in very different niches.
- If capital preservation is your priority, take a look at 31 resilient stocks with low risk scores that may suit a more cautious approach.
- If you prefer resilient balance sheets and cleaner fundamentals, the list of solid balance sheet and fundamentals (24 results) can help surface candidates worth a closer look.
- If you are hunting for under followed opportunities with stronger underlying numbers, the 19 high quality undiscovered gems could highlight ideas that are not yet widely discussed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com