


EN
Is Earnings Beat Altering The Investment Case For Rush Enterprises (RUSH.A)?
- Rush Enterprises reported third quarter 2026 revenue of US$2,113.1 million and net income of US$78.04 million, with earnings per share from continuing operations between US$0.65 and US$0.67. The board declared a US$0.14 quarterly dividend per Class A and Class B share to be paid in December 2026.
- The latest update showed solid contributions from new truck deliveries and aftermarket services. Management also flagged slower customer ordering tied to supply chain constraints and uncertainty around upcoming EPA 2027 emissions rules.
- We will look at how Rush Enterprises' investment narrative aligns with stronger Q3 aftermarket demand, while customer orders pause amid EPA 2027 uncertainty.
Scan other truck dealers and capital goods operators facing similar order pauses and regulatory questions with our curated list of list of solid balance sheet and fundamentals (24 results).
Rush Enterprises Investment Narrative Recap
To own Rush Enterprises, you need to believe its aftermarket and leasing operations keep doing the heavy lifting while truck buyers sit on their hands waiting for EPA 2027 clarity. The latest quarter showed that parts and service can support the story when new orders slow, so the near term catalyst still hinges on fleets finally releasing deferred replacement demand.
The biggest risk has not changed. Prolonged regulatory uncertainty or a weak freight backdrop could keep medium duty and new truck orders muted, which would cap how much Q3 momentum in revenue and earnings can help. If that standoff drags on, aftermarket strength may only partly offset softer vehicle sales.
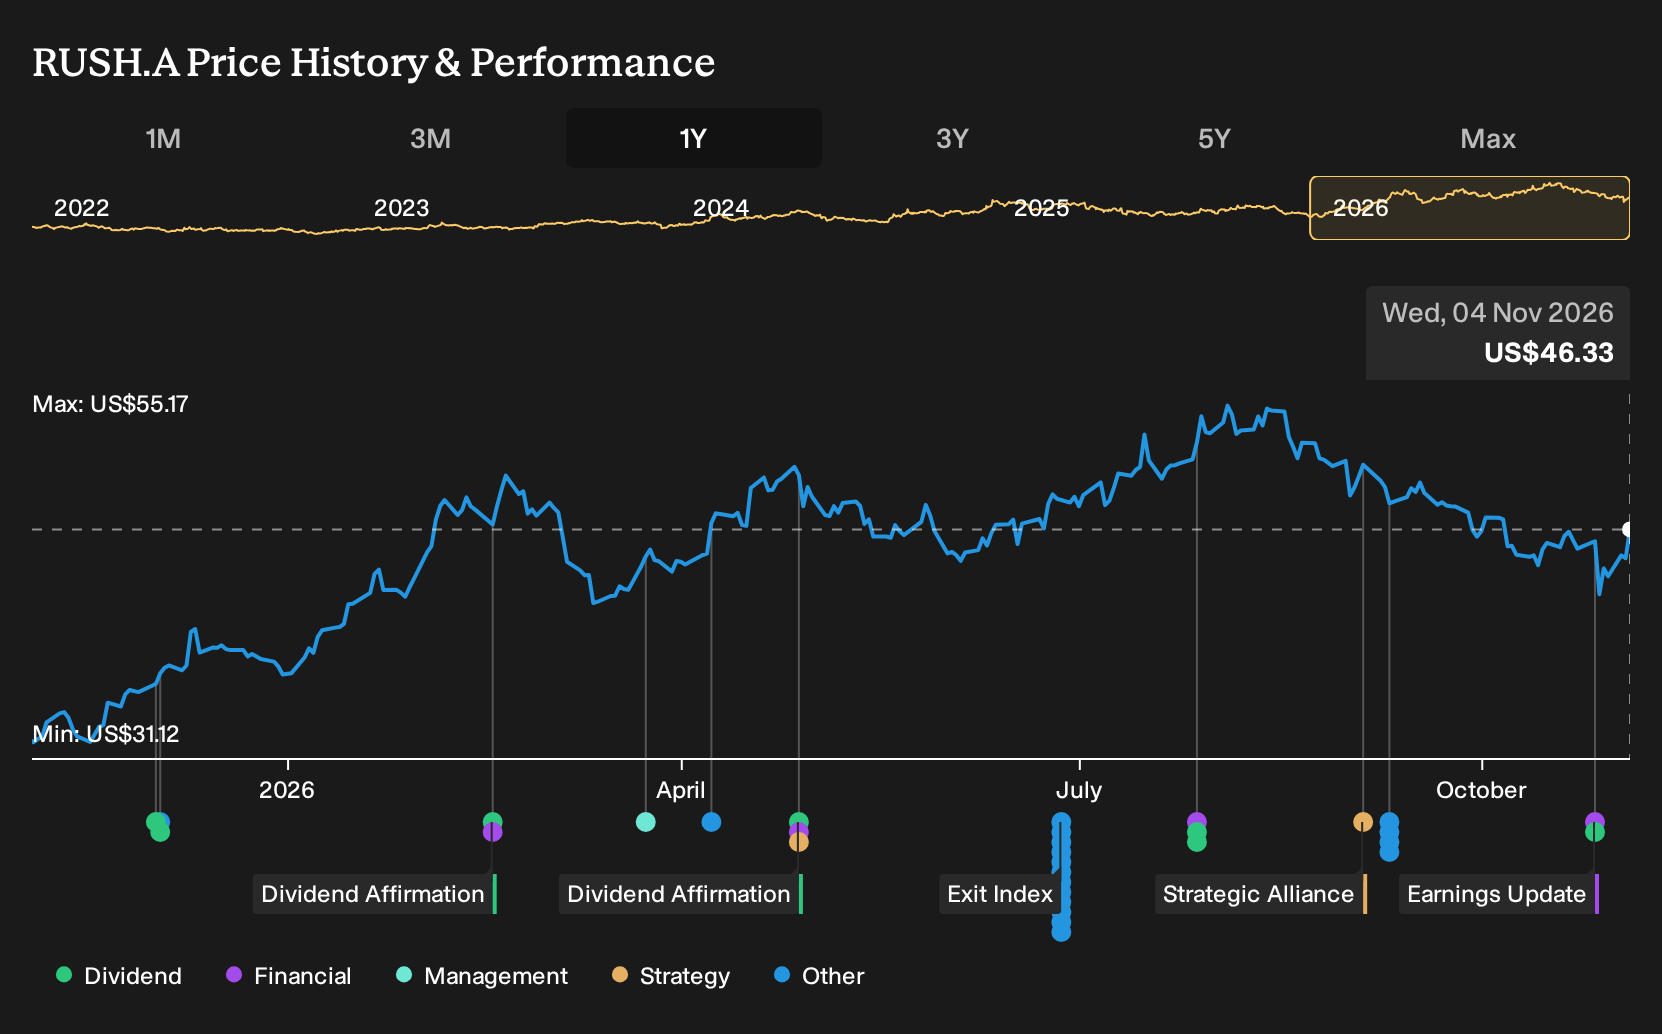
The dividend affirmation looks most relevant right now. A US$0.14 quarterly payout, with payment scheduled for December 10, 2026, points to management keeping capital return steady while working through delayed customer ordering and supply chain friction. For you as a shareholder, that puts some emphasis on cash generation and balance sheet resilience while waiting for clearer emissions rules.
That payout also sits alongside an active repurchase program, with 229,904 shares bought back for US$15.79 million under the existing authorization. Both moves tie the catalyst back to execution. The business needs to keep turning its 2026 revenue base of about US$7.5b into consistent free cash, so it can handle potential order softness while still investing in the dealership network.
Rush Enterprises' narrative projects US$9.8b revenue and US$386.5 million earnings by 2029. This assumes 10.6% yearly revenue growth and about a US$121.3 million earnings increase from US$265.2 million today.
Uncover why Rush Enterprises' fair value indicates a 22% potential upside to its current price before the gap closes for Rush Enterprises.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Rush Enterprises as a prebuy winner. They were sketching out roughly US$10.6b of revenue and US$377.2 million of earnings by 2029, before this dividend and Q3 report, and assume tighter emissions rules could spark stronger cycles. You are seeing one data point that might reshape that story.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rush Enterprises research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rush Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rush Enterprises' overall financial health at a glance.
Looking For More Ideas Beyond Rush Enterprises?
If you like the aftermarket and capital allocation story at Rush Enterprises but want a wider bench of opportunities, the Simply Wall St Screener can help you line up other businesses with balance sheets and fundamentals that fit your style.
- If capital preservation comes first for you, start with companies that pair resilience with stability through the 31 resilient stocks with low risk scores.
- For income focused investing, broaden your watchlist with companies that combine robust yields and consistent shareholder payouts via the 5 dividend fortresses.
- If you are hunting for potential future leaders that are not yet widely followed, cast a wider net with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com